


Metro (HMSE:B4B0) Stock Still Looks Cheap As Its 32% Gain Faces Russia Risk
Metro shares have delivered a 32.5% return over the past year, which puts the focus squarely on whether that move is supported by the wholesaler's underlying sales. With fresh political pressure on its Russian operations, the stock now raises a straightforward question for you as an investor: how much of Metro's current price can be explained by the revenue its business is actually generating?
- The 32.5% 1 year gain has reshaped recent holders' returns and makes it important to ask whether Metro's current valuation is anchored in its sales base.
- The Kremlin's decision to place Metro's Russian business under temporary administration may affect how much revenue the group can reliably turn into future cash flows and where investors think sales growth can realistically come from.
- Before you settle on a price for Metro, see what its peers cost. See how Metro's 0.1x P/S compares with its peers.
For investors, the debate is whether Metro's current share price can be justified by its sales when set against the industry average.
If this Russian headline has you rethinking how much sales risk you want in your portfolio, a focused stock screen is a useful second opinion. You can start with 222 resilient stocks with low risk scores.
Is Metro Still Cheap on Sales?
P/S is the cleaner yardstick for Metro because wholesalers tend to convert a relatively small slice of turnover into profit, which can make earnings-based ratios noisy.
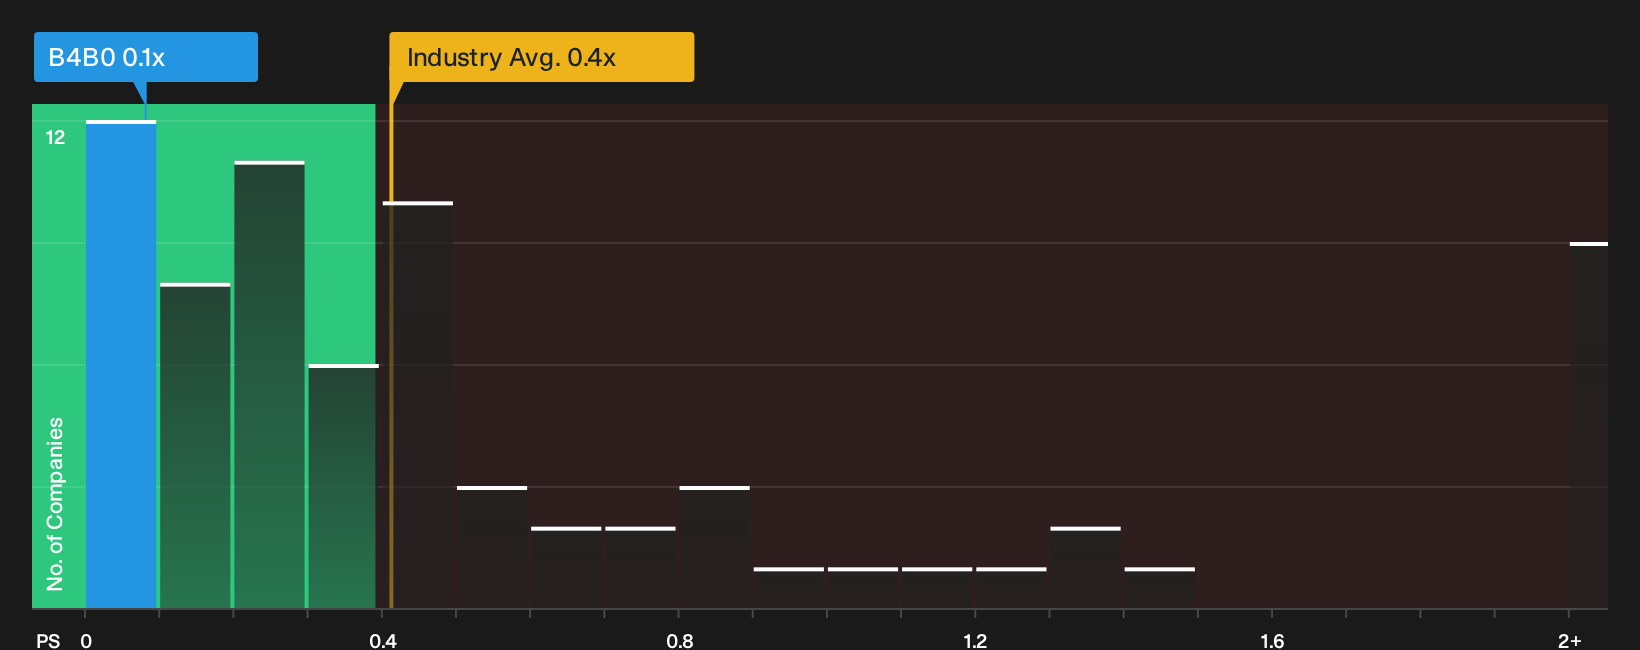
On this measure, Metro trades on a P/S of 0.1x, which is below both the broader consumer retailing industry average of 0.4x and the peer group at roughly 0.2x. That gap means the market is currently paying less for each euro of Metro revenue than for comparable wholesalers and retailers.
Because the Russian arm has been placed under temporary administration, this discount likely reflects concern about how dependable a portion of Metro's turnover now looks and how much of that top line can be converted into cash. For you as a shareholder or potential buyer, the low sales multiple only becomes attractive if you are comfortable with the concentration of risk and the quality of the remaining revenue base. Explore the numbers behind Metro's P/S valuation.
The Metro Narrative: What Would Justify Today's Price?
Metro's Simply Wall St Narratives pick up where the P/S debate leaves off. They spell out which paths for revenue, margins and earnings would need to occur for the stock to look much stronger or much weaker than the current share price implies, and each narrative ties a fair value to a clear story about Metro's potential catalysts and key risks, so you can track which version comes closer to reality over time on the Community page.
A written, number driven view on Metro gives you a clear way to spell out what would need to happen after Russia's temporary administration of its local arm for today's sales multiple to make sense. It also forces those assumptions into the open so you can revisit them as fresh results and updates on the Russian operations arrive.
Share your own Narrative for Metro and set out the assumptions behind your valuation.
Before you move on from Metro, there is one more check to weigh
Price and sales only tell part of Metro's story, because Simply Wall St's broader review has also flagged specific concerns that deserve a look alongside the valuation picture. Take a closer look at 2 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com