


Nexans (ENXTPA:NEX) Could Be 23% Undervalued As Leadership Shifts In Northwest Africa
Nexans (ENXTPA:NEX) has reshuffled leadership in Northwest Africa after the board approved Amine Houssaim as General Director for both the regional business unit and Nexans Maroc, with Noureddine Aouda stepping in as Deputy General Director.
The leadership reshuffle comes at a time when Nexans shares trade at €129.3 and short term momentum has softened. The 7 day share price return of 5.21% and the 30 day share price return of 6.64% have both moved lower, while longer term total shareholder return over three and five years, at 111.51% and 71.77%, indicates that investors have been rewarded over time.
Scan 43 power grid technology and infrastructure stocks to see which other electrification players investors are watching alongside Nexans as grids modernize and capital tracks long term infrastructure projects.
Nexans has delivered strong multi year shareholder returns even as recent momentum cooled, and fresh leadership in Northwest Africa adds another layer to the story. Are you paying for fundamentals, or for a swing in sentiment?
Most Popular Narrative: 23% Undervalued
Nexans is framed as undervalued in the most followed narrative, with a fair value of €168 against the last close at €129.3. This puts a spotlight on how electrification and balance sheet strength are being weighed against known risks.
The ongoing acceleration of global electrification, renewable energy adoption, grid modernization, and significant investments in infrastructure (especially in Europe and emerging markets) continue to drive strong organic growth in Nexans' Electrification, Power Grid, and Transmission segments, supporting a robust order backlog and increased revenue visibility for coming years.
Nexans' strategic transformation into a near pure-play electrification company, combined with sustained focus on high-value-grid, offshore wind, and specialty cabling solutions, positions the company to benefit from expanding high-margin market opportunities and structurally improve group net margins.
See why 11 investors see Nexans as 23% undervalued.
Result: Fair Value of €168 (UNDERVALUED)
Still, Nexans faces pressure if raw material costs stay volatile or if large acquisitions create integration snags that drag on margins and cash generation.
Find out about the key risks to this Nexans narrative.
Another View On Nexans Valuation
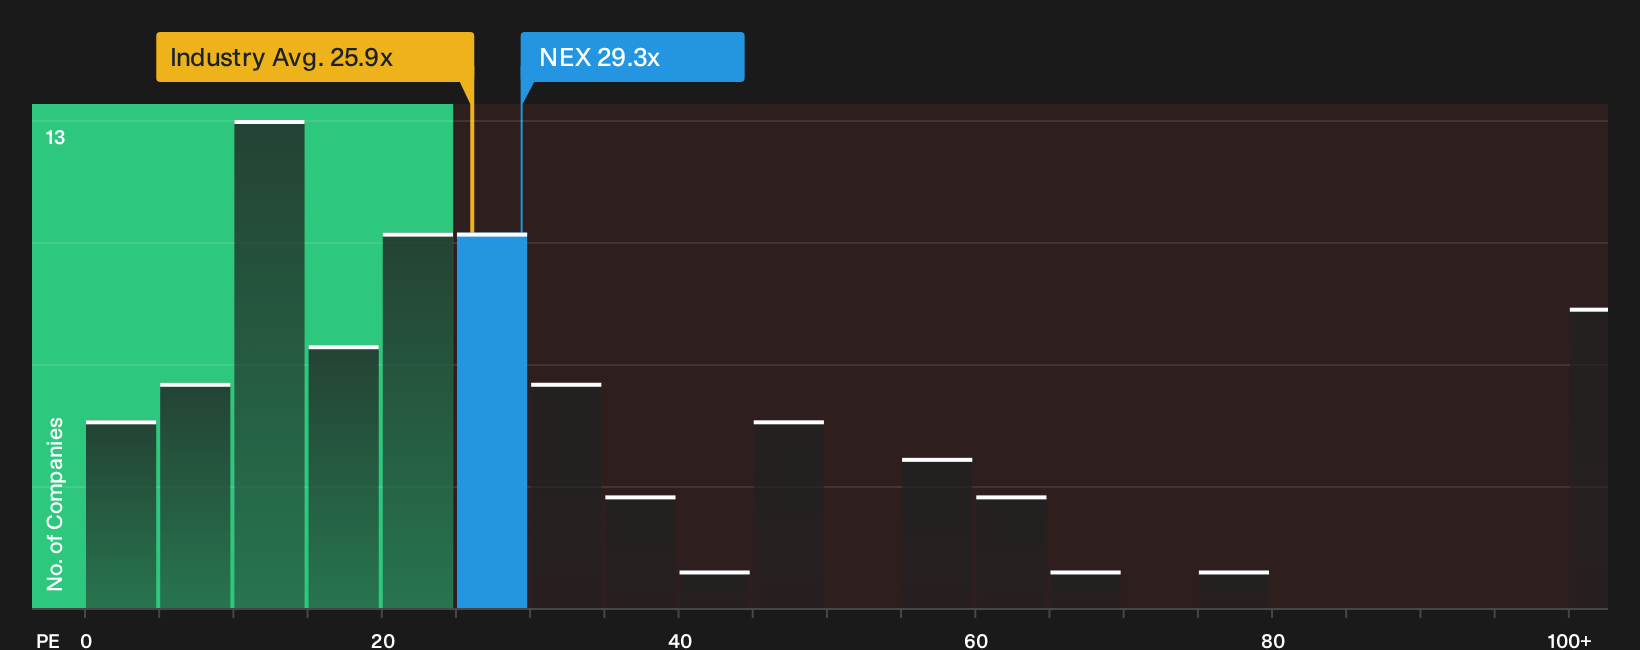
On the flip side of that €168 fair value narrative, Nexans currently trades on a P/E of 29.3x compared with 25.9x for the European Electrical industry, while its fair ratio is estimated at 26.4x. That premium suggests there is less margin for error if the story encounters setbacks.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If Nexans appears both promising and complex after this, that is intentional. It is therefore important to act promptly and consider the 4 key rewards and 2 important warning signs.
Looking for more Nexans investment ideas?
If Nexans has sharpened your focus on electrification, do not stop there. Broaden your watchlist with targeted screeners that surface focused ideas before others spot them.
- Target potential mispricing by scanning companies flagged as quality opportunities on the 175 high quality undervalued stocks.
- Prioritize resilience by reviewing the list of solid balance sheet and fundamentals (204 results) to find businesses with stronger financial foundations.
- Get ahead of the crowd by checking the 618 high quality undiscovered gems that combine fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com