


Is Tractor Supply (TSCO) Fairly Valued Following Its New Nampa Distribution Center Opening?
Tractor Supply (TSCO) just opened its 11th distribution center in Nampa, Idaho. The 865,000 square foot hub uses automation and an AI innovation team to support more stores across the Northwest.
For context, Tractor Supply’s share price has climbed 2.95% in the last day and 5.52% over the past week, yet the 30-day share price return is down 5.13%, and the year to date share price return has declined 34.13%, with a 1-year total shareholder return down 36.77% and a 5-year total shareholder return down 6.92%. This points to recent momentum picking up after a longer stretch of weaker performance as the market weighs new projects such as the Nampa distribution center and the upcoming third quarter 2026 results on October 22.
Spot fresh momentum stories like Tractor Supply’s Nampa buildout and compare them with other retailers ramping capacity and automation through our curated list of solid balance sheet and fundamentals (25 results).After Tractor Supply’s sharp bounce off multi‑year share price declines, the gap between the current US$33.48 quote, analyst targets, and intrinsic value estimates matters far more than the new Nampa headlines. Where does fair value actually land?
Most Popular Narrative: 6% Undervalued
On the most followed view, Tractor Supply’s fair value sits at $35.48, a shade above the latest $33.48 close. This view places more weight on cash generation and pet services than on short term comparable sales.
The valuation implies that Tractor Supply is priced as if near term headwinds in core rural and pet categories and softer comparable sales will weigh on the share price more than the potential benefit from its pet ecosystem, delivery capabilities and capital redeployment.
See why 44 investors see Tractor Supply as 6% undervalued.
Result: Fair Value of $35.48 (UNDERVALUED)
Still, if comparable sales weakness deepens or tariff refunds and vendor support fade faster than expected, the current Tractor Supply fair value story could unravel quickly.
Find out about the key risks to this Tractor Supply narrative.
Another View: Tractor Supply Through The P/E Lens
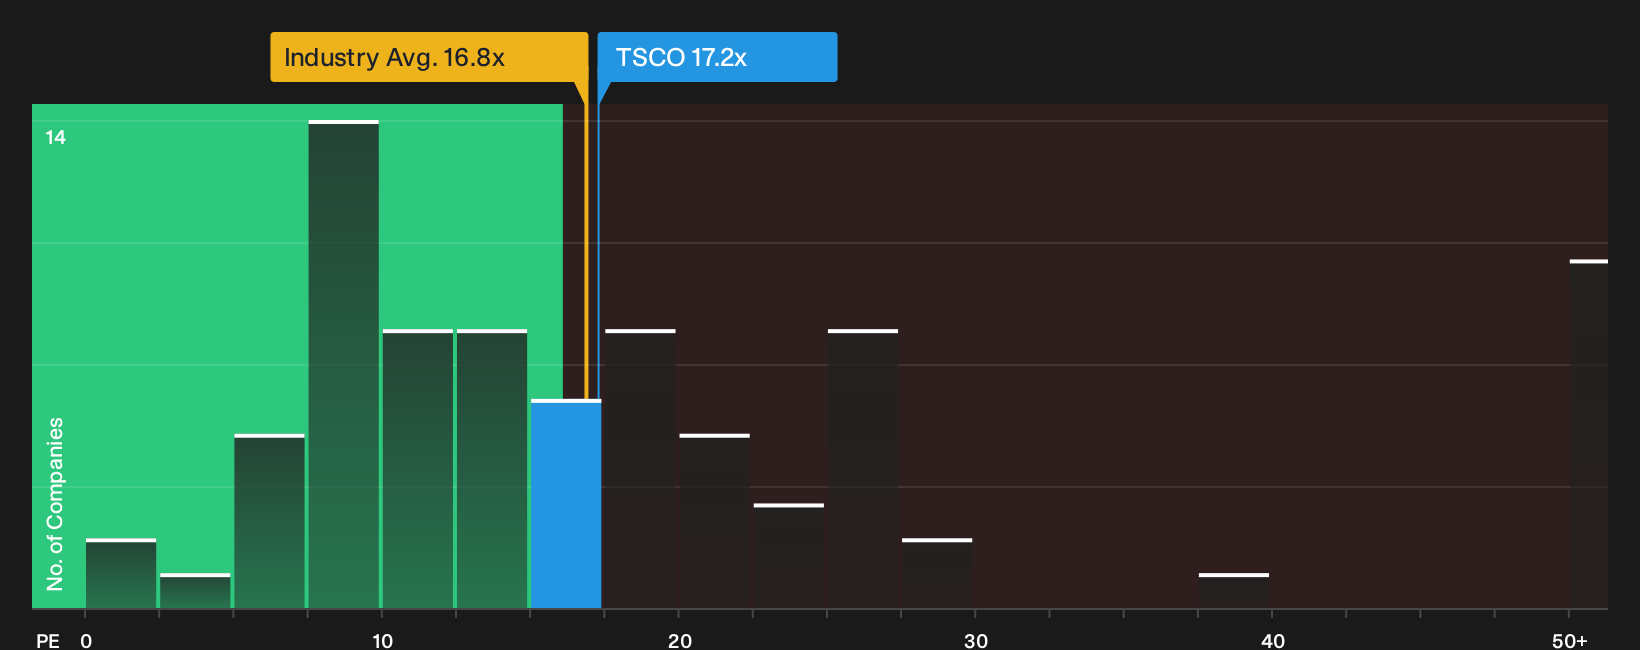
The story shifts when you skip cash flow models and look at Tractor Supply through earnings multiples instead. The stock trades on a P/E of 17.2x, slightly richer than the US Specialty Retail group at 16.8x, yet below its peer average on 20.2x.
The fair ratio for Tractor Supply sits at 15.3x. That is a clear gap. It points to the risk that the market could lean toward that lower multiple if sentiment weakens, or hold the premium if investors stay comfortable paying up. Which path do you think is more realistic?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Tractor Supply is mixed, with real concerns sitting alongside clear bright spots. Move quickly, review the data, and reach your own verdict with 2 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Tractor Supply?
If Tractor Supply has your attention, do not stop here. Use the Simply Wall St screener to line up your next set of candidates across sectors.
- Target dependable balance sheets first and build a watchlist anchored in financial strength with a curated list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a discount and compare Tractor Supply with a focused pool of potentially mispriced opportunities using the 27 high quality undervalued stocks.
- Prioritize resilience and sleep better at night by filtering for steadier profiles through a 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com