


Did MRO Award Win Just Shift Leidos Holdings' (LDOS) Investment Narrative?
- Leidos Holdings recently reported that its Australian Mission Equipment Service Centre was named MRO Business of the Year, while also advancing AI driven cyber offerings and reshaping its security screening portfolio through a joint venture with Altaris.
- The MESC award, entry into the US Navy's NAVSUP program and focus on agentic SOC automation highlight how Leidos is leaning into complex, higher value mission systems work with tight operational execution requirements.
- Next, the focus shifts to how Leidos Holdings' investment narrative could be affected by the MESC recognition and its expanding defense support footprint.
Leidos Holdings Investment Narrative Recap
For a shareholder in Leidos Holdings, the core belief is that complex defense tech, AI-enabled cyber, and energy infrastructure work can offset pressure points in U.S. government health and civilian contracts. The most important short-term catalyst still sits in clean execution on large defense and grid programs, rather than in these corporate announcements, so the direct operational impact looks modest.
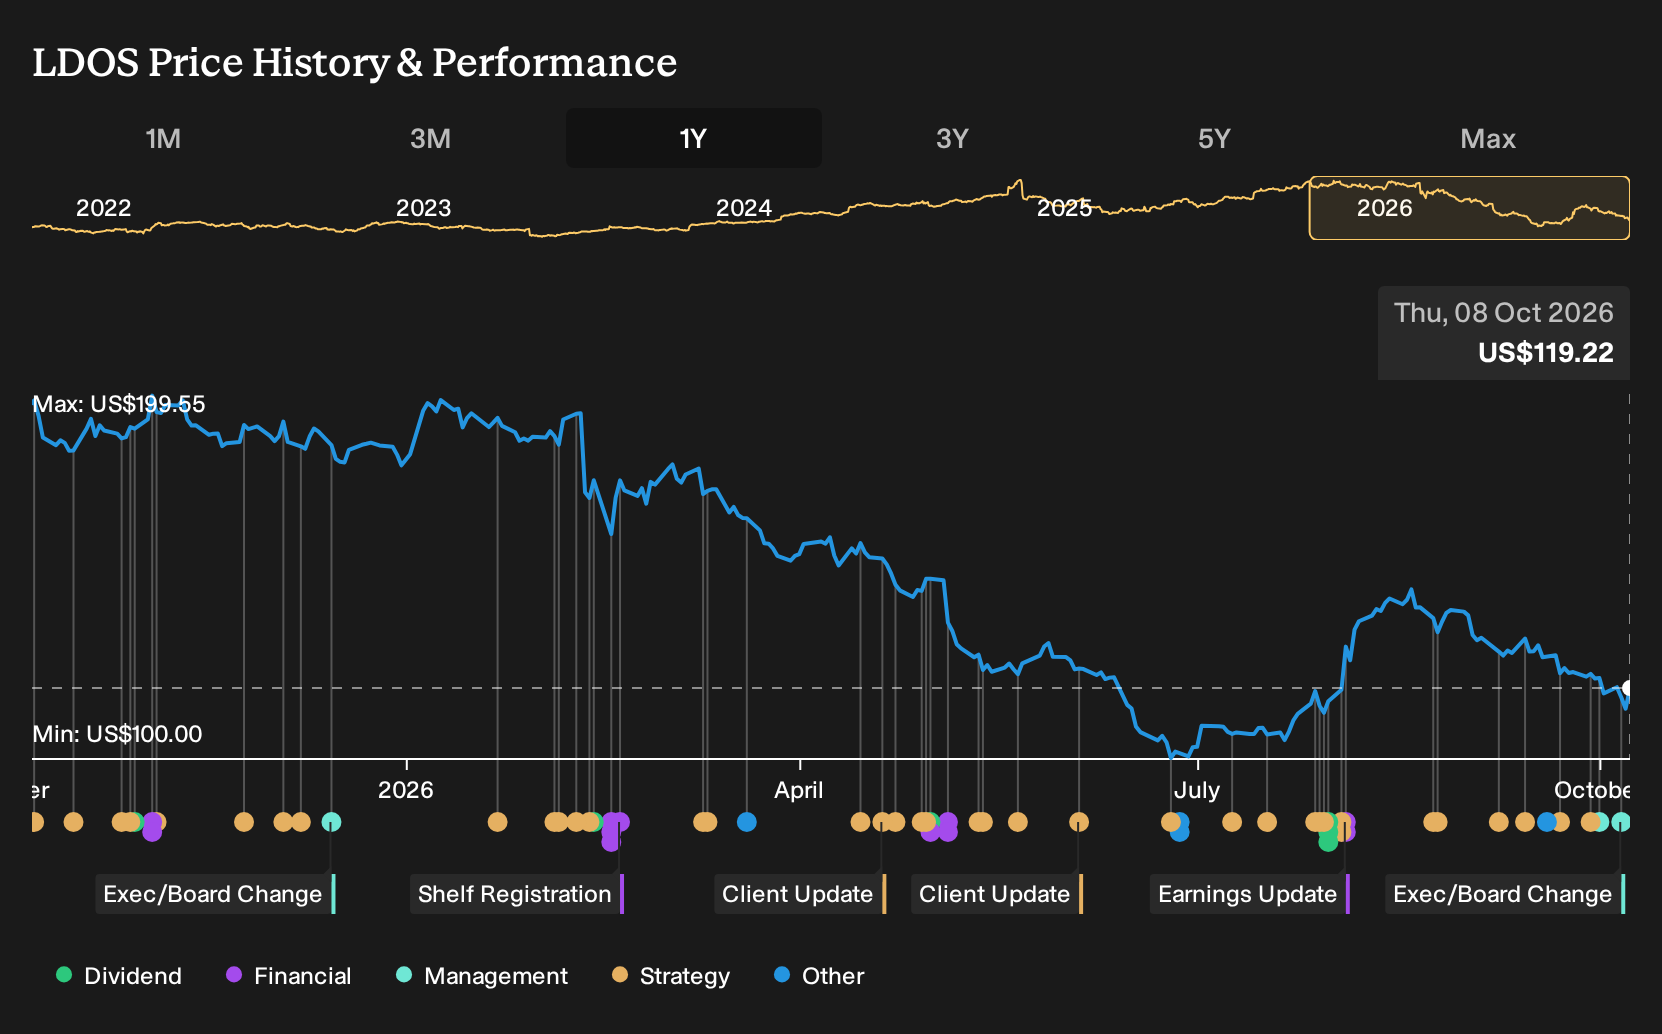
The biggest near-term risk remains funding concentration in U.S. federal budgets, especially as Health margins are already under strain. Recent stock underperformance and high debt levels mean any stumble on contract delivery or sentiment toward government services could weigh on how investors treat the current P/E discount.
The board addition of AT&T COO Jeffery McElfresh is probably the most relevant piece of recent news for the current Leidos Holdings story. His experience with a US$250b connectivity rollout, cybersecurity oversight, and large-scale data operations ties directly into Leidos projects in digital modernization, energy infrastructure, and AI-powered defense systems.
For you, this matters less as a headline and more as an execution signal. Board-level oversight with deep telecom and cyber experience can support decisions around grid projects from Entrust, AI offerings such as UpHold Effect Agentic SOC Automation, and future capital allocation, all of which feed into the key catalysts and existing federal contract risk.
Leidos Holdings' current analyst narrative points to revenues of US$20.7b and earnings of US$1.6b by 2029, built on assumed yearly top line expansion of 5.4% and an earnings increase of about US$200m from US$1.4b today.
Uncover how Leidos Holdings' fair value indicates a 32% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Leidos Holdings’ NorthStar 2030 plan, arguing that stronger AI driven programs and energy projects could justify about US$21.2b of revenue and US$1.9b of earnings by 2029, compared with the baseline US$20.7b and US$1.6b view. The new investor relations leadership and MESC recognition may push these narratives in new directions, so treat this as a reminder that opinions differ widely and are worth comparing yourself.
Explore 2 other Leidos Holdings fair value estimates, including one that suggests up to 93% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Leidos Holdings research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Leidos Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leidos Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Leidos Holdings?
Once you are comfortable with the Leidos Holdings story, it can help to widen the lens and compare it with other opportunities that share some of the qualities you care about most. The Simply Wall St Screener lets you do that quickly by filtering for balance sheet strength, value, income, or whatever else matters to you.
- If capital protection comes first for you, start with a curated group of financially resilient businesses through the 31 resilient stocks with low risk scores.
- For investors who want value-focused ideas, scan a targeted set of companies that combine quality fundamentals with attractive pricing using the 27 high quality undervalued stocks.
- If reliable income is high on your checklist, compare high-yield opportunities and their payout profiles through the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com