


China Resources Power Holdings (SEHK:836) Gains Ground, Is It A Bargain Or Fully Priced?
Without a specific catalyst in focus, China Resources Power Holdings (SEHK:836) draws attention through its mix of thermal and renewable operations, which gives investors multiple revenue streams to evaluate in a single utility stock.
Recent trading has been quietly positive for China Resources Power Holdings, with the share price at HK$19.72 and a 30-day share price return of 4.34% contributing to a 90-day gain of 12.94% and a 1-year total shareholder return of 13.81%. The 3-year total shareholder return of 62.39% suggests that momentum has been building over a longer stretch rather than reversing suddenly.
Scan beyond China Resources Power Holdings and compare its recent momentum with a curated set of utility peers and infrastructure plays in the 43 power grid technology and infrastructure stocks
The steady climb in China Resources Power Holdings, paired with modest revenue and net income growth, raises a simple puzzle. Does the valuation now mirror the underlying mix of thermal and renewable assets, or a mood shift in the market?
Price-to-Earnings of 7.7x: Is it justified?
Valuation on China Resources Power Holdings currently leans on a relatively low P/E of 7.7x, while the shares change hands at HK$19.72 and recent returns have been solid compared with both the Hong Kong market and the regional renewable energy group.
The P/E ratio links the current share price to earnings per share and gives you a simple shorthand for how much investors pay for each unit of profit. For a power producer with both thermal and renewable assets, earnings quality and consistency often matter more than fast top line expansion. A modest earnings multiple can therefore be a focal point for comparison.
Here the comparison is clear. China Resources Power Holdings trades on a P/E of 7.7x, which is far below the Asian renewable energy industry average of 14.3x and also below the peer group average of 11.8x. That discount is also steep relative to the estimated fair P/E of 9.7x, a level the market could move towards if sentiment and fundamentals stay aligned.
Explore the SWS fair ratio for China Resources Power Holdings.
Result: Price-to-Earnings of 7.7x (UNDERVALUED).
Still, the China Resources Power Holdings story can be knocked off course if thermal power weighs on earnings or if policy support for renewables tightens unexpectedly.
Find out about the key risks to this China Resources Power Holdings narrative.
Another View: Our DCF Model Flips The Signal
That low P/E makes China Resources Power Holdings look inexpensive, yet the SWS DCF model tells a different story. With the shares at HK$19.72 and the estimated future cash flow value at HK$18.27, the stock screens as overvalued on this method. Which signal do you trust more?
Look into how the SWS DCF model arrives at its fair value.
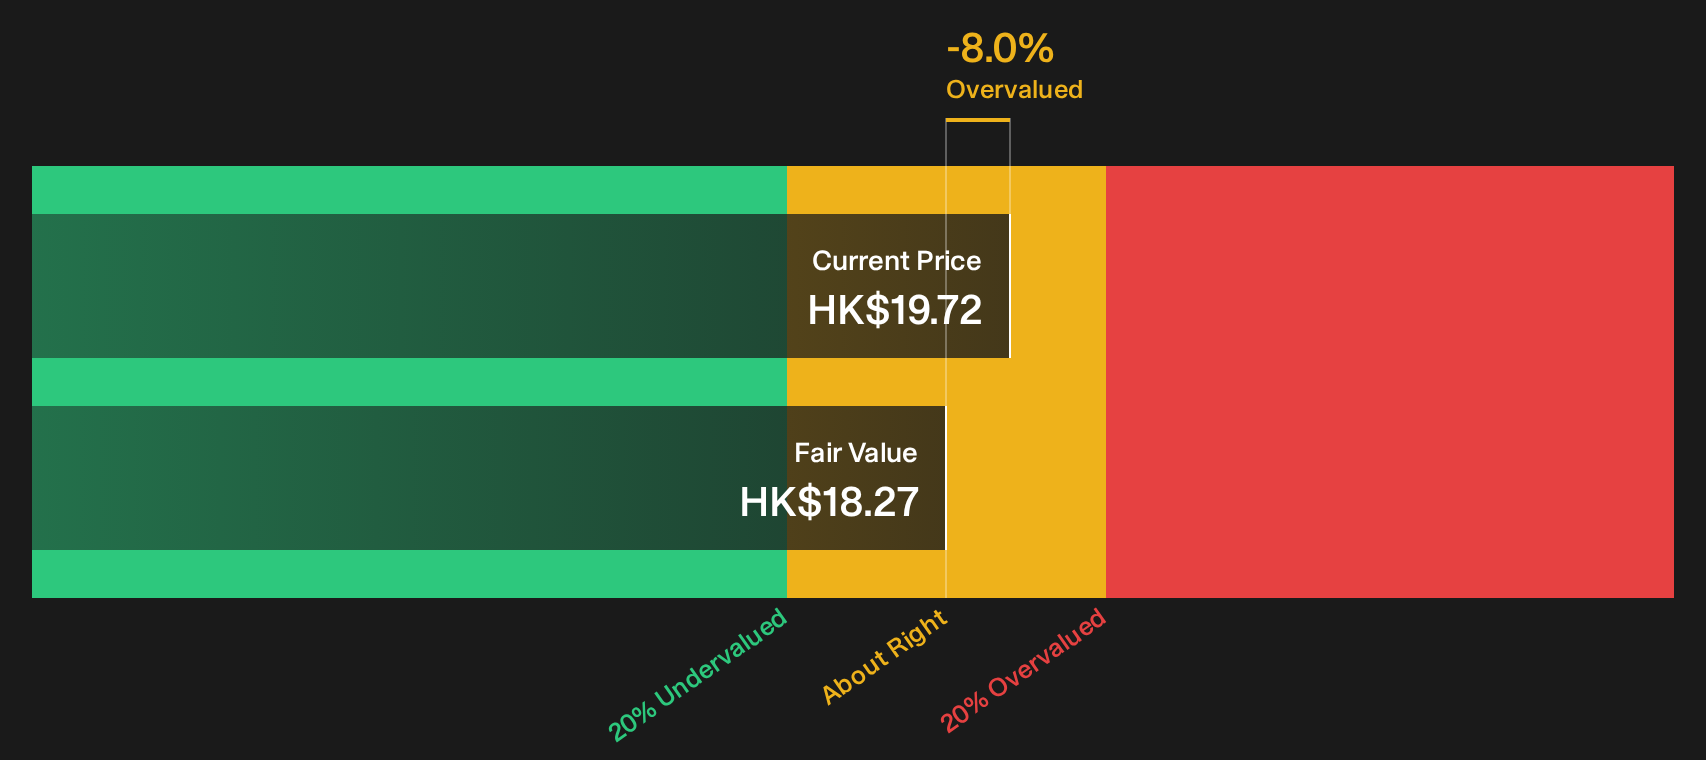
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out China Resources Power Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 177 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of comfort and doubt around China Resources Power Holdings rings true, do not wait for the next headline to decide. Take a few minutes to review the full picture of risks and potential upsides before you adjust your stance with the help of the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond China Resources Power Holdings?
Do not leave your next move to chance when you can systematically scan for fresh opportunities using the Simply Wall Street Screener.
- Target potential mispricing by reviewing the 177 high quality undervalued stocks that pair stronger balance sheets with more conservative valuations.
- Strengthen your income stream by focusing on the 224 dividend fortresses built around higher yields and consistent payment records.
- Dial down portfolio stress by concentrating on the 226 resilient stocks with low risk scores that emphasise resilient business models and cleaner financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com