


Don't just focus on the tech sector! Goldman Sachs is betting on these 10 energy stocks, which skyrocketed by up to 151% during the year and is still calling to buy
The Zhitong Finance App learned that in the fourth quarter of 2026, Goldman Sachs selected 10 individual stocks with attractive risk-return ratios in the energy and power complex, focusing on the continuation of oil and gas exploration and development (E&P) momentum, US electricity and LNG themes, refining sector improvement space, and emotional miskilling of natural gas upstream and midstream natural gas.
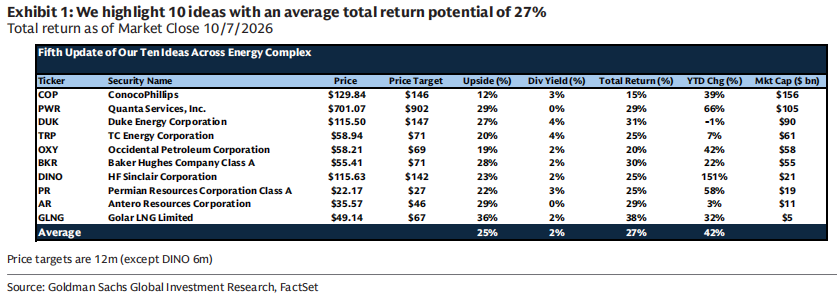
Based on the October 7 closing price, the average total return of these ten stocks is about 27%, with an average annual increase of 42%.
Main line 1: Oil and gas E&P momentum continues, focusing on the inflection point of free cash flow
This offline Goldman Sachs launched ConocoPhillips (COP.US) for the first time. The latest target price is 146 US dollars. The company will usher in a free cash flow inflection point of 7 billion US dollars. Four major projects, NFE, NFS, Port Arthur and Willow, will be put into operation one after another, adding 1 billion US dollars of cost reduction. It is expected to achieve a compound annual increase of 20%-25% of free cash flow per share under the long-term assumption of Brent oil price of 75 US dollars/barrel, and return about 45% of operating cash flow to shareholders. The return ratio is expected to be close to 50% in the second half of 2026; recent catalysts include the winter construction of the Willow project and the first liquefaction production line of NFE in Qatar to be put into operation in 2027.
The latest target price for Occidental Petroleum (OXY.US) is $69. The bank upgraded its rating from “neutral” to “buy” on August 30, and was selected on the American confidence list: the company's 2027/2028 average free cash flow yield is about 13%, which is 11% higher than that of the general market. It plans to increase the sustainable cash flow of 4 billion US dollars by 2030. The total amount of conventional and unconventional resources exceeds 4 billion barrels of oil equivalent, and is expected to reach the $10 billion principal debt target in early 2027.
The latest price target for Permian Resources (PR.US) is $27: The stock has risen 58% during the year, but the bank still expects its compound free cash flow growth rate of about 20% from 2025-2028. The 16% free cash flow yield is significantly higher than 13% of the oily sector. The $1.05 billion reinforcing mergers and acquisitions and the recovery in Permian Waha gas prices during the year brought additional elasticity.
Main line 2: Electricity and LNG topics, power grid and data center construction are the core drivers
The latest target price for Quanta Services (PWR.US) is 902 US dollars: The bank believes that it is the core beneficiary of power grid and data center construction. Large-scale 765 kV transmission projects continue to be implemented, and the power business accounts for about 80% of revenue. The compound annual revenue growth rate is expected to be about 15% before 2030, and the target price corresponds to 30 times the long-term corporate value multiple.
Duke Energy (DUK.US)'s latest target price is $147: It is relatively immune to election risk (North Carolina, the largest jurisdiction, has no governor election this year). It has about 15.4 gigawatts of high-confidence load pipelines, of which about 7.8 gigawatts have signed a power supply agreement and about 5.2 gigawatts are under construction. The management is expected to raise the profit growth rate guide from 5%-7%. The bank expects a compound annual growth rate of about 8% per share, which is higher than the agreed market expectation of about 7%.
The latest target price for Baker Hughes (BKR.US) is $71: The bank is optimistic about the increase in collaboration and after-sales service after Chart Industries' merger, and the EBITDA profit margin of the Industrial and Energy Technology (IET) business is expected to rise to about 25% in 2031.
Golar LNG (GLNG.US)'s latest target price is 67 US dollars, with a total return of about 38%, the highest of the top ten standards: the bank expects its current assets to achieve an operating rate of about 1.2 billion US dollars (about 260 million US dollars in 2025), and each additional MKII floating liquefied natural gas carrier will contribute about 400 million US dollars in EBITDA. The fourth ship is expected to sign a commercial contract in the near future. The ongoing strategic evaluation may include sale, which is part of the market An undervalued option.
Main line 3: There is still room for improvement in the refining sector, optimistic about niche market leaders
HF Sinclair (DINO.US) has surged 151% during the year, and the bank is still offering a 6-month target price of 142 US dollars, which corresponds to a total return of about 25%. The reason is that it is deeply involved in the Rocky Mountain and central mainland niche markets, the non-refining business is profitable, the return on free cash flow is expected to be about 11% and 6% in 2027/2028, and changes in the Small Refinery Exemption (SRE) rules have additional option value; the bank believes that the recent market has provided an entry window for concerns about the transition of CEO handover and the decline in refining gross profit.
Main line 4: The upper and middle reaches of natural gas are mistaken, the current entry point for high-quality products
TC Energy (TRP.US)'s latest target price of $71: The stock fell 9% in the past three months (the midstream index fell only 2% during the same period). The bank believes that the value of its US gas pipeline project and Ontario nuclear power assets is undervalued, the compound EBITDA growth rate may increase by about 6% in 2025-2032, and there is still room for capital expenditure of 6 billion to 11 billion Canadian dollars to be approved before 2030; the current stock price corresponds to 13 times the forward price-earnings ratio, which is about 16 times lower than that of its peers. The dividend ratio is approximately 4.5%.
Antero Resources (AR.US)'s latest target price of $46: The company plans to reduce cash costs from $2.70 per thousand cubic foot equivalent in 2025 to $2.00 by the end of 2028. The cancellation of high-cost transportation agreements can bring about $300 million in profit margin improvements, which are expected to expand to 600 million to 700 million US dollars in the next few years. The return on free cash flow of 14% is far higher than 9% of Appalachian peers, and is in discussions with power and data center customers for multi-year gas supply agreement.