


1&1 (XTRA:1U1) Dropped, So What Is Behind The Latest Attention?
1&1 (XTRA:1U1) has drawn fresh attention after a recent pullback, with the share price down about 4% over the past week and month, while the past 3 months remain positive.
That recent softness follows a mixed stretch for 1&1, with the 90 day share price return up 14.71% but the year to date share price return still down 7.63%, while total shareholder return over the past year of 15.26% hints at investors warming to the story despite near term volatility.
Scan how 1&1 compares with other potential breakouts by running your eye over our hand picked 179 high quality undervalued stocks that pair resilient balance sheets with quality cash flows.
Bulls point to 1&1’s recent 90 day rebound and value score, while bears highlight the longer term share price drag. Which side does the current valuation actually support?
Most Popular Narrative: 9% Undervalued
On the most followed view, 1&1 is worth about €25.28 a share, compared with the recent close at €23. That gap rests on a long list of moving parts, but one network shift in particular carries a lot of weight in the story.
Completion of customer migration onto 1&1's own network and continued 5G buildout is expected to substantially reduce dependence on costly national roaming agreements. This is projected to drive material long-term improvements in gross margin and EBITDA as more traffic is shifted onto owned infrastructure.
Ramp-down in extraordinary migration and network startup costs, combined with the cessation of upfront roaming payments as build-out progresses, is anticipated to free up cash flow and improve net income. This is seen as supporting a financial turnaround that the market may not fully appreciate in the current valuation.
See why 7 investors see 1&1 as 9% undervalued.
Result: Fair Value of €25.28 (UNDERVALUED)
Still, the 1&1 story can falter if OpenRAN rollout costs stay heavy or if ongoing roaming dependence keeps network expenses high and margins under pressure.
Find out about the key risks to this 1&1 narrative.
Another View: 1&1 Looks Expensive On Earnings
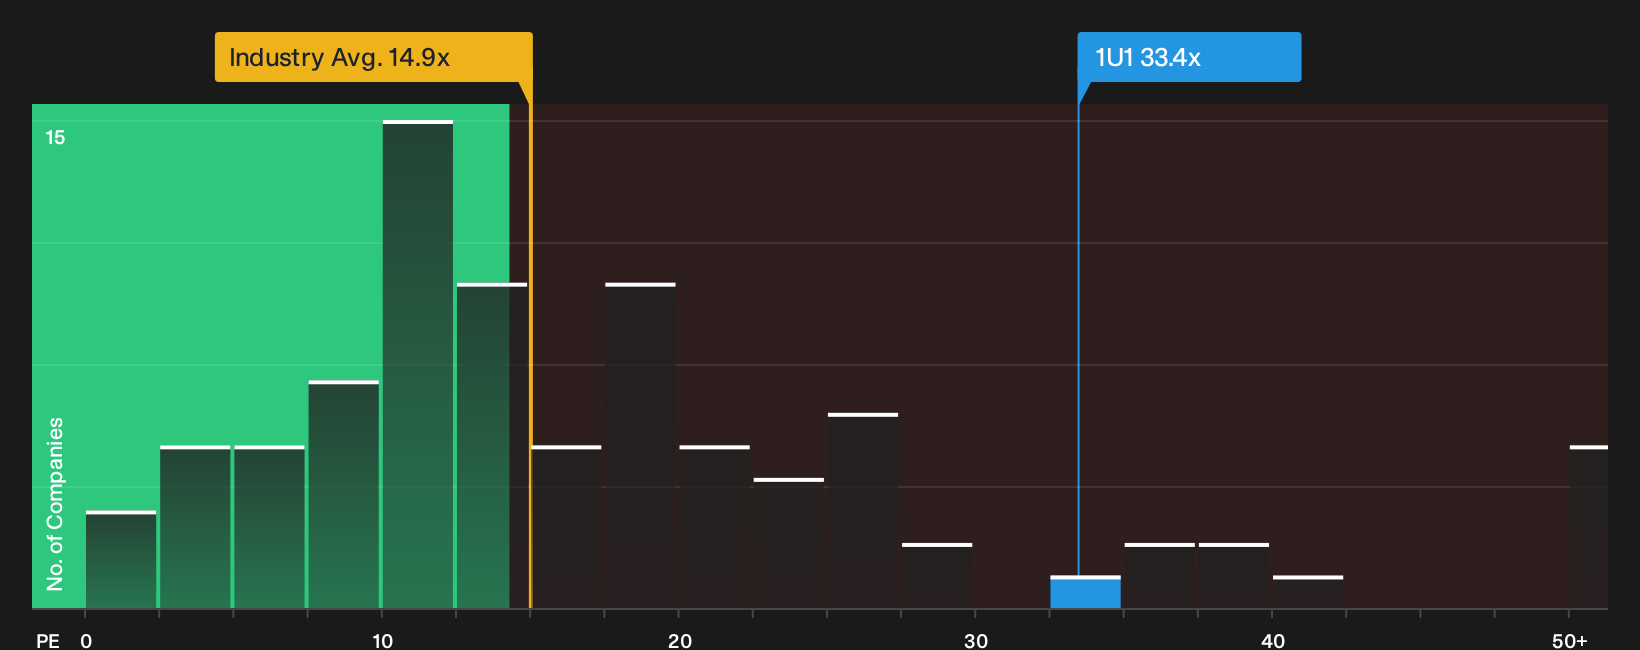
The earlier fair value story paints 1&1 as undervalued, yet the P/E picture points the other way. At 33.4x earnings, the stock trades well above both peers at 22.1x and the global wireless telecom average at 14.9x, and even above a fair ratio of 23.4x. That gap raises a simple question: Is the market already paying up for a recovery that has not yet shown through in profit trends?
For a closer look at how this earnings based view stacks up against other ways to price 1&1, it is worth digging into the full valuation breakdown and its moving parts, then weighing whether the current premium still feels comfortable for your risk tolerance. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or quiet opportunity? If you want to move fast rather than follow the crowd, stress test the upside case for yourself by reviewing the 2 key rewards.
Looking for more investment ideas beyond 1&1?
If you want to keep your edge, do not stop with 1&1. Use the Simply Wall Street Screener to hunt for stronger balance sheets, quieter compounders, and income ideas that suit your risk profile.
- Target resilient compounding by scanning a list of solid balance sheet and fundamentals (206 results) that can help you sidestep fragile businesses before the next bout of volatility.
- Spot potential mispricings early by filtering through a 619 high quality undiscovered gems before the crowd starts paying attention.
- Build cash flow into your plan by reviewing a 224 dividend fortresses that can help anchor returns when price moves feel unpredictable.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com