


Did Abbott Laboratories' Fall Catch You Out? What Investors Missed
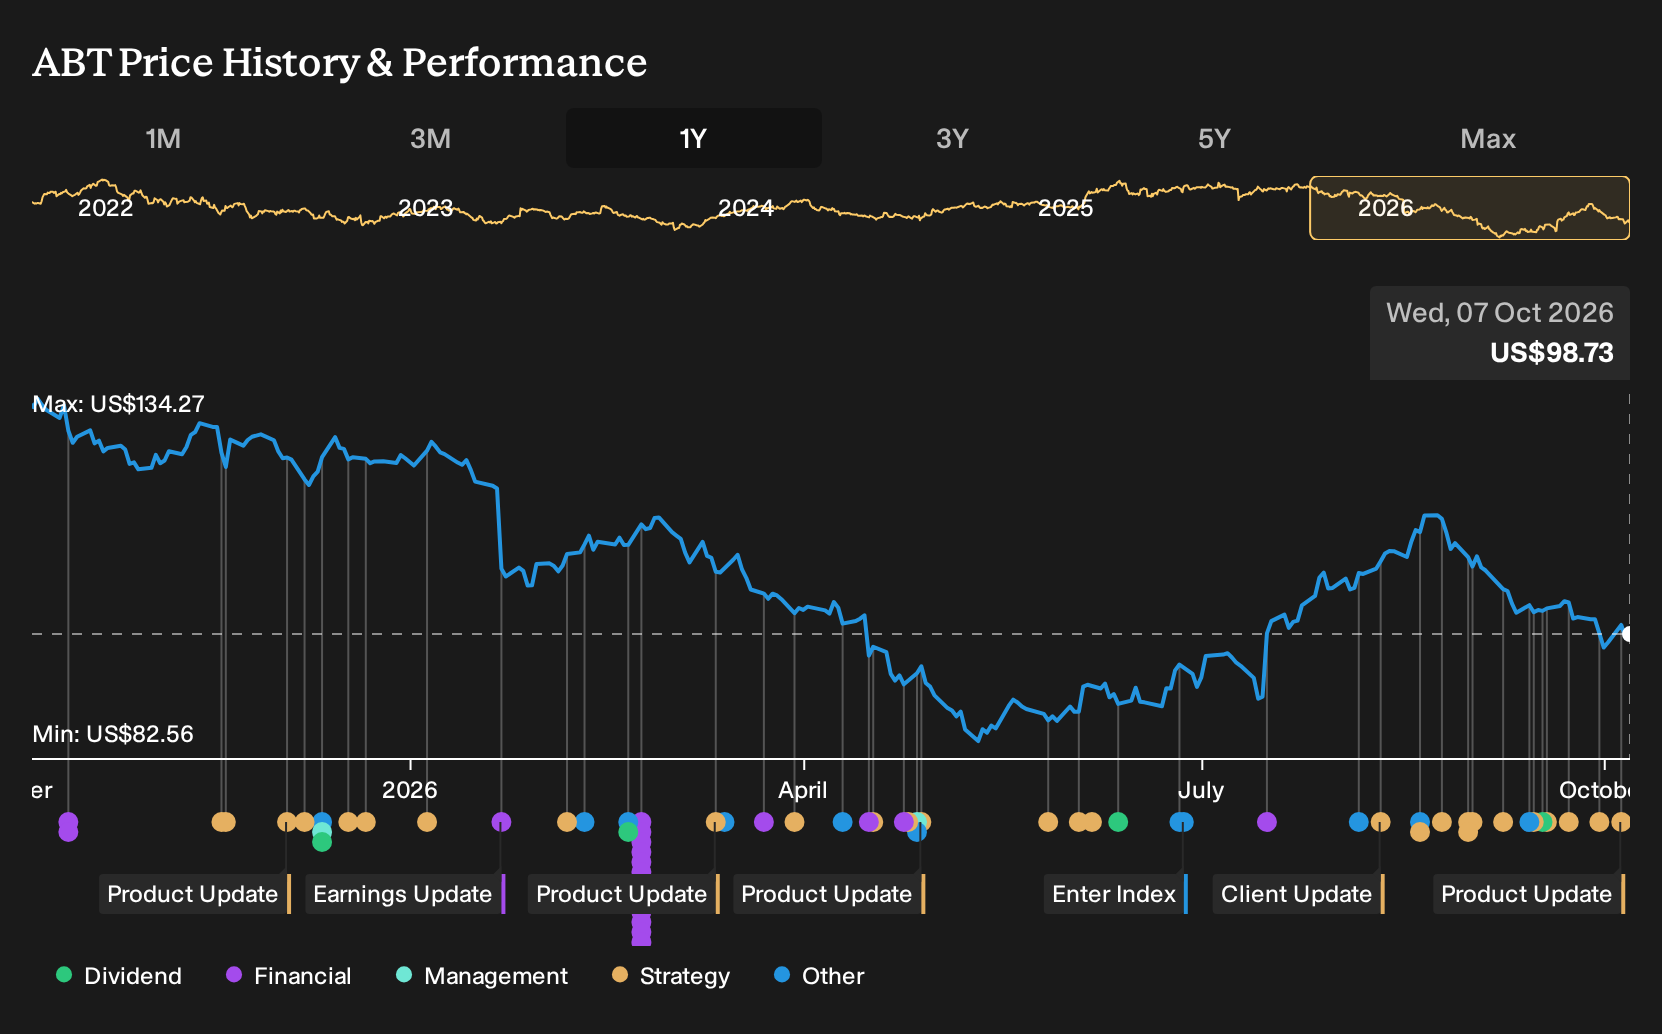
If you only glanced at Abbott Laboratories’ headlines this year, the story looked constructive. Product launches, major diagnostics deals and raised guidance all suggested a business pushing ahead. For Abbott Laboratories shareholders, the loss over the past year was 24.8%, including dividends. If you had been weighing an entry on 7 October 2025, how much of that eventual drawdown was hinted at by the earnings mix, margins and acquisition plans already on the table?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
This theme extends beyond Abbott Laboratories. See which of 35 healthcare AI stocks may still merit a closer look.
The Two Stories Abbott Investors Were Choosing Between
The shares cost US$133 at the start of the period, and Abbott Laboratories sat between two competing stories about what that price already assumed.
The optimistic case pinned Fair Value at US$142. It leaned on stronger demand from emerging markets and aging populations, and on Abbott Laboratories using its diversified mix in devices, diagnostics, nutrition and branded generics to support steadier earnings.
The sceptical view put Fair Value closer to US$114. That scenario used a 6.6% revenue growth assumption with a 13.9% profit margin and a future P/E of 34.4x, while stressing premium valuation risk and pressure on key products like FreeStyle Libre.
What The Results Changed In The Abbott Laboratories Debate
Exact Sciences was the big swing factor for Abbott Laboratories, with a more than US$20b oncology deal that fit the optimistic push into higher value diagnostics but brought clear earnings dilution that aligned with the cautious view on premium risk. Q2 2026 underlined that tension. Revenue reached US$12,593m but net income dropped to US$928m and net margin fell to 7.4% from 16.0%, so profitability support for the bull case stayed unproven. Overall the evidence cut both ways.
The lesson is simple. When a thesis leans on margin strength, do not stop at sales growth. Track net income and net margin after big acquisitions and compare those figures to the original assumptions before trusting the story.
What Abbott Laboratories' Lower Price Now Asks You To Believe
Abbott Laboratories now trades at US$98.73, and the selected Narrative places its Fair Value above that level. The gap reflects a belief that the current quote does not fully credit the earnings power of devices and diagnostics.
To align with that higher figure, a buyer today would need confidence that Abbott Laboratories converts its medical technology pipeline into durable sales growth and stronger margins while keeping Nutrition related legal costs contained.
"Key Takeaways: Analysts expect Abbott Laboratories to keep using demand from emerging markets, aging populations and new products to support diversified growth and earnings power that are not yet fully reflected in the current share price. The main thing that has to go right is that Abbott Laboratories continues to convert its medical technology pipeline in areas like continuous glucose monitoring, electrophysiology and cancer diagnostics into sustained sales growth and margin expansion, while managing Nutrition legal and regulatory risks."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking Past Abbott To The System
Abbott gives you products and diagnostics. Something else quietly shapes how those tools actually get used and paid for.
The pressure point is healthcare costs that keep running hotter than plans expected. Insurers are steering members into care programs that try to manage complex patients earlier.
One large operator is backing value based care models and heavy use of technology. It is testing home health visits, tighter care transitions and digital tools that aim to cut avoidable hospital time.
That kind of infrastructure does not replace Abbott's devices. It could change which treatments gain traction and which budgets stay under strain.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 28% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com