


3 US Bank Stocks Worth Watching As Sticky Inflation Keeps Rates Higher
Fed officials are openly worrying that AI spending, firm energy prices, and still‑easy financial conditions could keep inflation sticky and policy tight for longer. That mix can rattle broad indices, yet it can also shift money toward a different set of potential winners. This piece unpacks that tension and walks through three large US fixed‑income and Treasury intermediaries that sit squarely in the path of this latest policy shock.
The stocks highlighted below are just a first sample from this theme, and the full screen on Simply Wall St surfaced 9 more large US fixed income intermediaries with similarly detailed stories that are not covered in this article. To identify and analyze which of these Treasury focused plays best fit your own thesis, head straight into the US Large-Cap Fixed-Income & Treasury Market Intermediaries screener.
Prosperity Bancshares (PB)
Prosperity Bancshares gives you exposure to a large regional lender whose core business is traditional banking, with only a side connection to the fixed income theme through its securities book and treasury services rather than full scale bond trading or primary dealer activity.
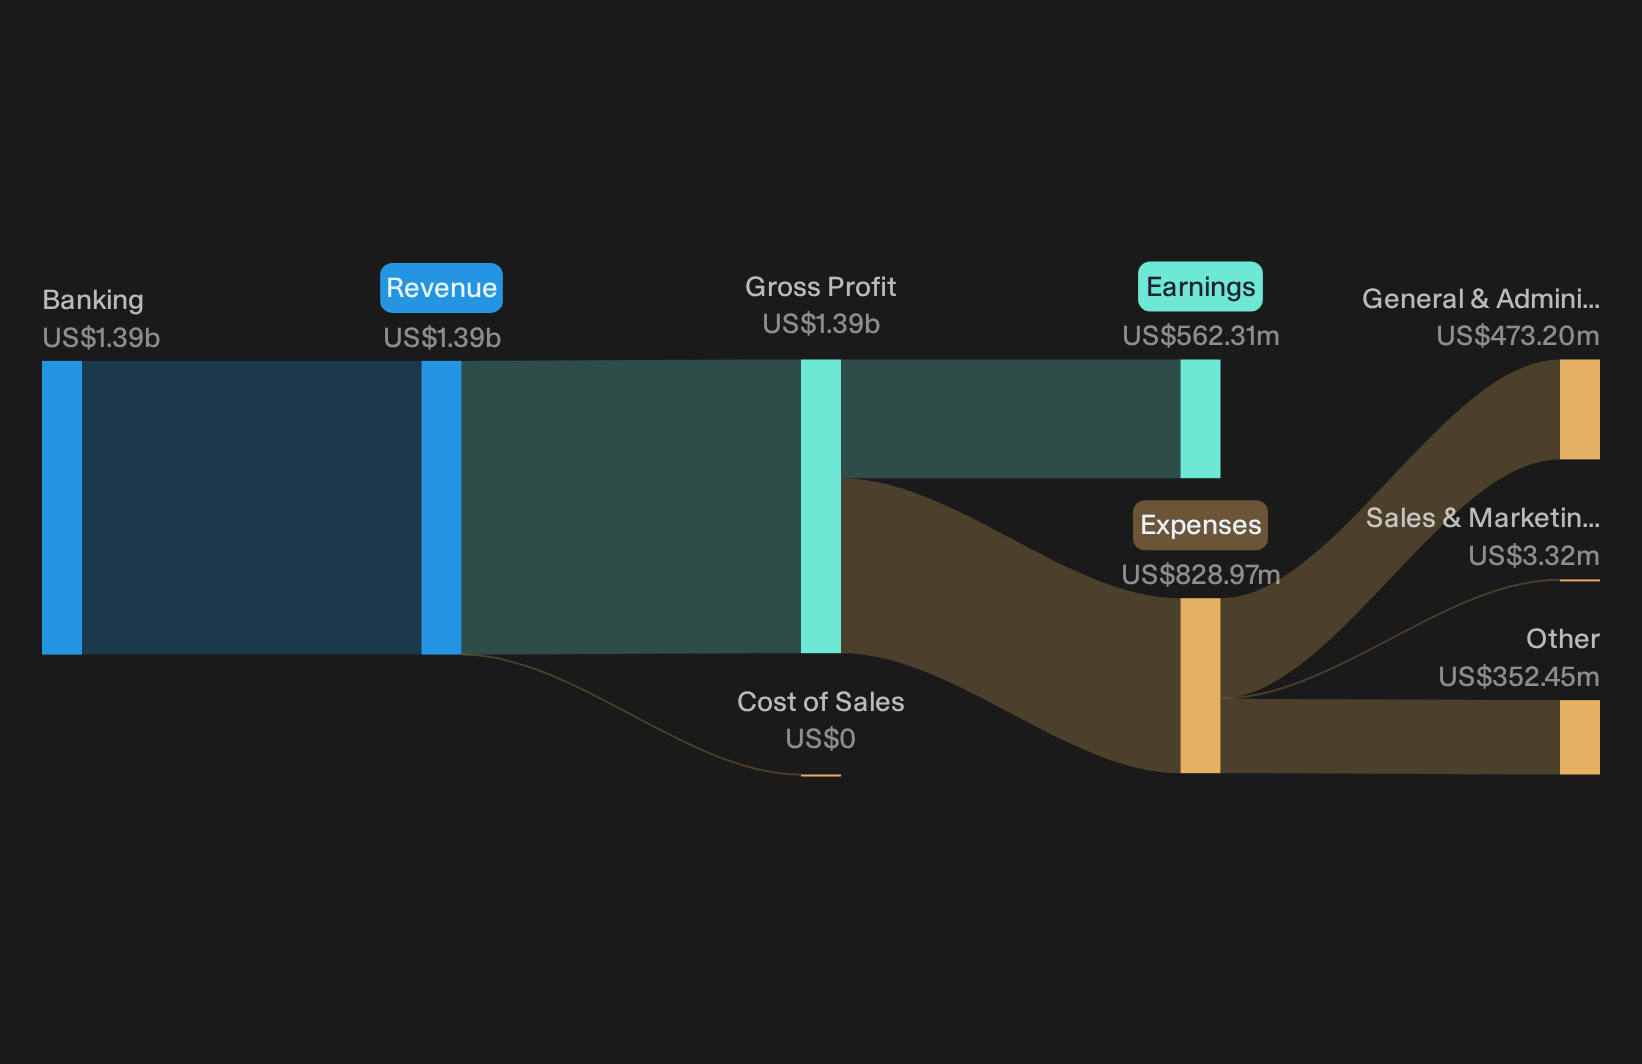
Prosperity Bancshares is a Houston based bank holding company offering deposits, loans, digital banking and treasury services, generating about US$1.4b of banking revenue in the US and carrying a market value of roughly US$8.1b.
"Completion of the American Bank, Texas Partners and Stellar transactions positions Prosperity Bancshares to consolidate a larger Texas and Oklahoma footprint, with management pointing to about US$100 to US$110 million of annual pretax cost savings that would directly support a lower efficiency ratio and higher net earnings power once integration is complete."
What happens to Prosperity Bancshares' earnings profile if one key cost and margin assumption buried in that integration story shifts even slightly?
Those small shifts can quickly reshape the risk reward trade off. Read the full narrative for Prosperity Bancshares to see how Prosperity Bancshares' integration story could accelerate or stall.
Pinnacle Financial Partners (PNFP)
Pinnacle Financial Partners plugs into this fixed income themed screen through its treasury management, deposit rich banking model and balance sheet lending. This gives you a regional lender that lives with rate volatility rather than a pure play trading desk.
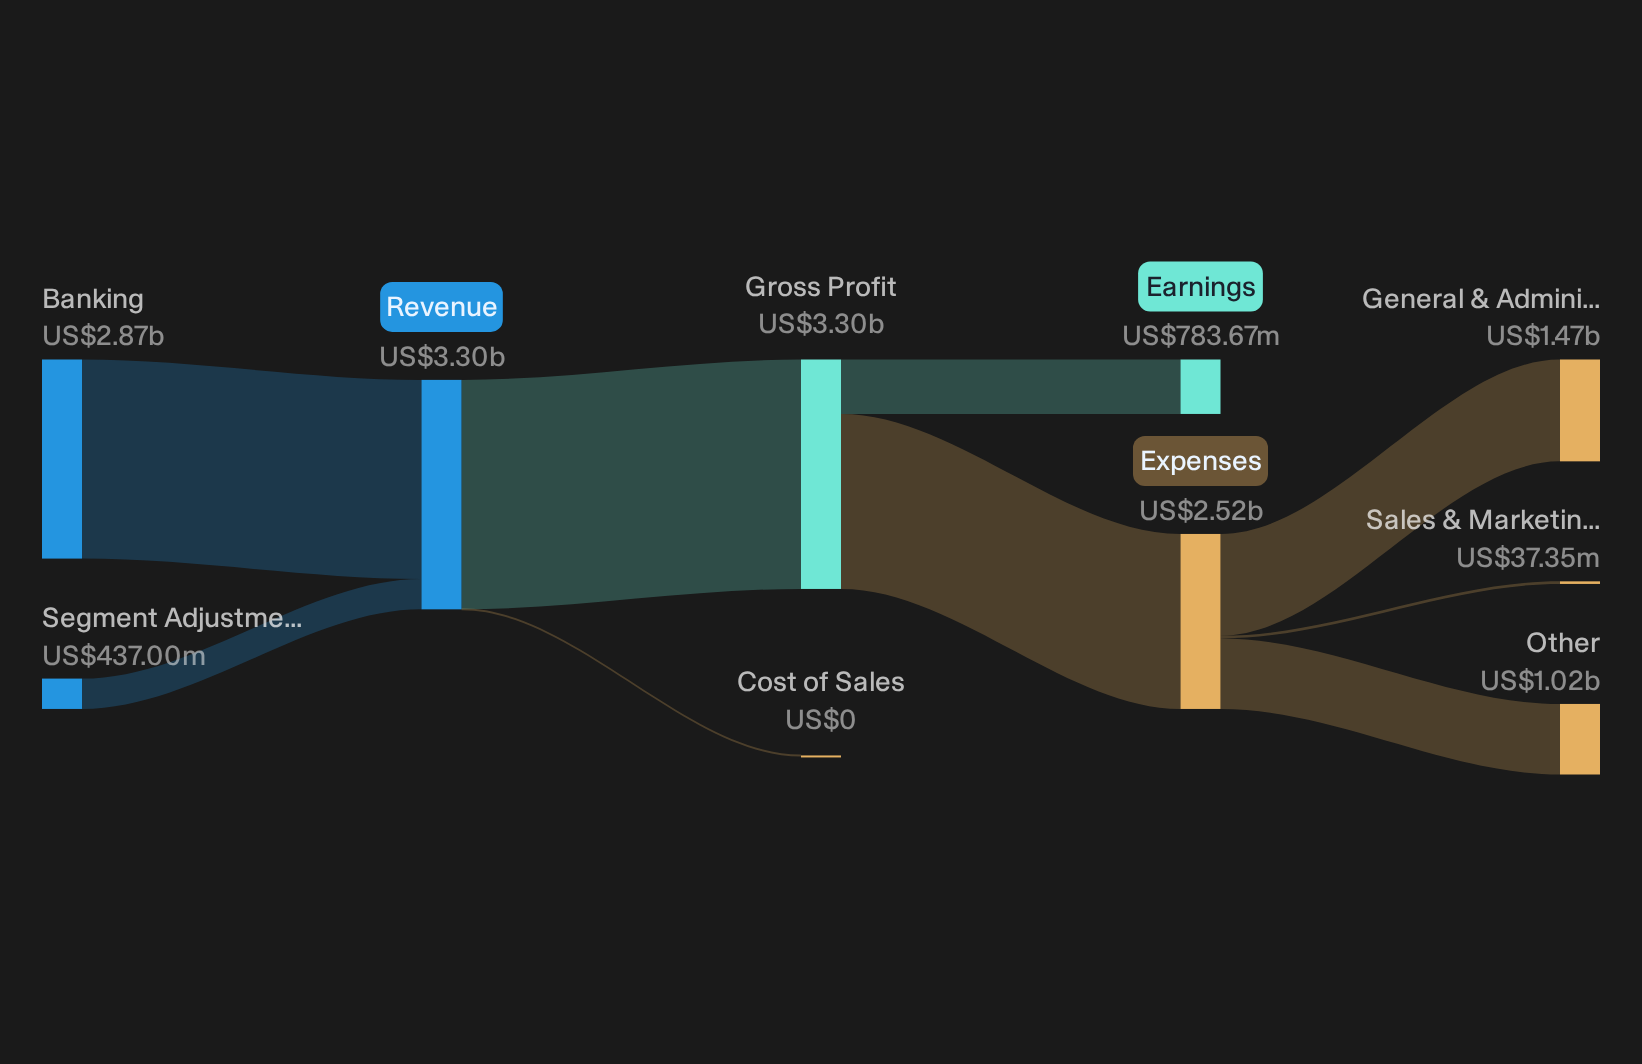
Pinnacle Financial Partners runs a broad banking, lending, treasury and wealth platform in the US, generating about US$2.9b of banking revenue plus a US$437 million segment adjustment. All US$3.3b is earned domestically and supported by an equity value of roughly US$14.5b.
Pinnacle Financial Partners brings that rate sensitive profile into focus through a franchise built on relationship banking, fee based services and a balance sheet that feeds off deposits and cash like products. This is why the next step in its story matters so much.
"Integration of Synovus, with revenue synergies of about US$10 million delivered year-to-date 2026 toward a US$20 million full-year target and a longer-term goal of US$100 million to US$130 million, is set up to add new product capabilities and geographies that feed into revenue and earnings."
What investors really have to weigh now is how one unseen pressure on funding costs and margin guidance shapes where those earnings ultimately land.
Those funding crosscurrents are exactly why the full narrative for Pinnacle Financial Partners digs into whether Pinnacle Financial Partners’ rate exposure is quietly masking earnings torque or capping the next leg of returns.
Banc of California (BANC)
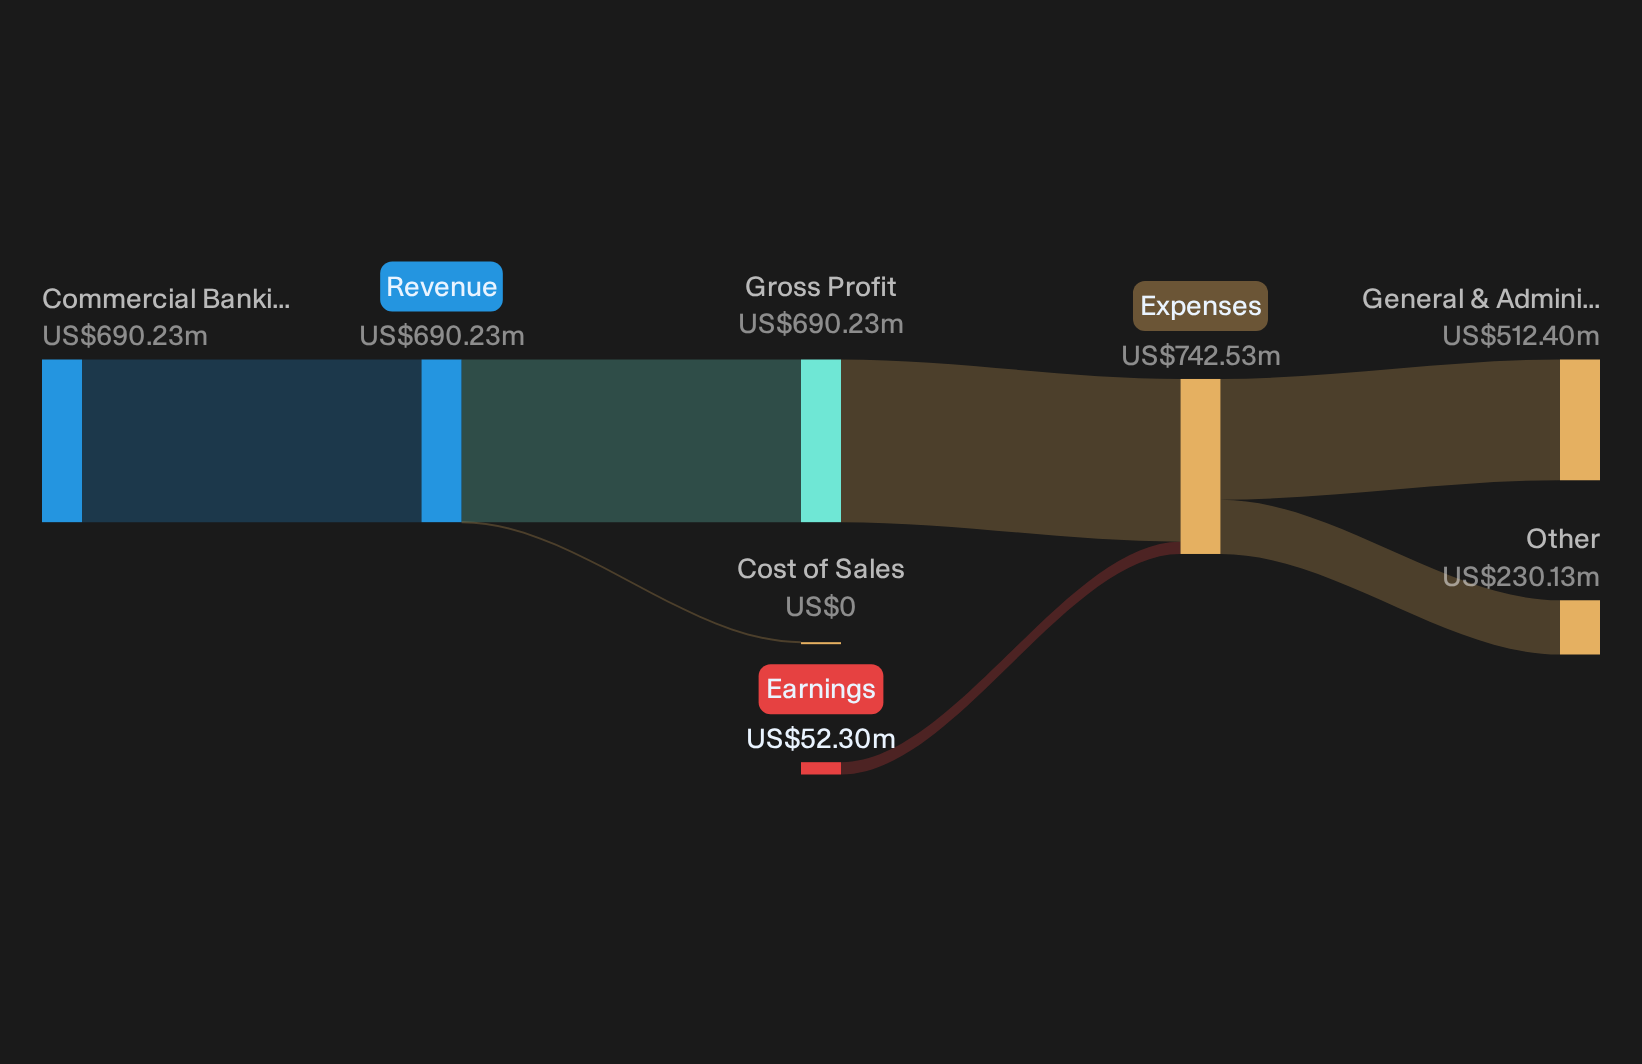
Banc of California supports this fixed income themed screen through its treasury management and corporate cash services, while its commercial banking engine keeps the real money flowing. The business generates about US$690 million from commercial banking in the US and carries a market value near US$2.8b.
"Heavy reliance on Southern California commercial real estate and construction loans exposes Banc of California to region-specific economic downturns and sector volatility, which could negatively impact asset quality, drive up loan losses, and suppress net earnings over the long term."
What shapes the opportunity now is how one less visible pressure on Banc of California’s funding mix and pricing power ultimately plays out.
That is where the story could pivot. Read the full narrative for Banc of California to see whether Banc of California’s funding pressures are masking upside or quietly stalling it.
Seeking Alternatives Before The Crowd?
Fresh themes can move from quiet to flying under the radar in a hurry. Scan for potential breakouts before the crowd so your watchlist is ready. Get in early.
- Spot potential cash rich bargains early by scanning the 29 high quality undervalued stocks while it still focuses on businesses the wider market has not fully caught yet.
- Ride the structural shift toward digital finance by screening 20 cryptocurrency and blockchain stocks while it remains under the radar for now and sentiment keeps dropping in and out of favor.
- Track possible compounding machines with strong footing by reviewing the list of solid balance sheet and fundamentals (25 results) before momentum screens start pulling those same tickers higher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com