


Visa Earnings Preview: What to Expect
Visa Inc. (V) is a global digital payments network headquartered in San Francisco, California. With a market capitalization of approximately $659.7 billion, Visa facilitates secure electronic payments, money transfers and payment services while providing fraud prevention, data analytics and innovative payment technologies to support global commerce and financial inclusion.
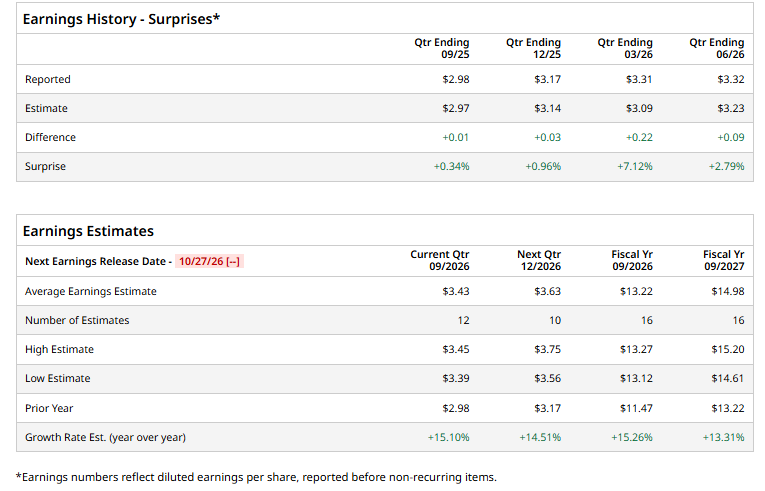
V is set to report its Q4 earnings soon. Ahead of the release, analysts expect the company to report diluted EPS of $3.43, up 15.1% from $2.98 in the year-ago quarter. V has exceeded Wall Street’s EPS estimates in each of the last four quarters, which is impressive.
For fiscal 2026, analysts expect the company to report EPS of $13.22, reflecting a 15.3% increase from $11.47 in fiscal 2025. V’s EPS is projected to increase another 13.3% year over year to $14.98 in fiscal 2027.
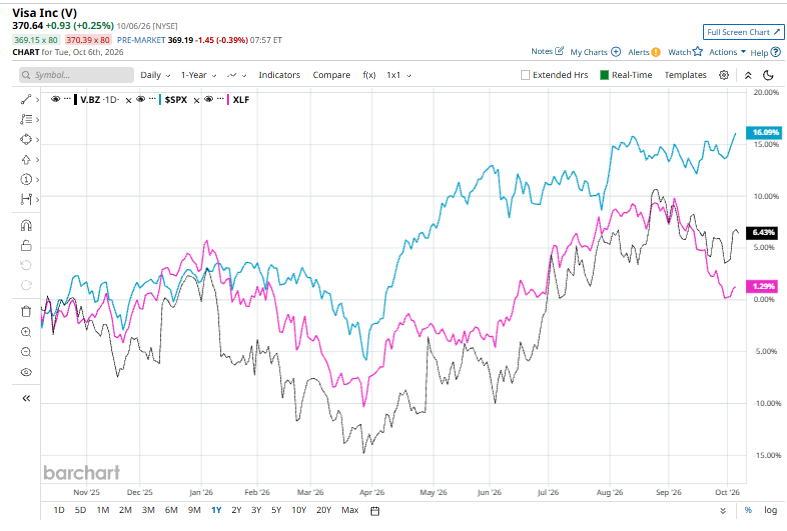
V stock has gained 6.1% over the past 52 weeks, underperforming the S&P 500 Index ($SPX), which returned 16%, while outperforming the State Street Financial Select Sector SPDR ETF (XLF), which posted a marginal gain over the same period.
Visa’s strong growth and profitability have supported its outperformance over the past year. Revenue has grown at a 14.5% annualized rate over the past five years, while share buybacks helped drive EPS growth of 18.8% annually, outpacing revenue growth. Meanwhile, Visa’s strong return on equity underscores its ability to generate highly profitable returns, further supporting investor confidence.
Analysts remain bullish on V, with the stock carrying a consensus “Strong Buy” rating. Of the 40 analysts covering the stock, 33 recommend a “Strong Buy,” four rate it a “Moderate Buy,” and three suggest a “Hold.” Meanwhile, the average analyst price target of $420.15 implies potential upside of 13.4% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.