


Adeia (ADEA) Names A New CEO And Renews Charter License, Is It Fully Priced?
Adeia (ADEA) has moved back into focus after two developments. Investors are weighing the impact of a new chief executive officer and a renewed multi-year IP license with Charter’s Spectrum businesses.
Recent trading tells a mixed story. Adeia’s share price has slipped over the past month and quarter, yet the year-to-date share price return of 39.93% and a 5-year total shareholder return of 443.40% show long-term holders have seen very large gains. This suggests sentiment is cooling in the short term as investors reassess growth potential and execution risk around the new CEO and the expanded Charter agreement.
Compare Adeia’s renewed Charter deal and leadership reset with peers by scanning our hand picked list of 19 high quality undiscovered gems that also lean on licensing and recurring revenue models.
Bulls see Adeia’s renewed Charter license and fresh leadership as underappreciated support for recurring cash flows. Bears point to modest revenue and profit growth. Which story does today’s valuation actually line up with?
Most Popular Narrative: 43% Undervalued
Adeia’s most followed valuation story pegs fair value at $43, above the last close of $24.60. That difference raises a clear question about what long term drivers could justify the gap.
Adeia is capitalizing on the ongoing proliferation of connected devices and the exponential surge in data generation, which is increasing the need for advanced digital content delivery, storage and high performance semiconductor technologies. These trends underpin expanding royalty streams, support sustainable top line revenue growth and reinforce long term earnings stability.
See why 8 investors see Adeia as 43% undervalued.
Result: Fair Value of $43 (UNDERVALUED)
Still, Adeia’s reliance on a concentrated set of large media and chip customers, combined with rising litigation costs, could quickly pressure both cash flow and the upbeat narrative.
Find out about the key risks to this Adeia narrative.
Another View: Adeia And The DCF Check
The most followed storyline has Adeia trading well below a $43 fair value based on analyst targets. Our DCF model is less generous. It puts future cash flow value around $24.24, which is close to the current $24.60 price and points to a much tighter margin of safety. Which lens do you trust more when real cash, not just earnings, drives returns?
To understand how that cash flow based estimate is built and what would need to change for it to move meaningfully higher or lower, take a look at the Look into how the SWS DCF model arrives at its fair value..
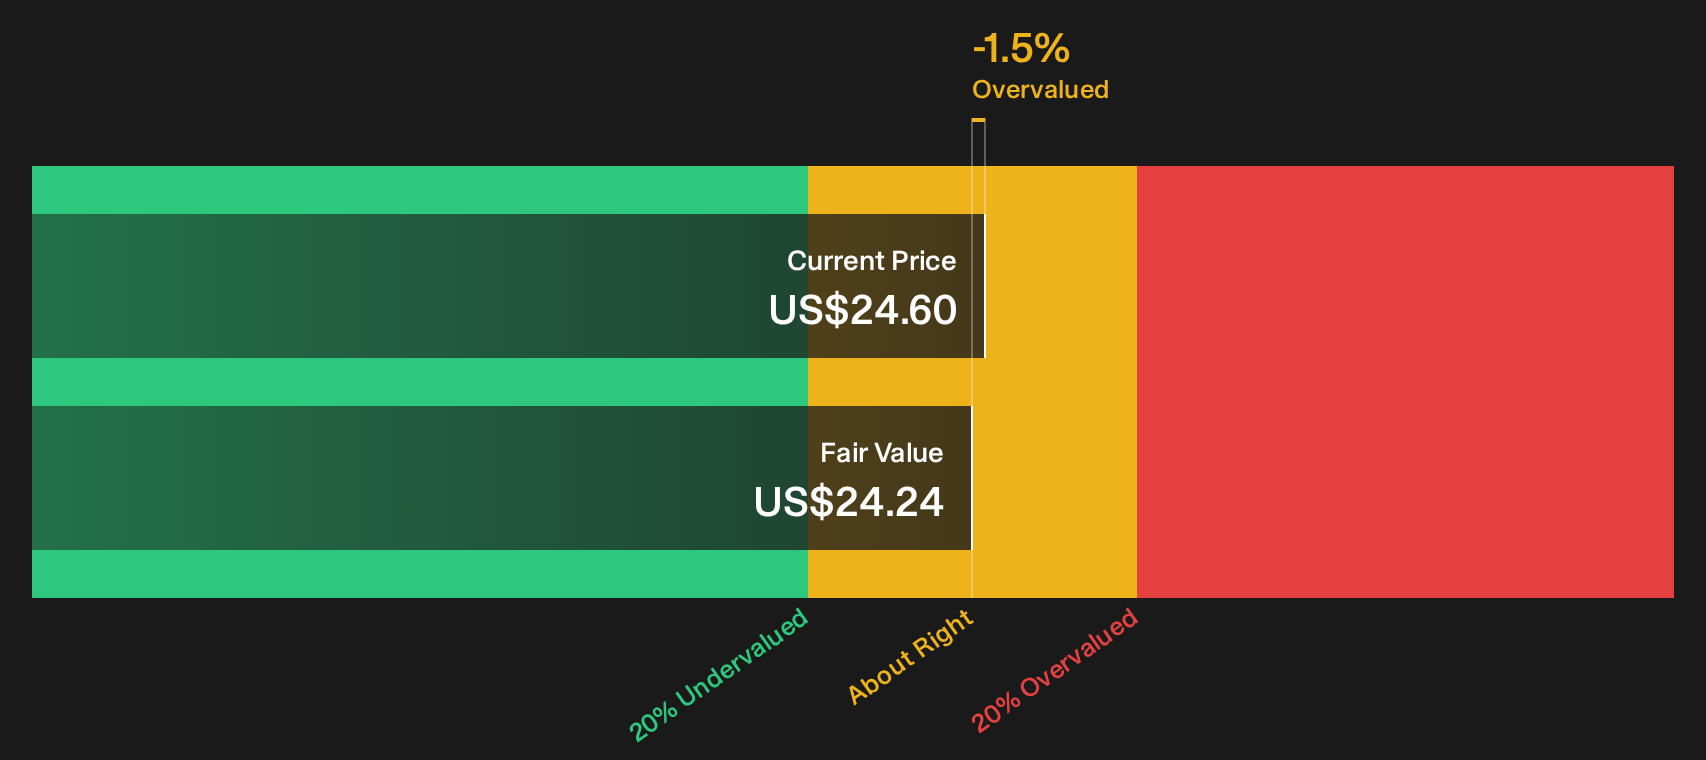
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Adeia for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages across Adeia’s narratives can make the picture feel murky. Review the key upside and downside signals now and build your own stance with the 4 key rewards and 2 important warning signs.
Looking for more Adeia style investment ideas?
If you only stop at Adeia, you risk missing other opportunities that fit your approach to risk, income and long term compounding potential.
- Target resilient potential by scanning a 31 resilient stocks with low risk scores that aims to prioritise stability when markets feel unpredictable.
- Chase fresh upside potential with a 19 high quality undiscovered gems that surfaces under the radar companies backed by solid fundamentals.
- Build a sturdier core for your portfolio through a list of solid balance sheet and fundamentals (25 results) that highlights businesses with stronger financial footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com