


Will Data Center Power Award Change Enerflex Stock Narrative
- Enerflex announced in October 2026 that it won a major Engineered Systems contract to supply about 450 megawatts of behind the meter natural gas power units for a North American data center developer, with deliveries scheduled between 2027 and 2028.
- The company is committing about $100 million of ES focused capital and infrastructure spending over 2026 and 2027, which could reshape its mix toward larger power projects and higher value life cycle services tied to data center energy demand.
- We will now look at how Enerflex's large data center power award might reshape its investment narrative and long term business mix.
Scan beyond Enerflex and this single contract by sizing up other power and infrastructure players in our hand picked 39 power grid technology and infrastructure stocks that are positioned to supply energy hungry data centers.
Enerflex Investment Narrative Recap
To own Enerflex, you need to believe the business can turn a large natural gas and infrastructure footprint into steadier, higher quality cash generation. The data center award supports that view by pointing ES work toward multi year, contracted power rather than one off gas projects. The key near term catalyst still sits in execution, converting backlog into projects that arrive roughly on time and on budget.
The biggest near term risk remains pressure on profitability in Engineered Systems, especially with profit margins recently at 2.1% compared with 5.5% a year earlier and leadership turnover still unresolved. The new contract does not remove those issues. It only gives Enerflex more volume to execute against cleanly or potentially stumble on.
The October 2026 announcement to invest about $100 million in ES facilities and power focused infrastructure is the clearest operational tie in to this data center award. Those commitments indicate that Enerflex is sizing its shop floors, tooling, and workforce around larger, power heavy orders rather than just traditional gas compression packages.
For catalysts, this capital plan matters because ES capacity and process efficiency will heavily influence whether backlog converts into healthier free cash flow or into more working capital tied up in projects. It also sharpens an existing risk. With 100% of liabilities funded through higher risk borrowing and a P/E of 57.7x versus a peer average of 18.7x, any execution slip on these investments could weigh quickly on returns.
Enerflex's narrative projects $3.1b in revenue and $270.0 million in earnings by 2029, based on analysts' assumptions. This implies 6.7% yearly revenue growth and an earnings increase of about 5x from $53.0 million today.
Uncover why Enerflex's fair value indicates a 31% potential upside to its current price, a gap that could narrow quickly if Enerflex executes cleanly on this contract.
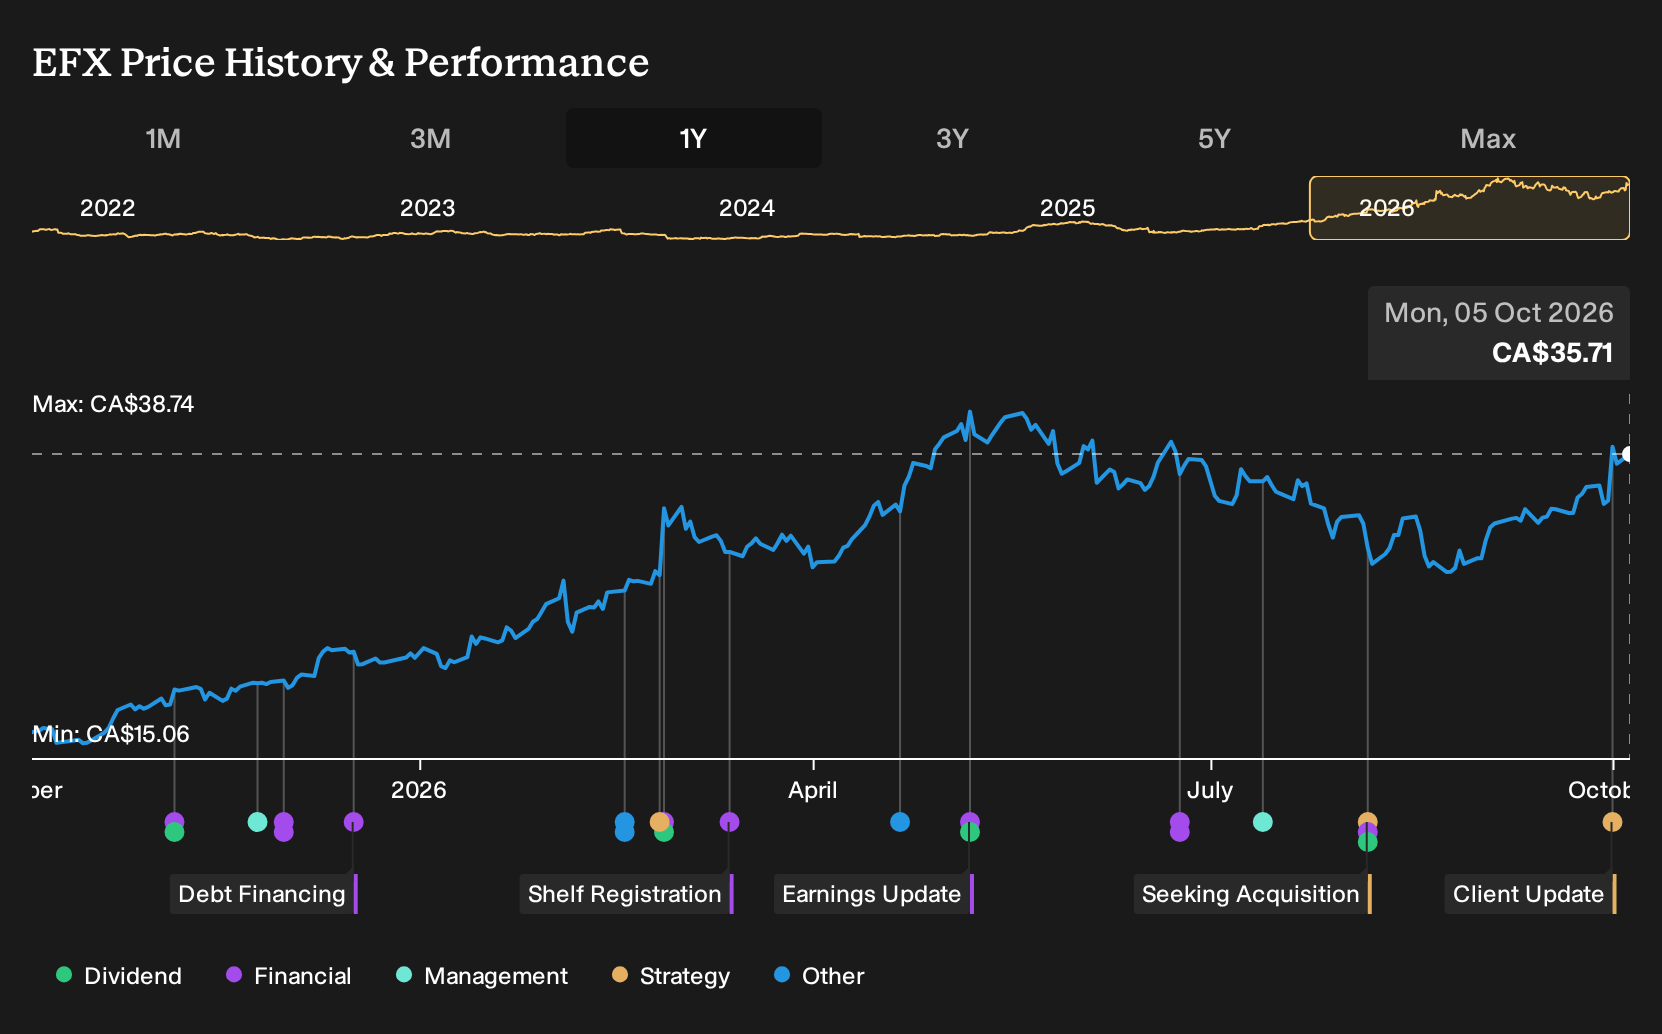
Exploring Other Perspectives
The lowest analysts on Enerflex focus on the risk that heavy data center and AI power exposure could backfire if project plans shift or timing slips. Before this power award, that group was pencilling in roughly flat revenue with earnings of $204.1 million by 2029. Their more cautious story might change. Yours can too, so explore both paths.
Explore 3 other Enerflex fair value estimates, including one that suggests it could be worth just CA$42.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Enerflex research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Enerflex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enerflex's overall financial health at a glance.
Looking for more investment ideas beyond Enerflex?
Once you have formed a view on Enerflex, it can help to compare that thesis with other opportunities that line up with your preferred balance of risk, income, and quality using the Simply Wall St Screener.
- If you want stability first, filter for companies with strong finances by starting with this list of solid balance sheet and fundamentals (7 results) that keeps the focus on resilient balance sheets and sound fundamentals.
- For investors hunting for misunderstood value, widen your search to a 9 high quality undiscovered gems that combine quality metrics with limited market attention.
- Those who care most about smoother rides can narrow the field quickly by using a 8 resilient stocks with low risk scores that tilts toward stocks with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com