


3 US Bank Stocks Riding High Money Market Rates
Bond yields near 5.25% on the 10 year Treasury, softer payrolls and shifting Federal Reserve expectations have turned cash and short duration investing into a real decision point rather than a parking bay. Higher risk free rates compete head on with equities, yet money market providers can also benefit when investors reshuffle idle cash. This article explains how three US Short Duration Cash and Money Market Product Providers are positioned in this new rate reality.
The three stocks highlighted below are a working sample from this theme. The full screen pulled out 31 more US Short Duration Cash and Money Market Product Providers with equally interesting cash flow stories that are not covered here. If you want to identify where your own risk tolerance and time horizon fit best, head straight into the US Short-Duration Cash and Money Market Product Providers screener to filter, analyze, and zero in on the highest conviction plays.
FirstSun Capital Bancorp (FSUN)
Overview: FirstSun Capital Bancorp is a regional US bank that provides commercial and consumer lending, deposits, and cash management services across several Western and Southwestern states.
Operations: FirstSun Capital Bancorp generates about US$356 million from Banking and US$88 million from Mortgage Operations, with roughly US$447 million of total revenue coming from the United States.
Market Cap: US$1.84b
FirstSun Capital Bancorp matters for this cash and money market theme because its business model leans heavily on operating deposits, sweep balances, and everyday cash management for small and mid sized clients who care where every idle dollar sits.
"FirstSun's robust deposit growth across both consumer and business segments, especially in high-growth Southwestern and newly entered California markets, is described by management as positioning the bank to benefit from urban migration trends and expanding local economies."
What happens to that earnings path depends heavily on how one unresolved pressure on credit quality and reserve levels ultimately plays out.
That unresolved pressure is the real hinge for the story, and the full narrative for FirstSun Capital Bancorp explains how credit risks, deposit momentum, and earnings could be moving in different directions.

Bank of N.T. Butterfield & Son (NTB)
Overview: Bank of N.T. Butterfield & Son runs community, commercial and private banking, managing deposits, loans and cash services for globally spread clients.
Operations: Bank of N.T. Butterfield & Son generates about US$625 million from Banking, mainly across Bermuda, Cayman, the Channel Islands and the UK.
Market Cap: US$2.31b
Bank of N.T. Butterfield & Son plugs straight into this cash and money market theme because its deposit base, wealth clients and offshore hubs all feed short duration balances that are sensitive to higher policy and money market rates.
"Advanced digital transformation initiatives and continued investment in technology are expected to drive ongoing operational efficiencies, cost containment, and improved client service, which in turn should support better cost-to-income ratios and enhanced earnings over time."
What happens when one less visible source of funding cost pressure collides with those efficiency gains will matter a lot for future profitability.
That funding squeeze is the real story accelerator, and the full narrative for Bank of N.T. Butterfield & Son lays out how Butterfield’s earnings profile could decouple from headline efficiency gains.

Isabella Bank (ISBA)
Overview: Isabella Bank Corporation is a Michigan community bank that combines traditional lending with deposit, wealth management, and cash management services.
Operations: Isabella Bank generates about US$83 million from Retail Banking Operations, all from customers based in the United States.
Market Cap: US$291 million
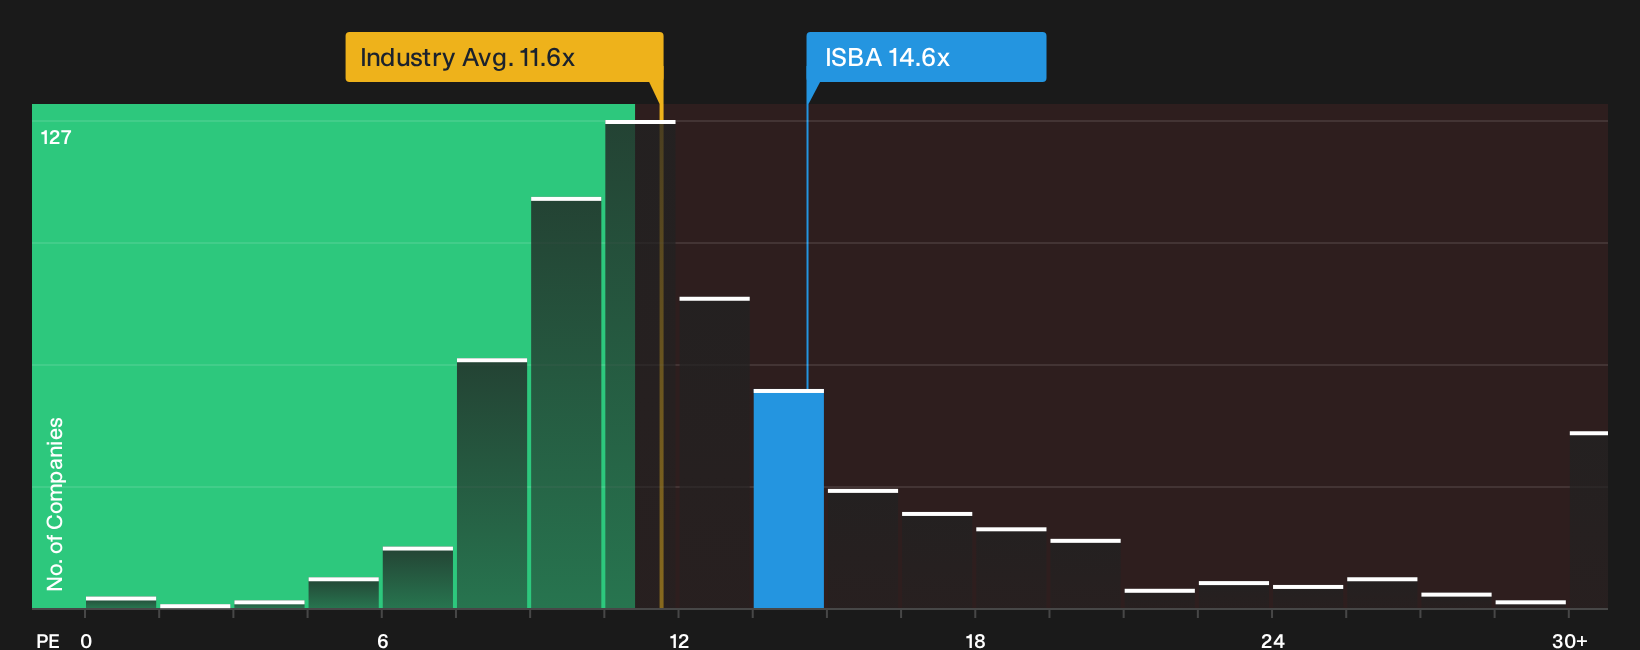
Isabella Bank fits this cash and short duration theme because it leans on checking, savings, and wealth accounts where rising short term rates can support net interest income and fee streams. Reported expectations of earnings growth above 20% and 24% profit margins suggest that this model has meaningful potential. However, how investors choose to view a 14.6x P/E in the context of an 8% ROE is presented as a key consideration for the overall investment narrative.
That valuation tension is exactly why the analyst forecasts for Isabella Bank could be worth a look for how Isabella Bank’s earnings profile might be evolving beneath the surface.
Seeking Alternatives Before Others Catch On
Fresh ideas can move fast. Breakout momentum often gets caught late, when prices are already moving significantly. Scan curated opportunities that may be under the radar for now and consider them before they become widely followed.
- Spot strong payouts that might hold up even when sentiment drops by reviewing the 7 dividend fortresses before the crowd starts focusing on yield.
- Track early movers in crypto related businesses while they are still building momentum using the curated 17 cryptocurrency and blockchain stocks before sentiment changes and pricing adjusts.
- Look for miners that may be positioned for metal demand cycles with the focused 36 elite gold producer stocks while pricing still reflects earlier expectations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com