


How Child Diabetes Screening Launch At Revvity (RVTY) Has Changed Its Investment Story
- Revvity launched the CE-IVDR-certified GSP T1D 3plex kit, an automated multiplex autoantibody assay that uses dried blood spots to support population-wide screening for type 1 diabetes risk in children, initially in European and other CE IVD-accepting markets.
- The kit extends Revvity’s diabetes portfolio into large-scale pediatric risk screening programs by bundling reagents, high-throughput GSP instrumentation and software into a single workflow that targets early detection before symptoms and diabetic ketoacidosis appear.
- We will now examine how Revvity's investment narrative could shift as its CE-IVDR GSP T1D 3plex kit targets national screening demand.
Scan beyond Revvity and see how other diagnostics players are positioning for large-scale screening demand with our hand picked 33 healthcare AI stocks.
Revvity Investment Narrative Recap
To own Revvity, you need to believe the clinical diagnostics and software mix can turn relatively modest revenue expansion into faster earnings growth and strong cash generation. The GSP T1D 3plex launch fits that story because it leans on existing GSP hardware and installed newborn screening relationships rather than requiring Revvity to build a new channel from scratch.
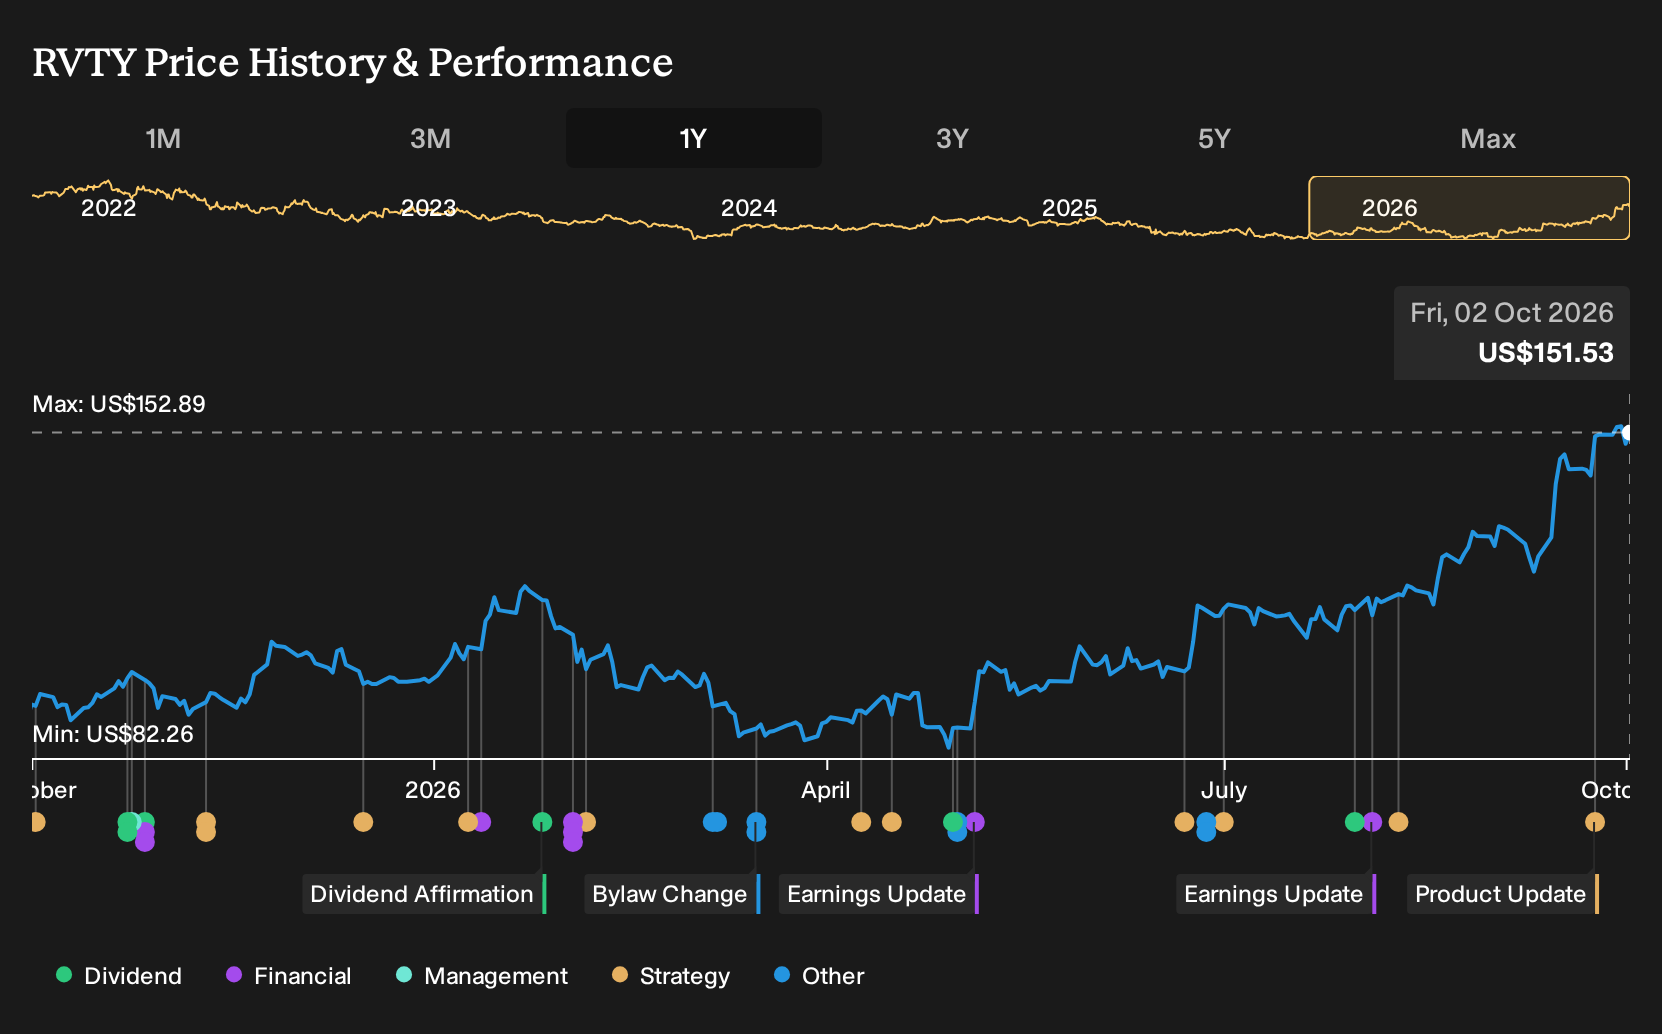
In the near term, the key swing factor is whether reproductive health and ex China immunodiagnostics, including T1D products, keep supporting 4% to 5% organic growth with upper 20s operating margins. The main risk is that expectations for high earnings growth and a 71.2x P/E collide with slower reported progress or further one off items.
The fresh T1D 3plex kit announcement plugs directly into one of the clearer operational catalysts analysts already flag. Stronger reproductive health and immunodiagnostics performance, supported by new prenatal and T1D screening products, is one area where the market may already be assuming faster and more durable revenue momentum from Revvity.
If national T1D screening programs adopt the CE IVDR workflow at scale, it could reinforce the idea that diagnostics and lab tools can carry organic growth while Signals software, AI enabled workflows and the China immunodiagnostics exit reshape margins. If uptake is slower or programs remain fragmented, this particular launch probably stays more incremental than transformational.
What The Current Analyst Set Up Implies For Revvity
Revvity's narrative projects $3.3b revenue and $539.9 million earnings by 2029. This assumes revenue growth of 4.3% a year and an earnings increase of about $302.5 million from $237.4 million today.
Uncover how Revvity's fair value indicates a 14% potential downside to its current price, suggesting a valuation premium that leaves little room for error.
Exploring Other Perspectives
You also have a very different story on Revvity if you focus on the bearish concern that earnings power never fully recovers. Those analysts were penciling in only $3.2b of revenue and about $352.2 million of earnings by 2029. That is far below consensus and shows how sharply opinions could shift as the T1D 3plex kit filters into future models.
Explore 2 other Revvity fair value estimates, including one that indicates as much as 14% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Revvity research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Revvity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Revvity's overall financial health at a glance.
Looking for more ideas beyond Revvity?
Once you have formed a view on Revvity, it can help to widen the lens and see how other businesses stack up on income potential, quality and risk. The Simply Wall St Screener gives you a structured way to do that without getting lost in hundreds of tickers.
- If you want income on top of potential capital returns, start by scanning companies that combine higher yields with resilience using our 7 dividend fortresses.
- If capital preservation sits high on your list, focus on businesses with steadier fundamentals and lower risk scores through the 31 resilient stocks with low risk scores.
- If you are hunting for under followed opportunities with solid numbers behind them, filter for stronger balance sheets and earnings quality across our 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com