


Edwards Lifesciences (EW) Could Be 16% Undervalued As AUTUS Approval Sharpens The Debate
FDA approval of AUTUS puts Edwards Lifesciences in focus
Edwards Lifesciences (EW) just received U.S. Food and Drug Administration approval for its AUTUS Size-Adjustable Valve, a pediatric pulmonary valve designed to expand as children grow, potentially limiting repeat open-heart surgeries.
The AUTUS approval comes at a mixed moment for Edwards Lifesciences, with the share price down 10.54% over the past 90 days and 5.28% over the last month, while the 1-year total shareholder return of 10.48% indicates that longer term investors have still seen gains.
Scan beyond Edwards Lifesciences and see how other healthcare specialists are positioned for breakthroughs with our curated list of 35 healthcare AI stocks.
The recent slide in Edwards Lifesciences despite AUTUS progress raises a sharp question: Are investors reassessing the business fundamentals or simply rotating sentiment at this price, which is where the valuation work starts?
Most Popular Narrative: 15.7% Undervalued
Edwards Lifesciences last closed at $85.15 against a widely followed fair value view of about $100.96, which puts the focus squarely on whether execution can match those expectations under a 7.51% discount rate.
The path to at least US$2b of TMTT revenue by 2030, supported by recent guidance of US$760 to US$780 million in 2026 TMTT sales, points to further mix shift into higher growth transcatheter therapies that could contribute to overall revenue and EPS expansion. The long term clinical durability data for SAPIEN and RESILIA valves, along with outcomes for EVOQUE and PASCAL, strengthens Edwards Lifesciences positioning with physicians and payers and may help sustain pricing and share, which can support both revenue and net margins.
See why 28 investors see Edwards Lifesciences as 16% undervalued.
Result: Fair Value of $100.96 (UNDERVALUED)
Still, the Edwards Lifesciences story can break if tariffs squeeze margins harder than expected or if the JenaValve injunction limits deal making and adds legal drag.
Find out about the key risks to this Edwards Lifesciences narrative.
Another View: Edwards Lifesciences Through The P/E Lens
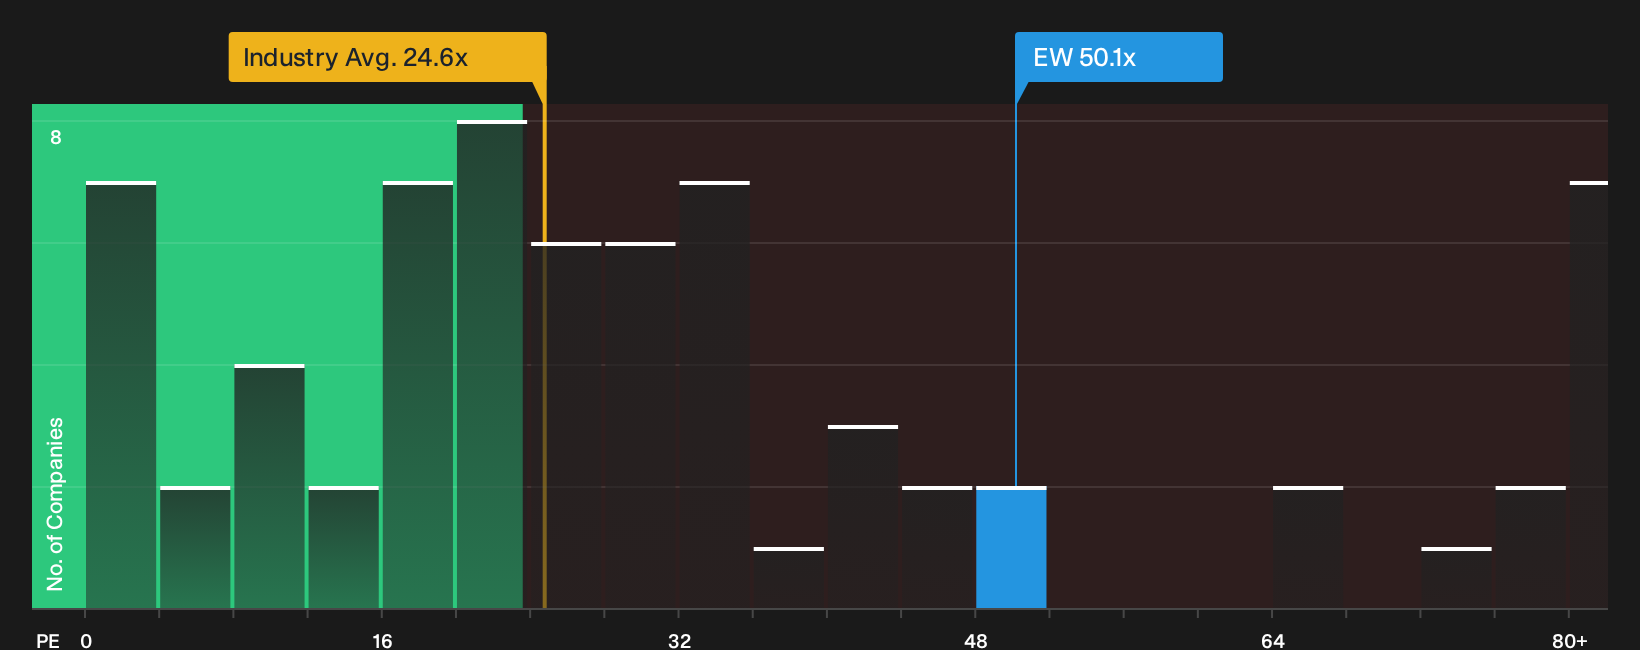
Edwards Lifesciences screens very differently once price is compared to current earnings. The stock trades on a P/E of 50.1x, almost double the US Medical Equipment industry on 24.6x and well above peers at 25.5x, while the fair ratio sits lower again at 32.8x.
That kind of gap means investors today are paying a hefty premium that could compress if sentiment or forecasts cool. The open question is whether the growth and margins you expect truly justify staying that far above the P/E level the market could move towards.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early opportunity, you will only know where you stand on Edwards Lifesciences once you have reviewed both sides of the ledger and moved fast enough to keep your view current, starting with the 2 key rewards and 2 important warning signs.
Hunting for more Edwards Lifesciences style ideas?
Once you have formed a view on Edwards Lifesciences, broaden your watchlist with focused screens that surface specific types of opportunities other investors may be overlooking.
- Target potential mispricings by scanning a curated pool of quality companies that currently look out of favor through the 31 high quality undervalued stocks.
- Strengthen your income stream by reviewing a hand picked set of higher yielding payers via the 7 dividend fortresses.
- Dial down volatility risk by filtering for sturdier businesses using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com