


Realty Income Stock And 2 Large Cap Dividend Plays For Rising Rates
A fresh rate hike cycle often feels like a storm rolling in, and plenty of investors head for shelter just as opportunity appears. With the Federal Reserve tightening and the S&P 500 historically prone to short-term pullbacks, quality dividend stocks can become the steady cash engines others rush past. This article examines three large-cap dividend payers affected by the latest Fed move and explains how their setups might appeal to patient income seekers.
The stocks highlighted below are just a starter pack, and the full screen pulled up 29 more large-cap dividend payers with equally compelling income stories that are not covered here.
To sort through the full field, analyze payout strength, and identify your own highest-conviction income plays, head straight to the High-Quality Dividend-Paying Large-Cap Stocks screener.
Gaming and Leisure Properties (GLPI)
Gaming and Leisure Properties fits this dividend screener as a large US REIT built around long leases with tenants covering most property costs. This structure can appeal to income investors looking for steadier cash flows while the new Fed rate cycle plays out.
Gaming and Leisure Properties acquires and owns US gaming real estate that it leases on triple net terms. It generates about US$1.7b from investments in real estate and carries a market value of roughly US$11.3b.
"The ongoing development and deployment of committed capital into projects such as Bally’s Chicago, Penn’s Aurora, Bally’s Lincoln and Live! Virginia is now backed by about US$1.8b of future funding expected to be deployed by year end 2027. Significant financial exposure to Bally's, a tenant with a downgraded credit profile and ongoing cash flow and leverage concerns, remains a concentration risk for Gaming and Leisure Properties."
Any change, even a small one, in a single tenant relationship could materially influence future income and investor confidence.
That concentration risk is only part of the picture, and the full narrative for Gaming and Leisure Properties shows how Gaming and Leisure Properties could still convert this exposure into accelerating dividend resilience.

Realty Income (O)
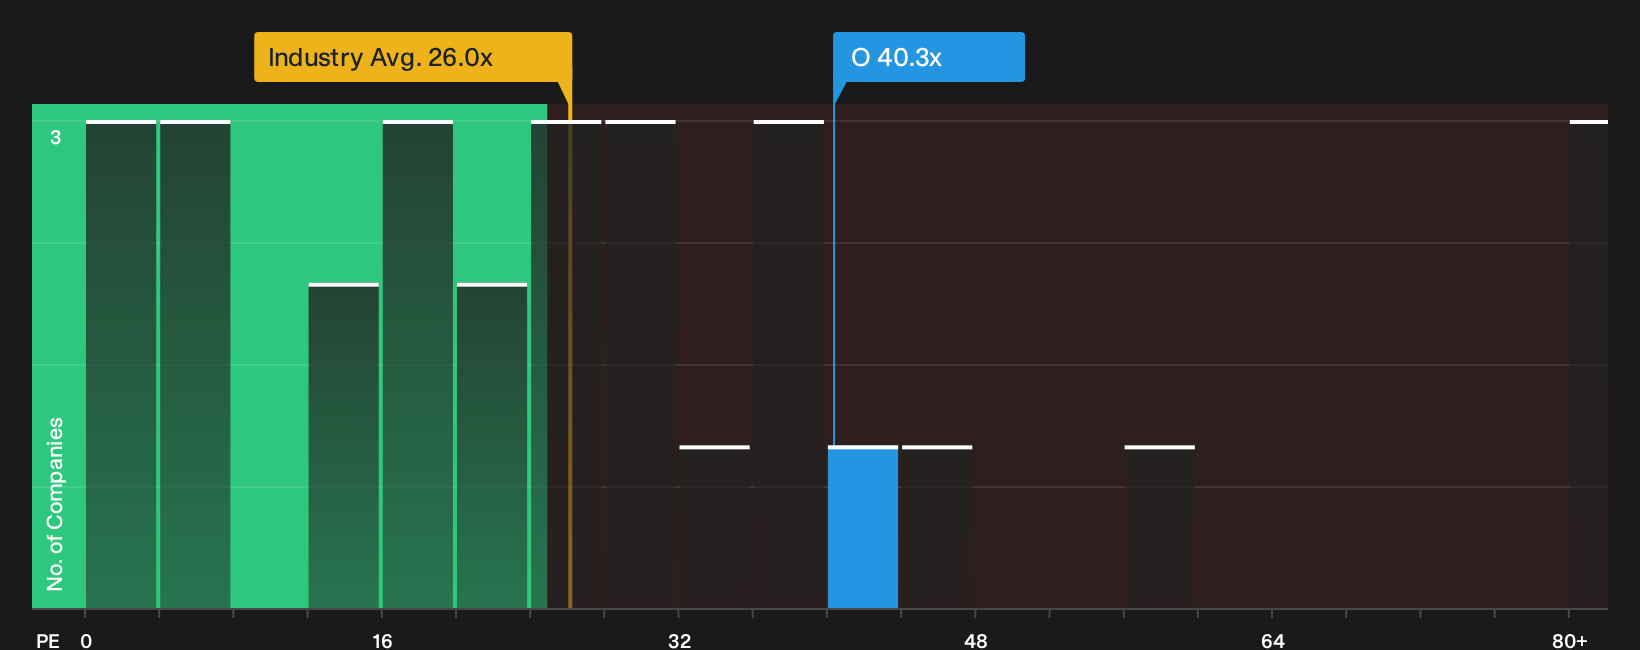
Realty Income fits the high-quality dividend screen as a large net lease REIT that rents essential real estate on long contracts, earning about US$6.1b from leasing to clients and backed by a roughly US$51.2b market value.
For income investors searching this screener for staying power rather than drama, Realty Income offers a textbook example of what long leases and disciplined payouts can look like when markets wobble around Fed moves.
"Realty Income is the standard in REITs. Having paid a monthly dividend over 32 years uninterrupted (starting at 1994), every investor that wants to have a secure and reliable source of dividend income has a position or had some kind of investment in this company over time."
What matters next is how one quiet pressure on its funding costs shapes the gap between dependable income and actual total returns.
That funding squeeze is exactly what the full narrative for Realty Income unpacks, showing where Realty Income's monthly checks could be masking accelerating strengths and overlooked risks.
Prologis (PLD)
Prologis slots naturally into this high-quality dividend screener because its logistics warehouses and infrastructure tilt toward rental income that often holds up when rate hikes unsettle equities. The scale involved makes its cash flows and balance sheet especially relevant for income-focused investors.
Prologis is a global logistics and industrial REIT that develops and leases warehouses and related infrastructure. It generates most of its revenue from U.S. real estate operations of about US$8.0b, alongside smaller Asia, Europe and other Americas property and strategic capital fees, and carries a market value near US$125b.
"A record 67 million square feet of leases signed in Q2 2026, higher occupancy at 95.5%, and raised full year occupancy and same store NOI guidance suggest that prior pent up demand in the leasing pipeline is beginning to convert into contracted rent. Continued reliance on share issuance to support growth could dilute existing shareholders and weigh on earnings per share growth even if revenue expands."
The real test for Prologis now is how that tension between expanding leased space and the way it funds growth ultimately shapes dividend headroom.
That growth versus funding trade off is exactly what the full narrative for Prologis unpacks, highlighting where Prologis could convert expanding warehouses into accelerating dividend flexibility.

Curious About Fresh Dividend Alternatives
Markets move fast and the best breakout income stories rarely stay under the radar for long. Scan fresh momentum, spot yields before the crowd, and act now.
- Spot income opportunities investors keep missing by running the 7 dividend fortresses while yields, payout ratios, and balance sheets still line up in your favor.
- Track resilient cash generators that hold up when momentum swings by filtering through the 31 resilient stocks with low risk scores before the best setups get fully priced in.
- Hunt for potential multi-year compounding stories hiding in plain sight with the curated list of solid balance sheet and fundamentals (25 results) while these fundamentals are still being overlooked.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com