


Undervalued Asian Small Caps With Insider Action For October 2026
As Asian markets navigate a complex landscape of fluctuating oil prices and persistent inflation, small-cap stocks have garnered attention for their potential resilience amid broader economic uncertainties. In this environment, identifying promising small caps involves looking at companies with strong fundamentals and insider activity that may signal confidence in their future prospects.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Security Bank | 3.9x | 0.8x | 25.57% | ★★★★★★ |
| Q Technology (Group) | 3.5x | 0.2x | 42.81% | ★★★★★☆ |
| Australian Finance Group | 7.1x | 0.2x | 28.43% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 7.0x | 0.9x | 38.24% | ★★★★★☆ |
| Storage King Group | 9.2x | 5.7x | 10.16% | ★★★★★☆ |
| Citicore Energy REIT | 13.3x | 10.1x | 26.35% | ★★★☆☆☆ |
| FINEOS Corporation Holdings | 103.1x | 3.0x | 45.85% | ★★★☆☆☆ |
| Jumbo Group | 24.0x | 0.8x | 48.35% | ★★★☆☆☆ |
| Dexus Industria REIT | 17.2x | 6.2x | 20.03% | ★★★☆☆☆ |
| China Yongda Automobiles Services Holdings | NA | 0.0x | -50.60% | ★★★☆☆☆ |
We'll examine a selection from our screener results.
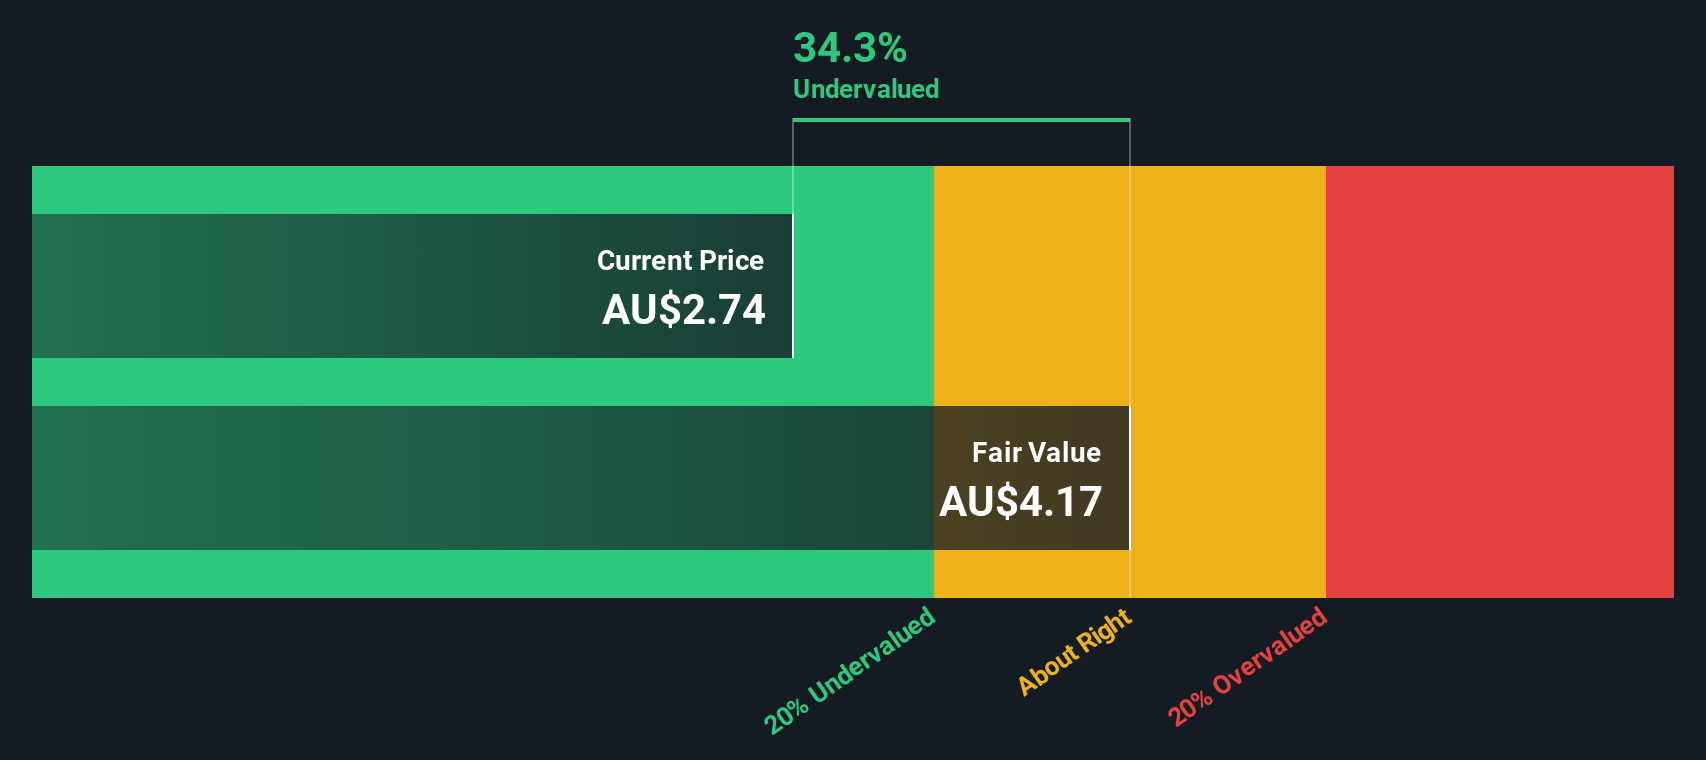
Dexus Industria REIT (ASX:DXI)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Dexus Industria REIT is a real estate investment trust focused on investing in industrial properties, with a market cap of approximately A$1.28 billion.
Operations: DXI primarily generates revenue through its investments in properties, with recent data showing a gross profit margin of 84.06%. The company has seen fluctuations in net income margins, recently recording a margin of 35.88%. Operating expenses remain relatively low compared to revenue, contributing to the company's financial performance.
PE: 17.2x
Dexus Industria REIT, a player in the industrial real estate sector, presents an intriguing case for small-cap investors in Asia. Despite a dip in earnings and revenue for the year ending June 2026—A$41.31 million net income down from A$53.08 million—the company's future looks promising with projected annual earnings growth of 6.47%. Insider confidence is evident as they have actively purchased shares recently, signaling belief in its potential despite reliance on external borrowing for funding.
Luk Fook Holdings (International) (SEHK:590)
Simply Wall St Value Rating: ★★★★★☆
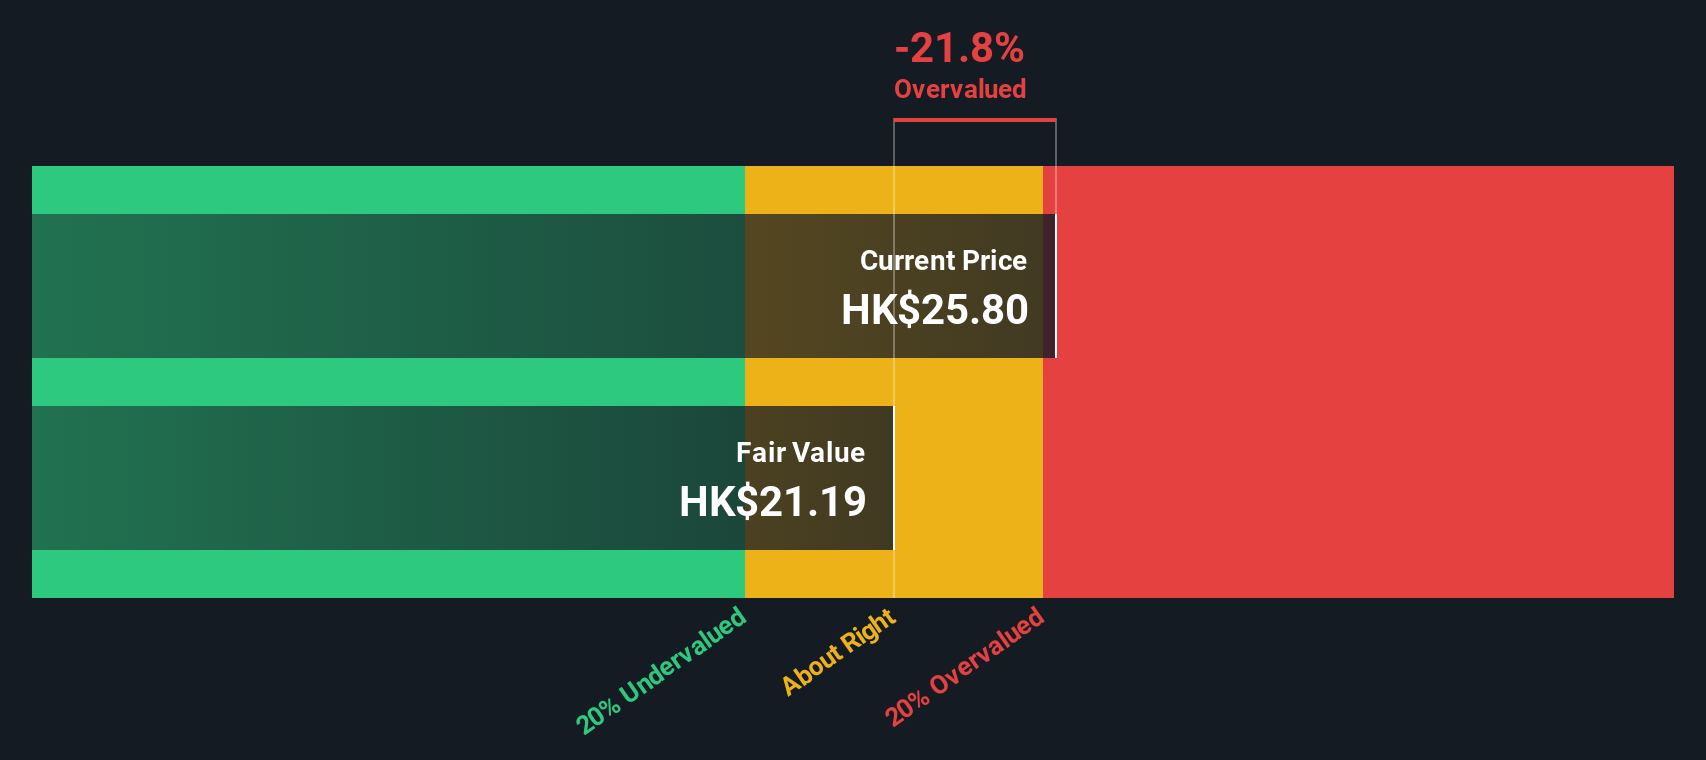
Overview: Luk Fook Holdings (International) operates primarily in the jewelry retail and wholesale sectors across Hong Kong, Macau, Mainland China, and overseas markets with a market capitalization of HK$9.34 billion.
Operations: The company generates revenue primarily through its retailing operations in Hong Kong, Macau, and overseas, which contribute significantly to its overall income. Its gross profit margin has shown an increasing trend over the years, reaching 36.68% by March 2026. Operating expenses form a substantial part of the cost structure, with sales and marketing being a major component. The company's net income margin also reflects growth over time, indicating improved profitability in recent periods.
PE: 6.1x
Luk Fook Holdings, a notable player in the jewelry sector, has seen a significant uptick in retail sales for Q1 of FY 2027. Retailing revenue surged 43% year-on-year, driven by investment gold products. The company’s RSV mix for gold and platinum products rose to 82%. Despite higher international gold prices, same-store sales (SSS) expanded notably. Insider confidence is evident with recent share purchases in early 2026. Recent board changes introduce seasoned expertise with Ms. Chiu joining as an Independent Non-executive Director, potentially strengthening governance and strategic direction amidst growth prospects.
Shangri-La Asia (SEHK:69)
Simply Wall St Value Rating: ★★★☆☆☆
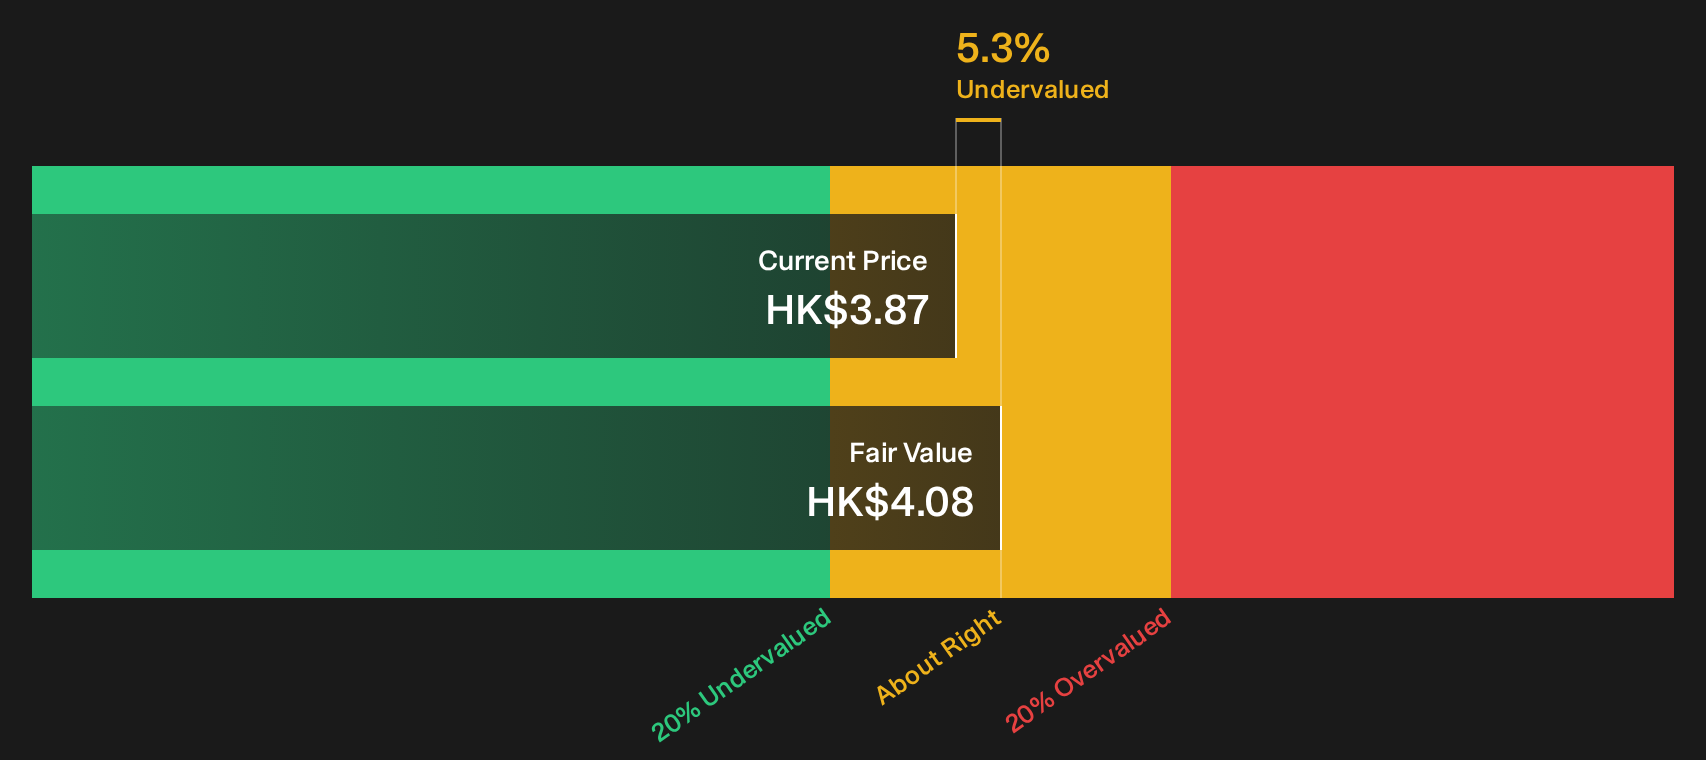
Overview: Shangri-La Asia operates a diverse portfolio of hotel properties and investment properties across various countries, with a market capitalization of approximately $3.47 billion.
Operations: The company's primary revenue streams are derived from hotel properties across various regions, with Mainland China and Hong Kong being the most significant contributors. Gross profit margin has shown an upward trend, reaching 56.22% in mid-2026. Operating expenses form a substantial part of the cost structure, with general and administrative expenses consistently exceeding $300 million in recent periods.
PE: 12.2x
Shangri-La Asia, a notable player in the hospitality sector, has seen its Chairman and CEO Hui Kwong Kuok purchase 182,000 shares for nearly US$707,543. This insider confidence suggests belief in the company's potential despite recent challenges like being dropped from the S&P Global BMI Index. For the first half of 2026, they reported increased sales of US$1.12 billion and net income of US$88.98 million compared to last year’s figures. However, their reliance on external borrowing poses financial risks as interest payments aren't well covered by earnings.
- Click here to discover the nuances of Shangri-La Asia with our detailed analytical valuation report.
Where To Now?
- Access the full spectrum of 59 Undervalued Asian Small Caps With Insider Buying by clicking on this link.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Ready To Venture Into Other Investment Styles?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com