


How Best Airport Win At Aeroports de Paris Stock Has Changed Its Investment Story
- In 2025, Aeroports de Paris reported that Paris Charles de Gaulle and Paris Orly together handled more than 107 million passengers, while Charles de Gaulle was ranked the best airport in Europe for the fifth consecutive year by Skytrax.
- This combination of record passenger volumes and repeated quality recognition suggests the ADP Group’s operational model is supporting both capacity utilisation and service consistency across its expanding global network of 26 airports serving almost 379 million passengers.
- We will now look at how Aeroports de Paris's repeated best in Europe ranking could influence the wider investment narrative for the group.
Scan beyond Aeroports de Paris and see how other travel infrastructure operators stack up on traffic, balance sheets, and pricing power with our handpicked list of solid balance sheet and fundamentals (206 results)
Aeroports de Paris Investment Narrative Recap
To own Aeroports de Paris, you need to believe that passenger volumes at Paris and international airports remain supportive of regulated aeronautical income and higher margin retail, real estate, and services revenue. The recent record traffic and Europe best airport ranking mainly reinforce the existing thesis rather than change it. In the near term, the key swing factor remains the new Economic Regulation Agreement that will shape tariffs and returns on planned capex.
The biggest near term risk still sits on the cost and balance sheet side. Rising staff expenses, higher external services, property taxes and heavy capex funded by debt could pressure cash generation if traffic or passenger spending soften. Profitability is also exposed to tax and FX noise, plus an already stretched coverage of debt and dividends by operating and free cash flows.
There have been no major fresh company announcements tied directly to this traffic and quality news, so the main reference points remain the existing regulatory and expansion framework. For investors, the thesis still revolves around how Aeroports de Paris executes on Paris hub modernization, manages leverage around a 4x net debt to recurring EBITDA level, and sustains current dividend habits that are not fully covered by free cash flow.
Against that backdrop, the 2025 passenger figures and Skytrax ranking act more as a live health check on the existing plan rather than a new catalyst. They speak to operational delivery at Charles de Gaulle and Orly. The real valuation swing variables still look tied to future tariff decisions, capex returns, cost control, and the pace of higher spending international travelers returning to luxury retail and other non aeronautical lines.
Aeroports de Paris' current analyst story points to €7.8b in revenue and €861.3m in earnings by 2029. That profile corresponds to revenue increasing at about 4.8% a year and an earnings increase of roughly €264m from €597.0m today.
Uncover why Aeroports de Paris' fair value indicates an 18% potential upside to its current price that could narrow quickly.
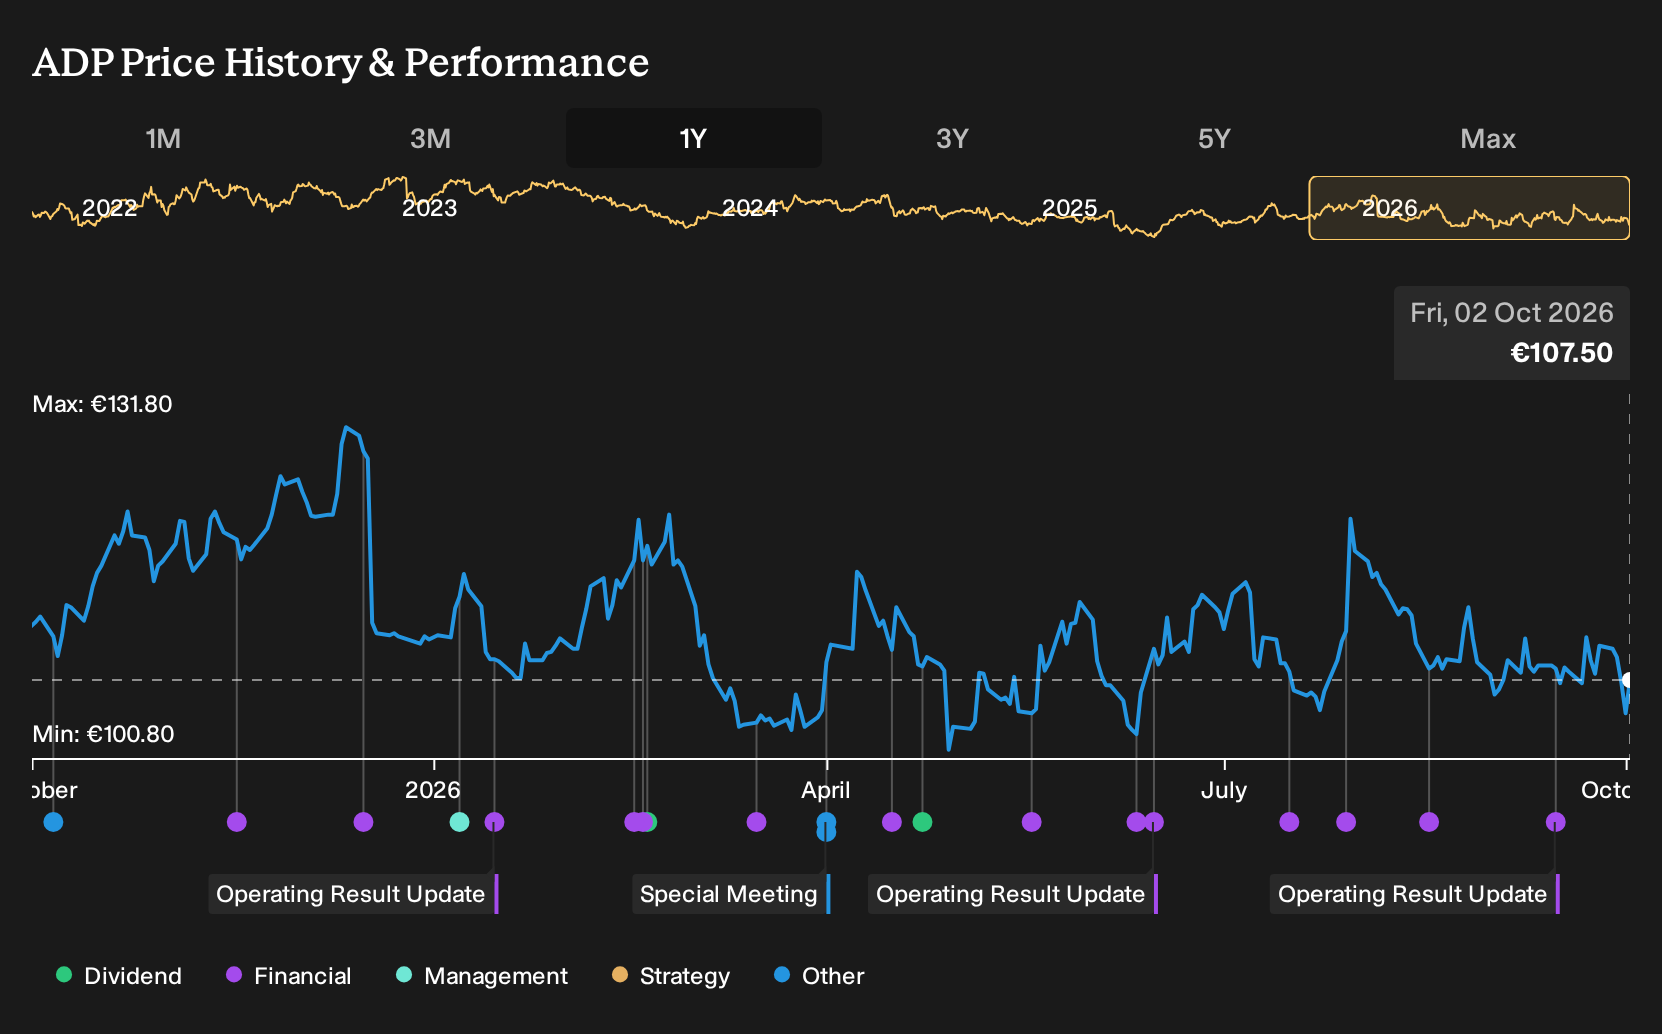
Exploring Other Perspectives
The Simply Wall St Community only has two fair value views on Aeroports de Paris so far, with estimates spread between €93.07 and €127.09 per share. That is a wide gap for a single business. When you also consider rising operating costs, debt funded capex, and regulatory uncertainty, it is clear why opinions differ. Explore those alternative takes before anchoring on your own number.
Explore another Aeroports de Paris fair value estimate, including one that suggests as much as 13% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Aeroports de Paris research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Aeroports de Paris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Aeroports de Paris' overall financial health at a glance.
Looking For More Aeroports de Paris Style Investment Ideas?
If the Aeroports de Paris story has you thinking about what else might be hiding in plain sight, it can help to scan a wider field of companies with clear financial profiles and different risk levels.
- For investors who want income plus resilience, review companies that currently screen as 168 dividend fortresses and see which ones match your return and risk comfort.
- If capital preservation matters more to you than excitement, take a closer look at businesses flagged as 227 resilient stocks with low risk scores and see how their balance sheets and volatility compare.
- For those hunting for underappreciated stories with room for re-rating, filter the market using our curated set of 615 high quality undiscovered gems and see which profiles align with your own thesis building.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com