


Terreno Realty (TRNO) Lease Momentum Puts Valuation Back In Focus
Countyline leases put Terreno Realty in focus
Terreno Realty (TRNO) just locked in 233,000 square feet of renewal leases at Countyline Corporate Park Phase III in Hialeah, Florida, with early tenant moves setting up full occupancy of Buildings 26 and 28 from 2026.
Terreno Realty’s latest lease renewals arrive after a choppy few months for the shares, with a 90 day share price return down 5.63% even as the year to date share price return sits at 9.35% and the 1 year total shareholder return reaches 15.02%. This suggests that momentum has cooled recently, while longer term holders have still seen positive overall gains.
Scan beyond Terreno Realty and compare this lease-driven momentum with a curated list of solid balance sheet and fundamentals (25 results) that are also focused on resilient real estate and infrastructure themes.
Terreno Realty now trades below both its analyst target and intrinsic value estimates. After a solid long term return and a softer 90 day patch, where does fair value really sit in that spread?
Price-to-earnings of 18.2x for Terreno Realty: Is it justified?
On current numbers, Terreno Realty trades on a P/E of 18.2x, which screens as good value relative to its own fair P/E estimate of 25.2x and below the peer average of 36.5x, even though it sits above the broader global Industrial REITs group at 15.1x.
The P/E ratio compares the share price to earnings per share and, for a real estate owner, it gives a quick sense of how much investors pay for each dollar of profit. For Terreno Realty, this lens matters because earnings are shaped by both recurring rent from its industrial portfolio and one off items that can temporarily distort the bottom line.
Recent profit growth of 52.9% over the past year, ahead of its own 5 year earnings growth of 28.9% per year and the Industrial REITs sector at 22.1%, points to the market not paying a premium multiple despite stronger recent momentum. The internal fair P/E estimate of 25.2x suggests a level that investors could gravitate toward if they place more weight on that track record and on net profit margins that currently sit at 76.9%, compared with 59.4% last year, even though those figures include a large one off gain of $210.9m in the last 12 months to 30 June 2026.
Set against that, the same forecasts flag that earnings are expected to decline by an average of 12.8% per year over the next 3 years and that return on equity of 8.8% is considered low, with projections pointing to 4.3% in three years time. Terreno Realty also relies entirely on higher risk funding sources such as external borrowing, which can matter for REIT investors who focus on balance sheet resilience alongside the dividend yield of 3.53% and a track record of reliable payouts.
The comparison with the wider global Industrial REITs group is blunt. Terreno Realty trades on a higher P/E than the 15.1x industry average while still screening as good value on both its own fair P/E of 25.2x and the peer group’s 36.5x average. This suggests the current ratio sits in a middle ground where some investors may see a discount and others may view it as a premium to the broad sector.
Explore the SWS fair ratio for Terreno Realty.
Result: Price-to-earnings of 18.2x (ABOUT RIGHT)
Still, that reliance on higher risk funding and the projected fall in earnings could quickly change how investors view Terreno Realty’s current P/E comfort zone.
Find out about the key risks to this Terreno Realty narrative.
Another view on Terreno Realty’s value
The P/E workup paints Terreno Realty as reasonably priced, yet the SWS DCF model also points to the shares trading below estimated future cash flow value, with the stock at $64.54 and the DCF mark at $66.95. That is a modest gap. How much weight do you give to a slim margin of safety?
Look into how the SWS DCF model arrives at its fair value.
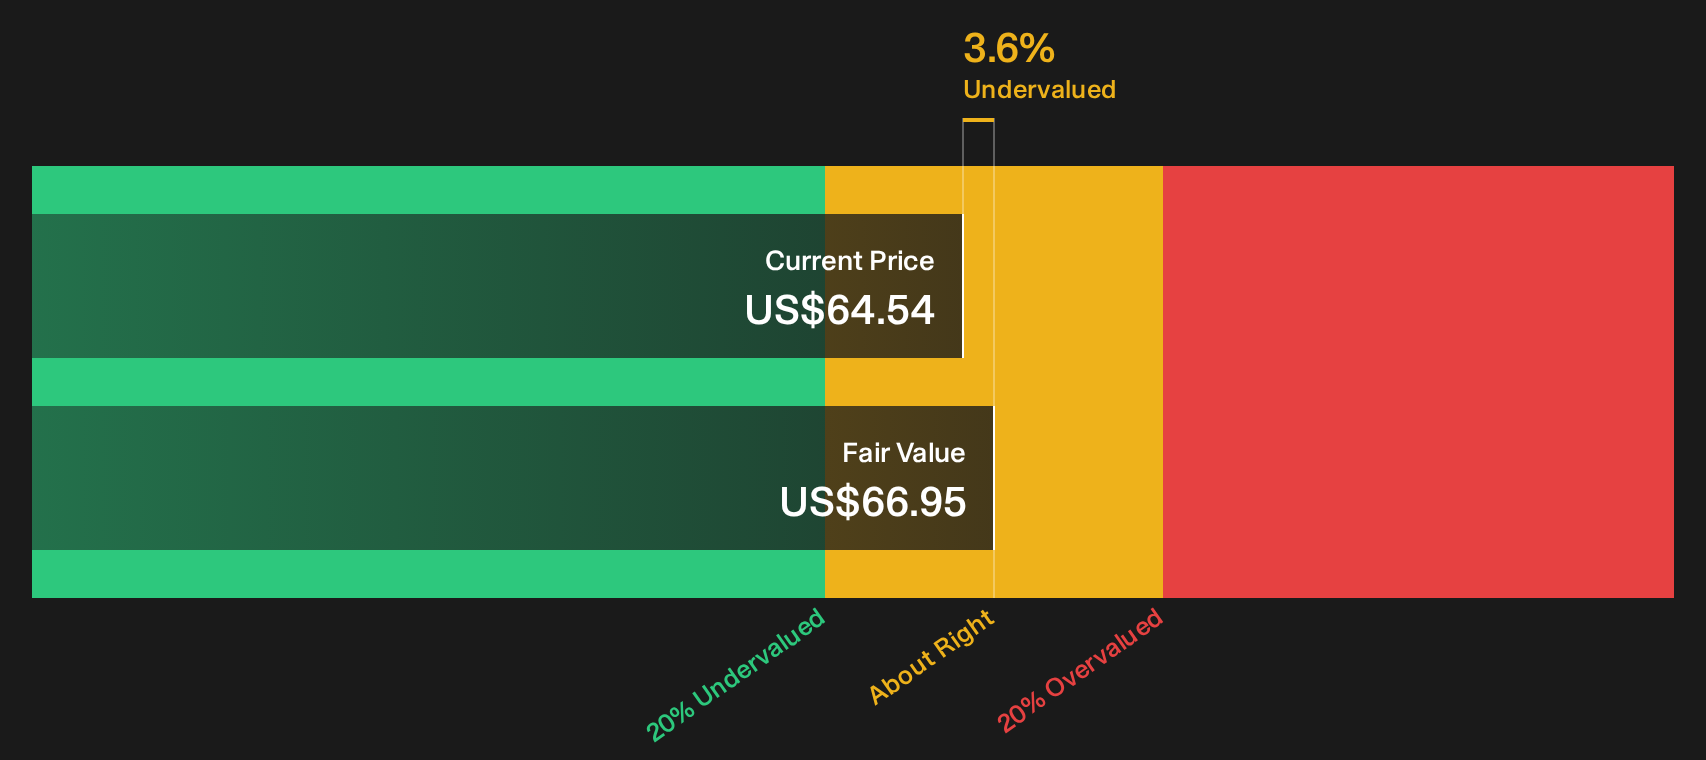
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Terreno Realty for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Terreno Realty’s valuation and funding profile make it a stock you need to judge on your own terms, so review both sides of the story with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Terreno Realty?
Terreno Realty offers one angle on industrial real estate, but your portfolio deserves a wider bench of ideas that match your risk, income, and value preferences.
- Target long term compounding by scanning a 31 high quality undervalued stocks that filters for quality businesses trading below what their fundamentals might suggest.
- Build a steadier income stream by reviewing a 7 dividend fortresses focused on higher yielding payouts backed by solid underlying financials.
- Dial back downside risk by checking a 31 resilient stocks with low risk scores that highlights companies with stronger balance sheets and more resilient profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com