


3 US Industrial Stocks Tied To Tax Cuts And Infrastructure Spending
When stronger U.S. GDP numbers hit the tape and tax cut debate flares up again, certain stocks suddenly feel far more exposed to the story playing out in Washington and at the Federal Reserve. That mix of growth optimism, inflation worries and political noise can quickly reprice winners and laggards, which is why sitting on the sidelines can feel costly. This article walks through 3 stocks directly tied to that news and explains where the risks and potential rewards now sit.
The three stocks below are just a starter set, and the full screen pulled out 20 more U.S. cyclicals with equally compelling tax cut stories that are not covered here.
If you want to quickly identify, compare and analyze the candidates that best fit your own risk profile, head straight into the U.S. Pro‑Growth, Cyclical Equities Benefiting from Tax Cuts screener.
Alamo Group (ALG)
Alamo Group plugs neatly into the pro growth, tax cut and infrastructure theme because it supplies the workhorse equipment that keeps U.S. roads, fields and cities maintained, and its fortunes rise and fall with public works budgets and industrial capital spending.
Alamo Group manufactures vegetation management and industrial equipment across two main businesses, generating about US$995 million from Industrial Equipment and US$666 million from Vegetation Management, and the stock carries a market value of roughly US$2.0b.
"Robust organic growth in the Industrial Equipment division, evidenced by record sales (+17.6% YoY), soaring backlog (~$510 million), and strong order bookings (+21% YoY in Q2), is directly tied to rising infrastructure investments and government spending, under conditions expected to persist globally, which supports continued revenue expansion and earnings growth."
The real swing factor is how one evolving pressure on future profitability shapes the next leg of Alamo Group’s earnings story.
That pressure point is exactly what the full narrative for Alamo Group unpacks, separating short term margin squeeze from a potentially accelerating long term earnings story.

Dycom Industries (DY)
Dycom Industries is one of the purest plays on the screener’s theme, because its contractors build and maintain the U.S. fiber and wireless networks that tend to see more capital poured in when growth is strong and tax rules encourage heavier domestic investment.
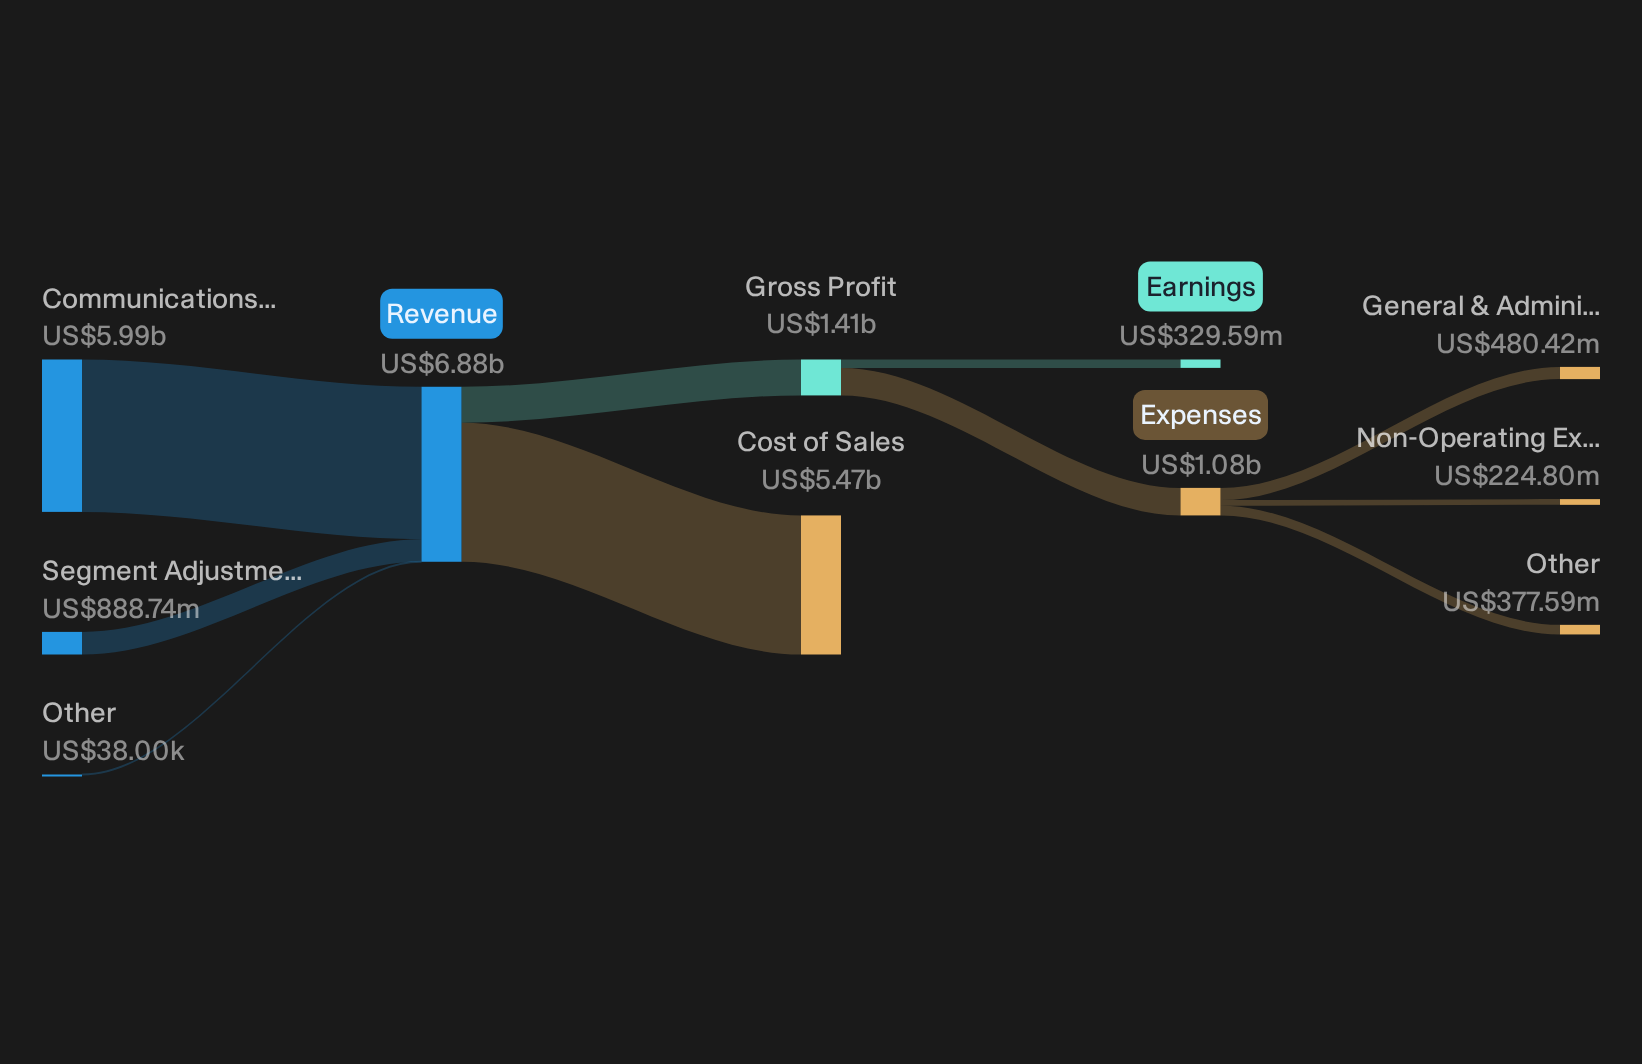
Dycom Industries provides engineering, construction and maintenance services for U.S. digital and telecom infrastructure, tying its fortunes to domestic capex and network buildouts. The business generates about US$6.0b from Communications work and related adjustments, all from within the United States, and the stock is valued around US$8.3b.
"A large, multi year build out of long haul, middle mile and inside the fence fiber to connect data centers nationwide is feeding a contracted addressable market that management sizes at about US$20b."
What really shapes the payoff for Dycom Industries is how one still unresolved cost and pricing pressure plays out against that long pipeline.
That unresolved pressure is exactly what the full narrative for Dycom Industries pulls apart, showing where pricing power, earnings quality and execution risk may be quietly decoupling.
Martin Marietta Materials (MLM)
Martin Marietta Materials plugs directly into the screener’s pro growth and tax cut theme because its aggregates and heavy building materials feed the very U.S. construction and infrastructure projects that tend to ramp up when GDP is strong and policy is friendly to capital spending.
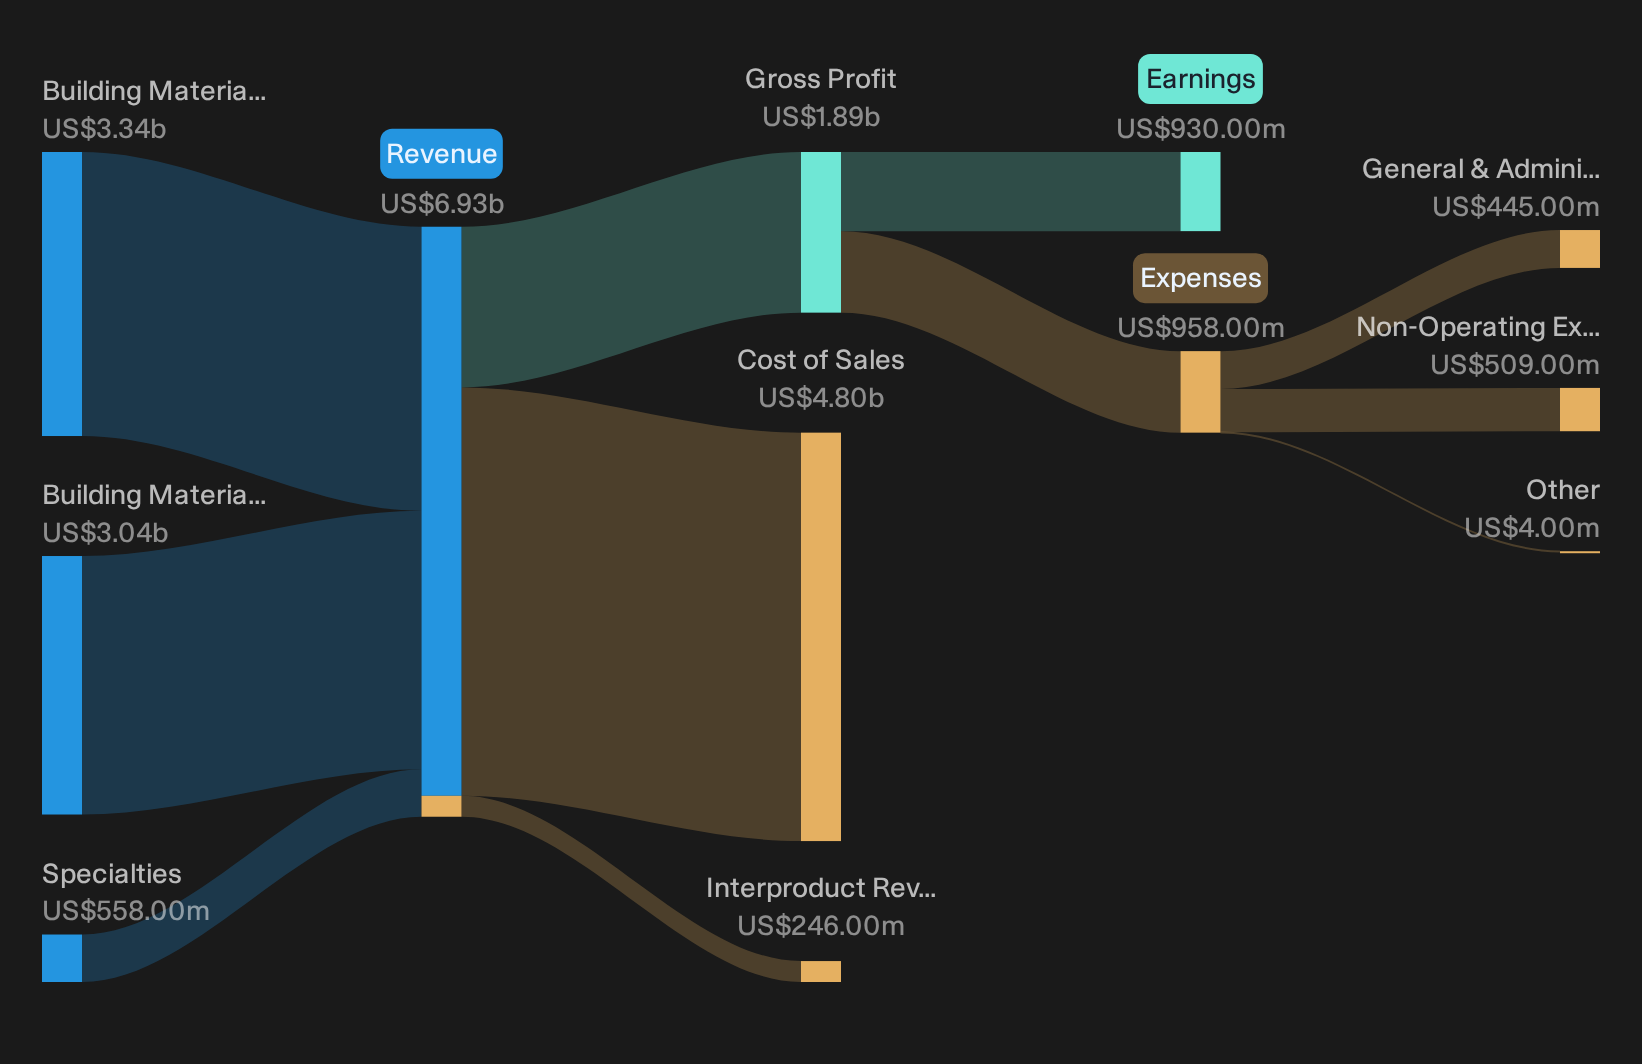
Martin Marietta Materials supplies crushed stone, sand, gravel, concrete, asphalt and magnesia-based chemicals to construction, industrial and infrastructure customers. It draws most of its revenue from the Building Materials East group at about US$3.3b and the West group at roughly US$3.0b, with Specialties at US$558 million, and the stock valued near US$34.3b.
Sustained, multi year U.S. infrastructure funding, with state Departments of Transportation advancing large multiyear construction programs supported by elevated state revenues and over US$150b of federal infrastructure funds that are yet to be invested, is expected to keep aggregates shipments and pricing for Martin Marietta Materials related to a long runway of revenue and EBITDA visibility.
The real swing factor is how one evolving cost pressure interacts with that long dated project pipeline to shape future margins and cash generation.
That cost puzzle is exactly where the full narrative for Martin Marietta Materials picks up, showing how cost inflation, pricing power and project timing could be quietly accelerating or masking Martin Marietta Materials’ next phase.
Seeking Fresh Alternatives Before They Fly
Fresh breakouts rarely stay under the radar for long. Once momentum is caught, attractive entry points can disappear quickly. Scan these curated ideas before the crowd arrives and consider them while they are still early.
- Identify resilient balance sheets early and track cash rich operators using the curated list of solid balance sheet and fundamentals (25 results). Do this while mispricing may still favor patient buyers.
- Focus on expanding automation trends and follow industry leaders through the focused 89 robotics and automation stocks. Act before robotics spending headlines draw more attention to the same trades.
- Monitor next generation energy demand and assess infrastructure contractors through the filtered 40 power grid technology and infrastructure stocks. Explore these names before grid upgrades become a widely followed theme.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com