


3 ASX Stocks That Might Be Trading Below Fair Value Estimates
The Australian stock market has experienced significant volatility recently, with a sharp decline on Thursday followed by a potential positive opening influenced by Wall Street's performance and optimism in Asian markets. In this fluctuating environment, identifying stocks that might be trading below their fair value estimates can offer investors opportunities to potentially capitalize on market inefficiencies.
Top 5 Undervalued Stocks Based On Cash Flows In Australia
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Woodside Energy Group (ASX:WDS) | A$31.24 | A$40.45 | 22.8% |
| Westgold Resources (ASX:WGX) | A$5.25 | A$6.71 | 21.7% |
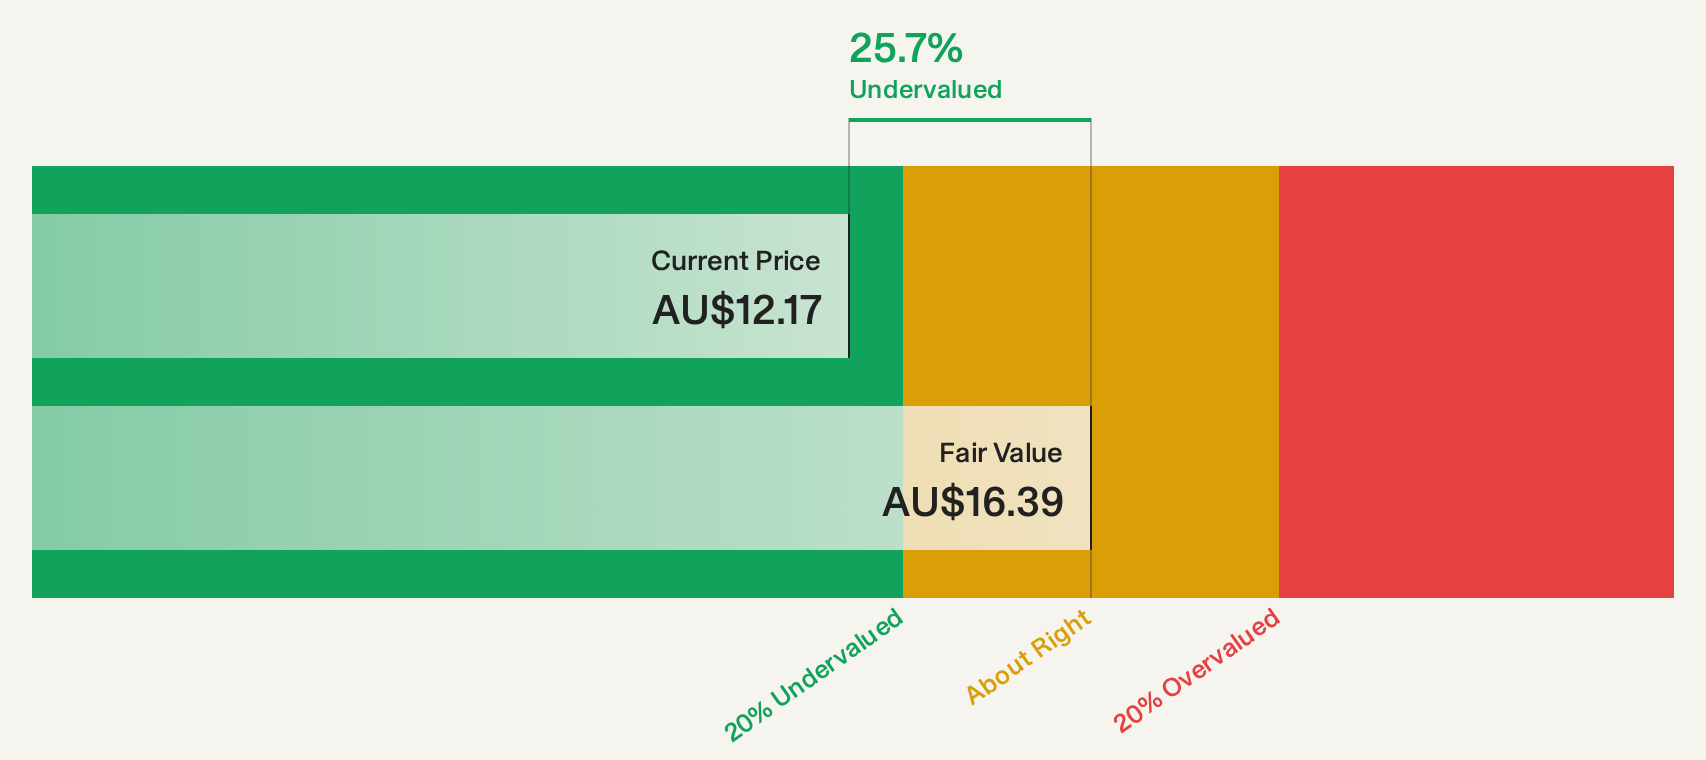
| Ricegrowers (ASX:SGLLV) | A$12.71 | A$16.39 | 22.4% |
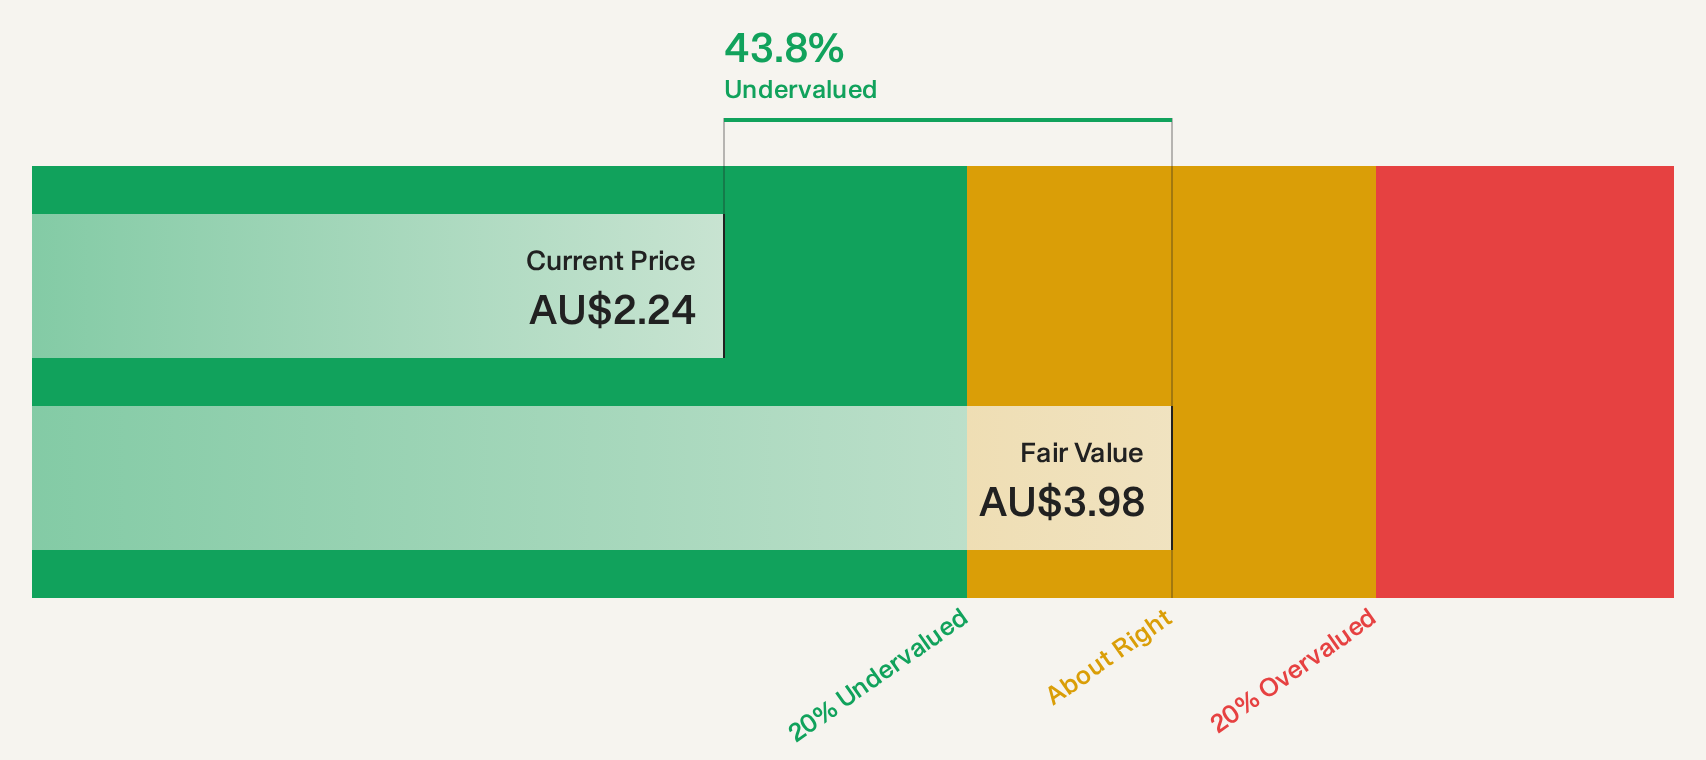
| Qualitas (ASX:QAL) | A$2.22 | A$3.98 | 44.3% |
| NobleOak Life (ASX:NOL) | A$1.28 | A$2.03 | 37% |
| MotorCycle Holdings (ASX:MTO) | A$2.53 | A$4.40 | 42.6% |
| LaserBond (ASX:LBL) | A$0.535 | A$0.78 | 31.6% |
| Greatland Resources (ASX:GGP) | A$10.31 | A$15.41 | 33.1% |
| Ansell (ASX:ANN) | A$44.55 | A$62.64 | 28.9% |
Here we highlight a subset of our preferred stocks from the screener.
Ansell (ASX:ANN)
Overview: Ansell Limited is a global company that designs, sources, develops, manufactures, distributes, and sells hand and body protection solutions across various regions including the Asia Pacific, Europe, the Middle East, Africa, Latin America, the Caribbean, and North America with a market cap of A$6.18 billion.
Operations: The company's revenue is primarily derived from its Healthcare segment, which generated $1.19 billion, and its Industrial segment, including Specialty Markets, which contributed $947.30 million.
Estimated Discount To Fair Value: 28.9%
Ansell is trading at A$44.55, significantly below its estimated future cash flow value of A$62.64, suggesting it is undervalued based on cash flows. Despite slower revenue and earnings growth forecasts compared to the Australian market, Ansell's recent buyback of shares worth A$118.4 million and a healthy funding position for potential acquisitions indicate strategic capital management efforts to enhance shareholder value while maintaining a focus on organic growth initiatives.
- The growth report we've compiled suggests that Ansell's future prospects could be on the up.
- Delve into the full analysis health report here for a deeper understanding of Ansell.
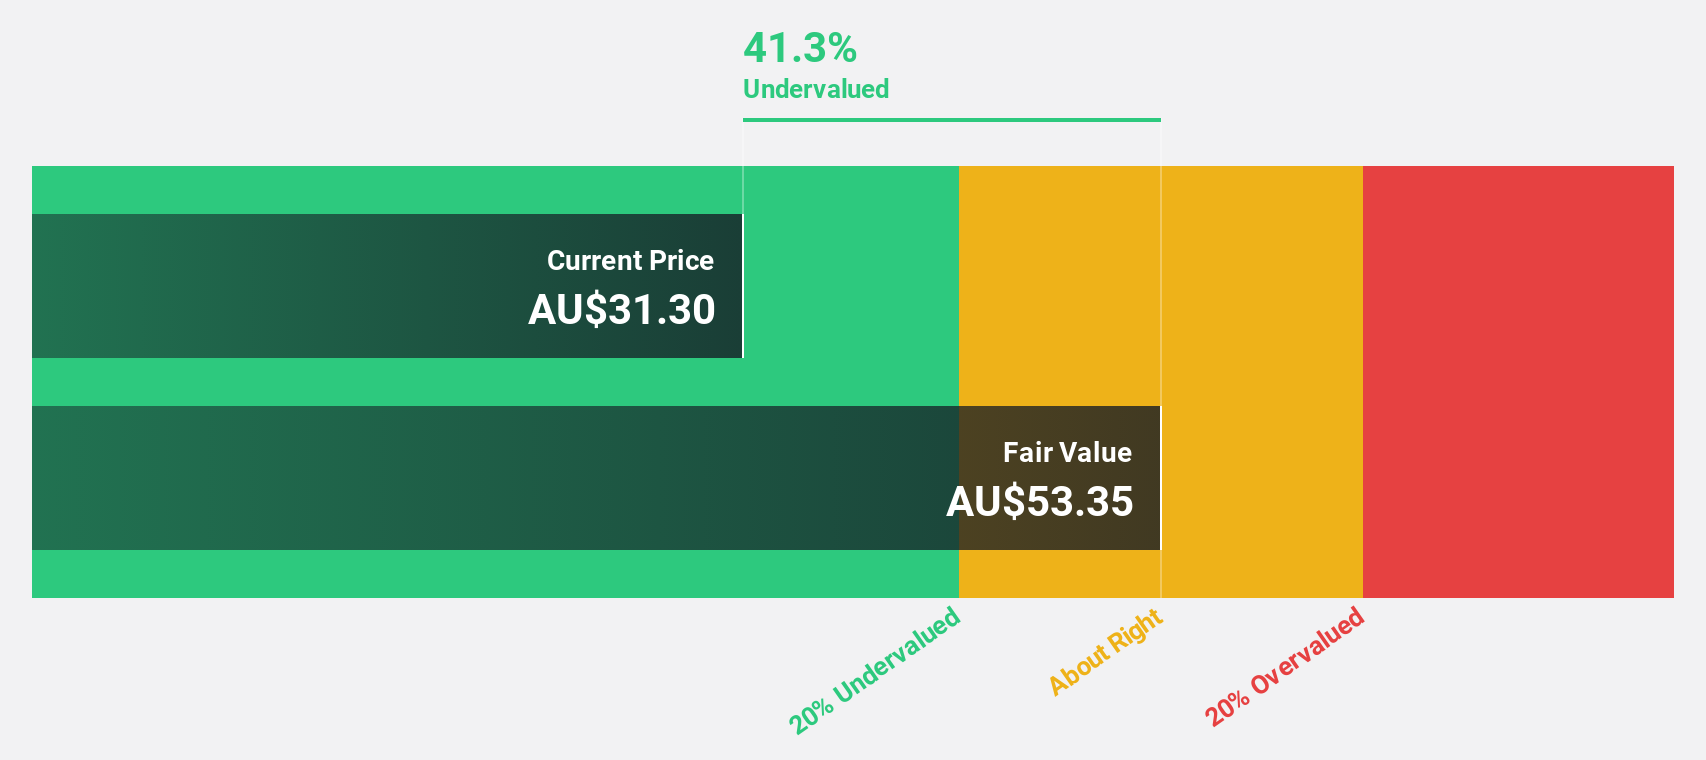
Qualitas (ASX:QAL)
Overview: Qualitas Limited is an alternative real estate investment manager that focuses on risk-adjusted investments in real estate private credit and equity, with a market cap of A$657 million.
Operations: The company's revenue is derived from Direct Lending, which contributes A$0.04 million, and Funds Management, contributing A$14.63 million.
Estimated Discount To Fair Value: 44.3%
Qualitas is trading at A$2.22, well below its estimated future cash flow value of A$3.98, highlighting undervaluation based on cash flows. The company reported a revenue increase to A$129.56 million and net income growth to A$41.72 million for the year ended June 2026, showcasing strong financial performance. However, its dividend yield of 5.07% is not sufficiently covered by free cash flows, which may pose sustainability concerns despite positive earnings growth forecasts surpassing market averages.
- According our earnings growth report, there's an indication that Qualitas might be ready to expand.
- Dive into the specifics of Qualitas here with our thorough financial health report.
Ricegrowers (ASX:SGLLV)
Overview: Ricegrowers Limited is a rice food company with operations across Australia, New Zealand, the Pacific, Asia, Europe, the Middle East, Africa, and North America and has a market cap of A$875.72 million.
Operations: The company's revenue is primarily derived from its Consumer Packaged Goods International segment at A$736.68 million, Consumer Packaged Goods Australia & New Zealand segment at A$735.29 million, and Bulk Rice and Animal Feed segment at A$327.90 million.
Estimated Discount To Fair Value: 22.4%
Ricegrowers is trading at A$12.71, below its estimated future cash flow value of A$16.39, indicating undervaluation based on cash flows. Despite a forecasted revenue growth of 2.1% per year, which lags behind the Australian market's 5.1%, the company offers good relative value compared to peers and industry standards. Recent guidance suggests earnings will be impacted by cost inefficiencies due to a smaller Australian rice crop, potentially affecting short-term profitability despite underlying branded business growth.
- In light of our recent growth report, it seems possible that Ricegrowers' financial performance will exceed current levels.
- Get an in-depth perspective on Ricegrowers' balance sheet by reading our health report here.
Make It Happen
- Unlock more gems! Our Undervalued ASX Stocks Based On Cash Flows screener has unearthed 6 more companies for you to explore.Click here to unveil our expertly curated list of 9 Undervalued ASX Stocks Based On Cash Flows.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Elevate your portfolio with Simply Wall St, the ultimate app for investors seeking global market coverage.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com