


NICE Stock Faces EPS Drop Ahead Of Revenue Growth
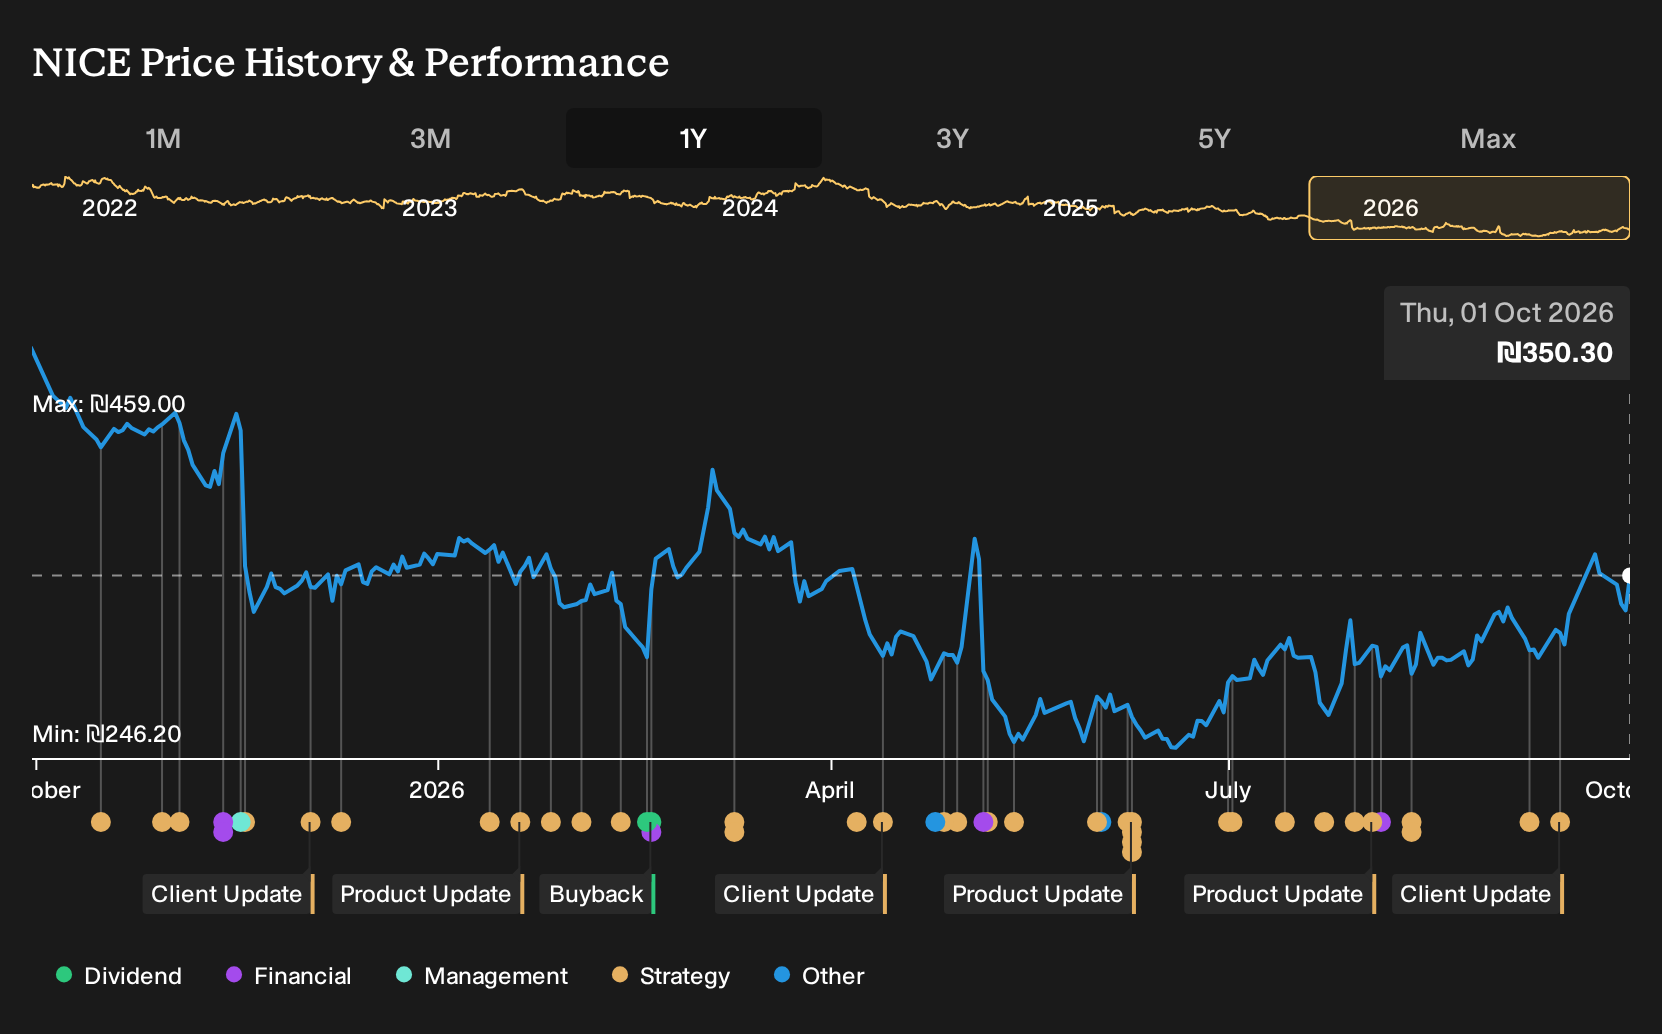
- NICE recently saw its stock decline 2.3% even as broader indices rose, with upcoming quarterly EPS projected to fall 12.58% while revenue is expected to reach 7.44% growth.
- The combination of higher projected sales and lower per share earnings points to rising cost or mix pressures that could test NICE's margin story more than its demand profile.
- It remains to be seen how NICE's investment narrative holds up against the projected EPS decline despite revenue growth expectations for the coming quarter.
Compare NICE's setup to a hand-picked 192 high quality undervalued stocks that currently pair firmer earnings trends with what may be more resilient margin profiles.
NICE Investment Narrative Recap
NICE still asks investors to believe in a long runway for AI powered customer engagement and financial crime platforms, with recurring cloud revenue at the center of the story. The near term tension is that projected EPS is set to decline 12.58% even as revenue is expected to rise 7.44%. That points to profit pressure more than demand weakness.
The key near term catalyst is whether cloud investments and international expansion start to relieve margin strain after a year in which net profit margins moved lower. The biggest risk is that spending on infrastructure, deals and AI capabilities keeps outpacing efficiency gains. If that occurs, this EPS air pocket could be part of a longer profitability squeeze.
Recent commentary around NICE highlighted growth in AI and self service ARR and the integration of Cognigy’s conversational AI as a meaningful product milestone. For a business built on high margin cloud subscriptions, that kind of volume in AI driven features is directly relevant to the margin debate now that EPS is projected to fall while sales are set to rise.
The same update pointed to large enterprise deals, international cloud traction and tight relationships with partners such as AWS, Salesforce, ServiceNow and Snowflake as important revenue drivers. These are useful supports for the current pullback in earnings, although they come with their own risk. Heavy deal and infrastructure commitments can strain profitability if customer adoption or upsell takes longer than expected.
NICE's narrative projects US$4.0b revenue and US$638.7m earnings by 2029. This assumes 9.8% yearly revenue growth and an earnings increase of about US$109m from current earnings of US$529.6m.
Uncover why NICE's fair value indicates a 77% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community cluster between about US$621 and US$737 per share, so even this small sample spans a wide band for NICE. These retail models pre date the recent EPS downtick and Zacks Rank #4 (Sell), so treat them as a starting point and explore more perspectives before relying on any single narrative.
Explore another NICE fair value estimate, including one that suggests potential upside of as much as 110% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your NICE research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NICE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NICE's overall financial health at a glance.
Looking For More Ideas Beyond NICE?
If the NICE story leaves you wanting a broader watchlist, it can help to put it next to other companies with very different profiles and risk setups. The Simply Wall St Screener lets you scan for stocks that fit the kind of earnings resilience, balance sheet strength or yield profile you want to compare against NICE before committing fresh capital.
- If capital preservation sits high on your list, check out a 227 resilient stocks with low risk scores that may suit a more defensively minded approach.
- For investors who care most about quality and price discipline, you can scan a 615 high quality undiscovered gems that might not yet be crowded trades.
- If your focus is on financial strength first, start with a list of solid balance sheet and fundamentals (206 results) that can help you benchmark leverage and liquidity across candidates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com