


What McCormick Shares Third Quarter Results Means For Shareholders
- McCormick reported third quarter 2026 sales of US$2,024.8 million and nine month sales of US$5,835.3 million, while reaffirming full year earnings guidance and projecting full year net sales growth of 13% to 17%.
- The mix of lower quarterly net income against higher year to date profit and the maintained outlook highlights how timing, integration progress, and cost dynamics are shaping McCormick’s current earnings profile.
- We will now look at how McCormick’s reaffirmed full year net sales growth outlook could reshape the existing investment narrative.
McCormick Investment Narrative Recap
To own McCormick, you need to believe this flavor platform can keep turning its brand strength and category reach into steady, volume backed revenue while managing integration complexity and debt. The reaffirmed 13% to 17% net sales growth outlook suggests management still sees that commercial engine working. The near term pivot point remains execution on the Unilever Foods combination, because synergy delivery and smooth integration frame how sustainable any earnings profile looks from here.
The biggest risk still sits in operational strain. There is high leverage on the balance sheet, regulatory scrutiny around the Unilever deal, and pressure in Consumer Americas from private label and branded rivals. The latest quarter, with strong year to date profit but softer quarterly earnings, reinforces that timing, cost phasing, and integration expenses can easily weigh on reported income and keep volatility elevated even when sales are healthy.
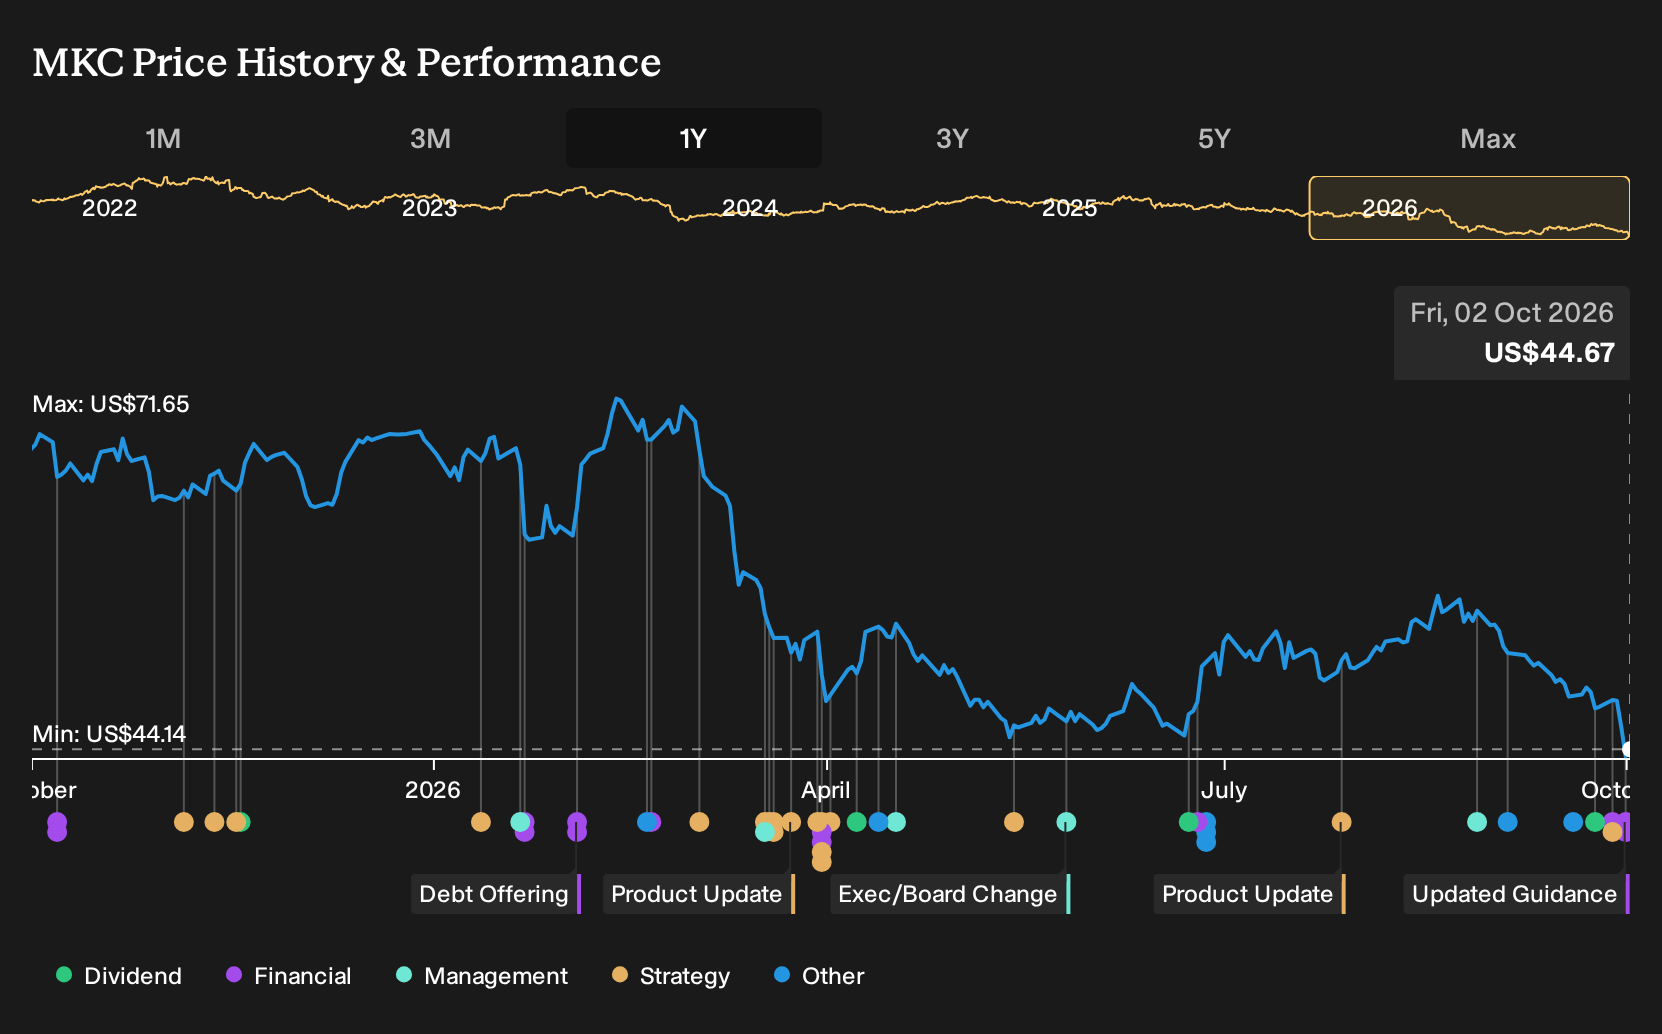
Among the recent announcements, the auditor change from EY to KPMG around the Unilever Foods transaction is the one that matters most for this earnings story. The shift is tied to independence rules after the deal closes, so it sits directly in the plumbing that will govern how the enlarged McCormick is audited and reported. That is not a revenue lever, but it does sit close to the quality and reliability of future financial disclosure on synergies, margins, and cash generation.
For catalysts, this move intersects with the core question of integration execution. Investors watching McCormick will likely track how quickly KPMG comes up the curve on the combined business and whether there is any friction in year one of the new audit relationship. Any delay in closing the acquisition, slower synergy capture, or bumps in reported figures during the handover could amplify existing concerns around earnings trajectory and the ability to turn strong top line guidance into consistent, visible profit and cash flow.
McCormick's current analyst script points to US$8.7b in revenue and US$693.1 million in earnings by 2029, anchored on 5.8% yearly top line growth. That outlook implies a decline of about US$906.9 million in earnings from the US$1.6b reported today, rather than an increase.
Discover how McCormick's fair value suggests a 35% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
One alternate angle focuses on cost pressure rather than integration risk. Bullish analysts still pencilled in McCormick revenue of about US$9.0b and earnings near US$799.4 million by 2029 before this guidance update, even while flagging ongoing inflation as a threat to margins. You can treat today’s reaffirmed 13% to 17% sales outlook as a fresh test of those more optimistic assumptions and consider how that might influence your own view.
Explore 5 other McCormick fair value estimates, including one that suggests up to 250% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your McCormick research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for McCormick. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate McCormick's overall financial health at a glance.
Looking for more McCormick style investment ideas?
If McCormick’s story has you thinking about what else might be hiding in plain sight, it can help to scan a broader set of opportunities and compare business quality, balance sheet strength, and income potential side by side.
- For investors who want stability first, consider screening for companies with healthier financing and stronger fundamentals through a list of solid balance sheet and fundamentals (25 results).
- If value is your priority, you can focus on mispriced opportunities where quality and valuation intersect by reviewing a 31 high quality undervalued stocks.
- Those looking to get in early on quieter stories may prefer businesses with strong financial traits that are not widely followed yet, which is where a 19 high quality undiscovered gems can be useful.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com