


ABB (SWX:ABBN) Climbed, So What Is Behind The Fresh Attention?
Why ABB stock is back in focus after the Infinitus launch
ABB (SWX:ABBN) has drawn fresh attention after launching Infinitus, a direct current power portfolio aimed at AI data centers that are facing higher electricity needs and tighter space constraints.
The Infinitus launch lands at a moment when ABB has already been on a strong run, with the 1-month share price return of 5.32% adding to a year-to-date gain of 33.74% and a 1-year total shareholder return of 41.73% that builds on very strong 3 and 5-year total shareholder returns. This hints that momentum remains positive, while the recent 90-day share price decline of 5.97% shows investors are still adjusting their risk and growth expectations around new projects and product bets like AI power infrastructure.
Scan a curated field of electrification and AI-infrastructure peers by focusing on resilient enablers of this trend with the 40 power grid technology and infrastructure stocks.
ABB’s recent surge and the Infinitus launch leave you weighing two paths. Is it worth paying up after this run, or does waiting for a cleaner entry make more sense once the valuation is on the table?
Most Popular Narrative: 3% Undervalued
ABB last closed at CHF81.90, a touch below a narrative fair value of CHF84.81. This puts the Infinitus story into a valuation context rather than just a headline.
Record-high order backlog ($25 billion), broad-based order growth across regions, and multi-year service contracts in process automation provide strong forward earnings visibility and support for sustained revenue and margin expansion over the medium to long term.
See why 75 investors see ABB as 3% undervalued.
Result: Fair Value of CHF84.81 (UNDERVALUED)
Still, ABB’s narrative could be knocked off course if weaker demand in areas like automotive and machine automation lingers, or if rising competition in China continues to pressure pricing.
Find out about the key risks to this ABB narrative.
Another View: What ABB’s P/E Is Telling You
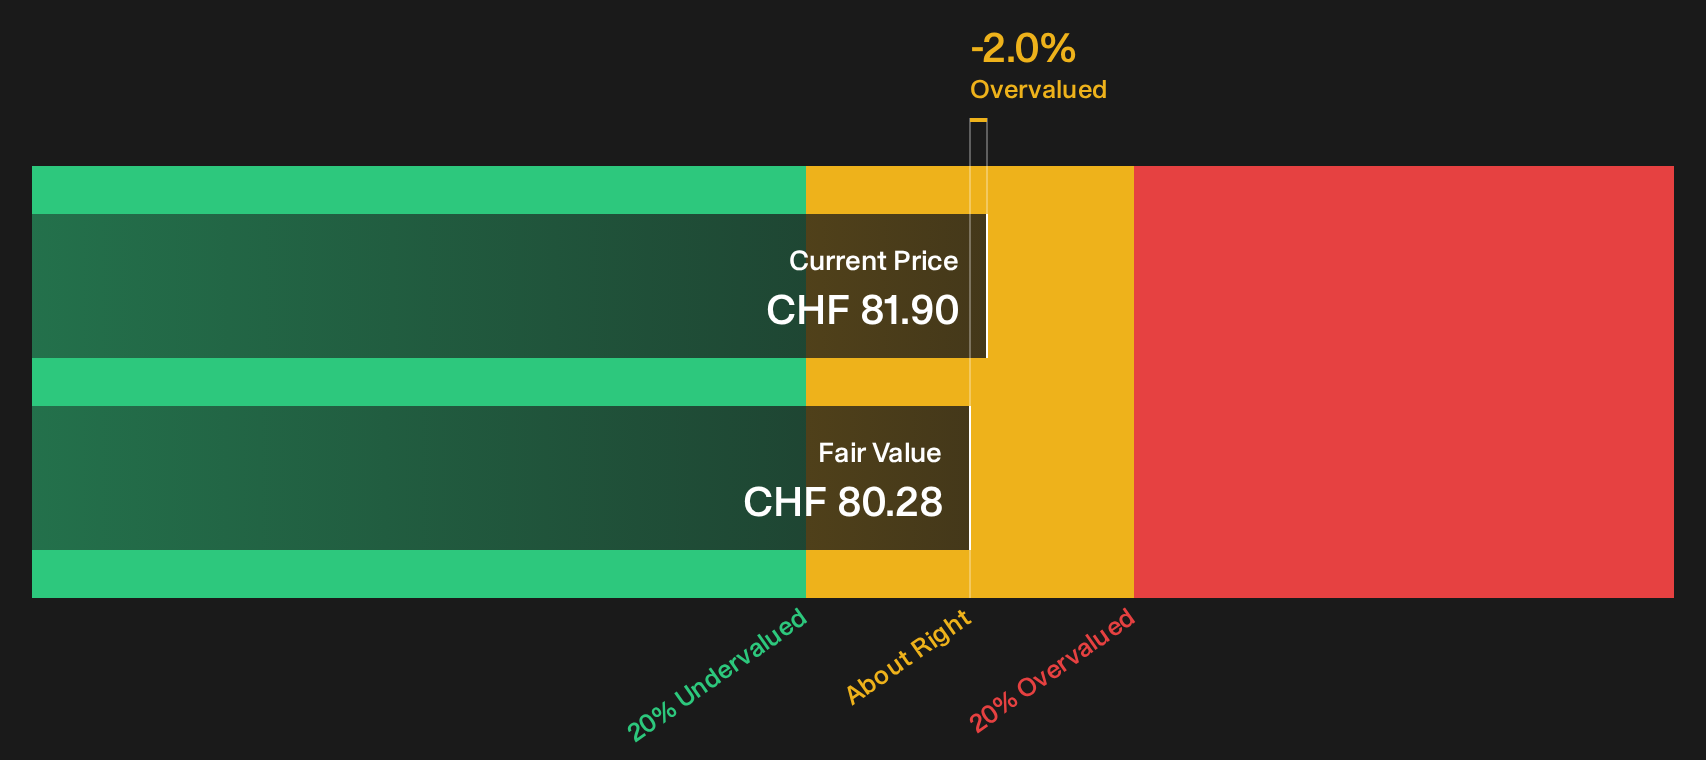
The SWS DCF model points to ABB shares being slightly above an estimated future cash flow value of CHF80.28 at today’s CHF81.90 price, which leans toward an overvalued signal. That sits against the 3% undervalued narrative. Which compass do you trust more: cash flows or consensus?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on ABB so far. Take a moment to look through the full picture for yourself and shape your own stance with the 2 key rewards and 1 important warning sign.
Looking for more ABB-linked investment ideas?
If ABB has your attention, do not stop at one opportunity. Cast the net wider with a few focused stock lists that match different goals and risk levels.
- Target resilient value by scanning a curated field of companies that score well on quality and pricing through the 192 high quality undervalued stocks.
- Prioritise capital strength and steady operations by reviewing a list of solid balance sheet and fundamentals (206 results) that can support shocks and reinvestment.
- Spot early-stage potential before it is widely followed by using our 615 high quality undiscovered gems while these stories are still off most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com