


What Visteon (VC)'s New OEM Wins Means For Shareholders
- Visteon has secured around US$1.9b of new automotive electronics business with manufacturers including Toyota and several Chinese OEMs, centered on digital cockpit and display programs.
- These wins deepen Visteon’s role inside the vehicle cabin by tying its cockpit AI and large-display platforms directly to future model pipelines of key automakers.
- We will now look at how Visteon’s investment narrative could shift as cockpit AI gains traction through these fresh program awards.
Scan other cockpit and auto-tech plays that are moving on similar themes of software-heavy vehicles and AI-driven display systems with our curated list of 90 AI infrastructure stocks.
Visteon Investment Narrative Recap
Owning Visteon means believing that cockpit AI and large in car displays become standard equipment across more models, and that this specialist supplier keeps winning those programs. The fresh US$1.9b of awards aligns with that thesis. In the near term, the key factor is how quickly those booked deals turn into production volumes and revenue.
The biggest near term risk still appears operational. Tariff policy and softer demand tied to China can disrupt production plans, squeeze margins and delay launches tied to those new wins. Margin pressure is already visible, with net profit margins at 3.8% compared with 8.4% last year.
The most relevant update here is the US$1.9b in recent business wins, including programs with Toyota and fast growing Chinese manufacturers. Those commitments plug directly into Visteon’s cockpit AI and display platforms, which analysts already expected to support earnings growth of about 18.8% a year.
For catalysts, that award book gives investors something concrete to track. The focus now is on how management executes on these model launches, manages tariff developments and stabilises profitability. If cost controls and supply chain planning keep pace with the new work, the existing order pipeline can remain a central part of the Visteon story.
Visteon's current analyst narrative points to revenues of US$4.4b and earnings of US$290.4m by 2029, based on an assumed 5.2% yearly revenue growth rate and an earnings increase of about US$125m from US$165.0m today.
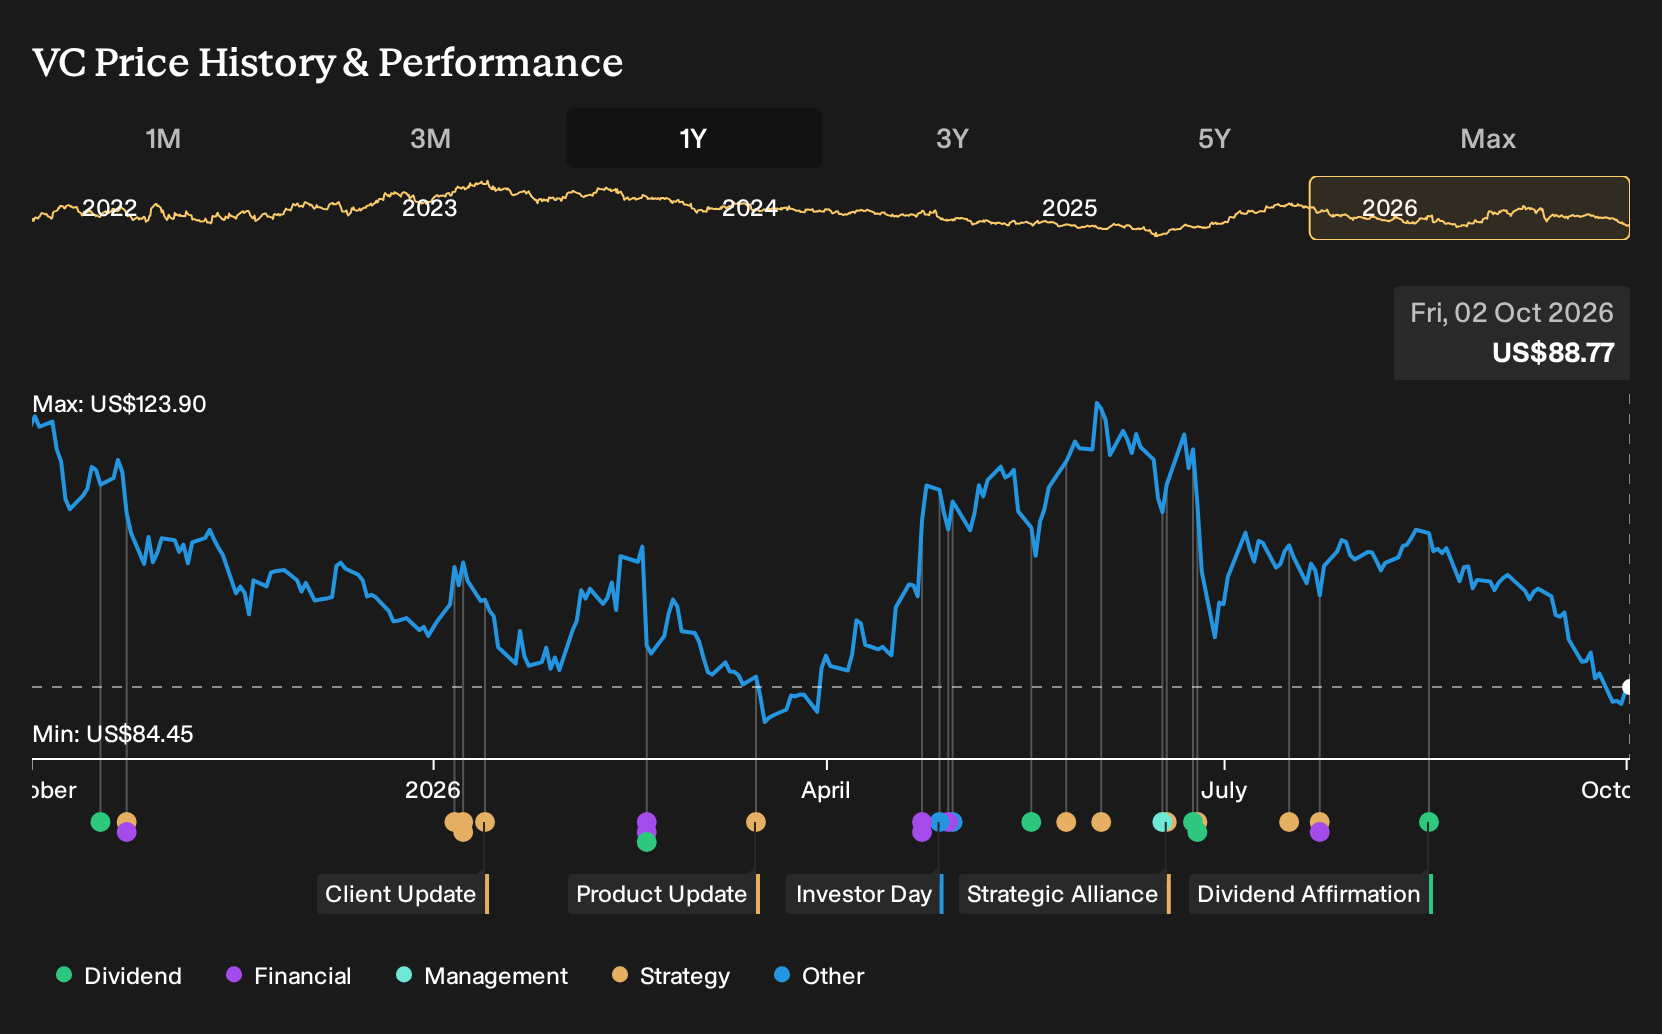
Uncover why Visteon's fair value indicates a 51% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view leans on customer concentration risk. If a few large automakers scale back orders or push more electronics in house, Visteon could see choppier revenue than consensus expects. Bullish analysts still penciled in US$4.7b of sales and US$324.9m of earnings by 2029 before this news, so their narrative may shift meaningfully from here.
Explore another Visteon fair value estimate, including one that suggests there could be as much as 126% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Visteon research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Visteon. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Visteon's overall financial health at a glance.
Looking For More Investment Ideas Beyond Visteon?
If the Visteon story has you thinking more broadly about your portfolio, it can help to scan for other businesses that fit clear financial themes using the Simply Wall St Screener.
- For investors who want potential mispricings with quality fundamentals, start with a focused set of 31 high quality undervalued stocks that may warrant a place on your watchlist.
- If capital preservation and steadier profiles matter more to you than rapid growth, filter for 31 resilient stocks with low risk scores and see which companies line up with that preference.
- When you prefer rock solid finances as your foundation, zero in on a list of solid balance sheet and fundamentals (25 results) that can help you build a shortlist grounded in financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com