


Franklin Templeton Holders Backed The Harder Case Not The Obvious One
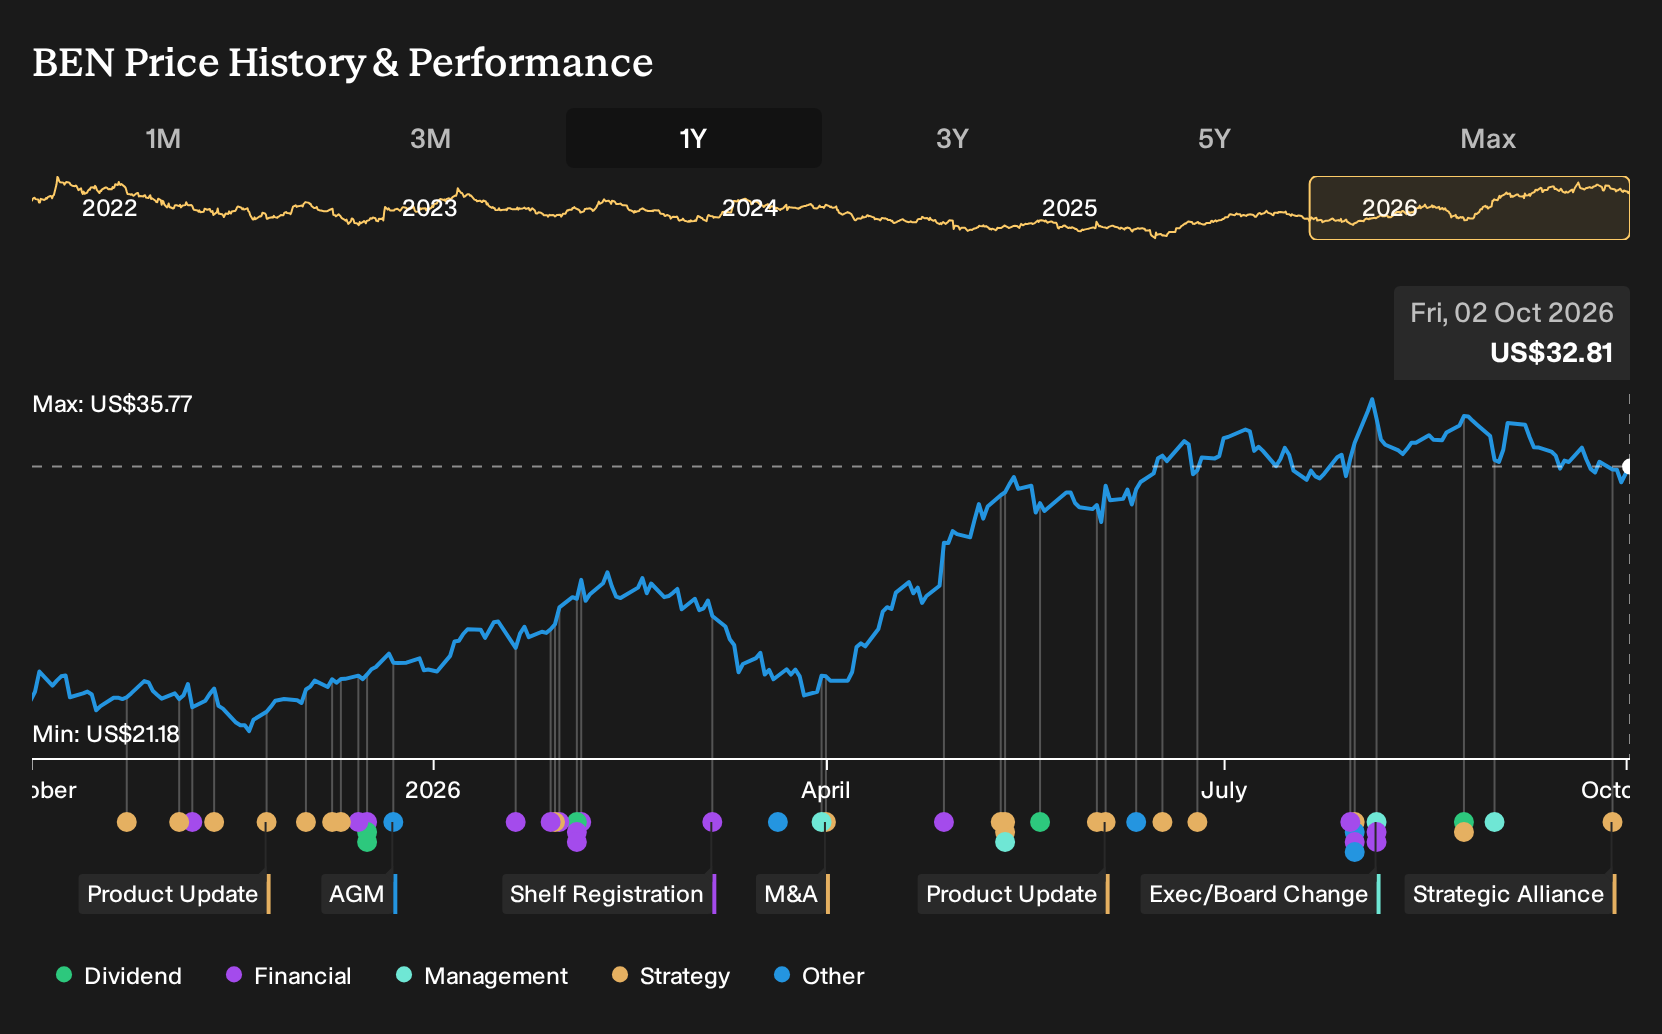
If you only glanced at the headlines on Franklin Templeton over the past year, the story might look messy. There was a $100 million SEC settlement at Western Asset and fresh crypto experiments, alongside record inflows and higher profits. Holding Franklin Templeton over the past year would have returned 44.7%, including dividends. If you had been weighing those bullish Uzbekistan and Saudi expansion arguments against fears about fee pressure and digital misfires back in October 2025, what should have stood out most?
Franklin Templeton has already moved. Pinpoint other ways to investigate the theme among 18 cryptocurrency and blockchain stocks.
The Two Franklin Templeton Stories Investors Were Arguing About
The shares cost US$22.91 at the start, and Franklin Templeton sat between two very different but credible storylines about where the business could head next.
On the optimistic side, one view said the Uzbekistan and Saudi Arabia push, plus alternatives and tokenized funds, could support gradual expansion. That narrative pointed to a Fair Value of US$25, a price that only worked if revenue grew 1.0% a year and profit margins reached 15.6% with a future P/E of 11.7x.
The cautious narrative flagged legacy active funds, fee compression, and tech rivals as ongoing headwinds. In that version, a Fair Value of US$19 rested on the idea that revenue would edge down 0.2% a year even as margins improved to 11.6%, with the shares worth only 12.5x those assumed earnings.
What The Results Changed For The Franklin Templeton Debate
The launch of Franklin Crypto after acquiring 250 Digital, plus new crypto-linked ETFs and a $1.5b private markets CFO, leaned toward the optimistic Franklin Templeton storyline that talked up alternatives, digital assets, and new channels. At the same time, the $100 million Western Asset settlement and related leadership change kept the cautious view about regulatory and legacy active risks alive. Overall, the evidence cut both ways.
The key assumption here was whether diversification beyond traditional active funds would actually show up in the numbers. Readers can test that at other asset managers by tracking long term net inflows into alternatives and digital products alongside the reported net margin in quarterly filings.
What Franklin Templeton's Run Now Asks You To Believe
At US$32.81, Franklin Templeton is priced above where the earlier October 2025 debate started, and the selected Narrative’s Fair Value still sits above the current price. The focus has shifted to how far alternatives, ETFs, SMAs and digital tools can reshape the earnings mix rather than just overall assets.
The Narrative leans on expanding private markets vehicles, personalization platforms and AI enabled distribution to do more of the heavy lifting. It argues that today’s price still does not fully credit Franklin Templeton successfully scaling these higher fee segments while keeping operating margins near management’s targets.
"The view on Franklin Templeton has shifted from a broad focus on potential AUM inflection and diversification to a more targeted expectation that its expanding alternatives platform, evergreen private markets vehicles, and AI enabled distribution tools can reshape the earnings mix and support more scalable margins over time."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 24% below our estimate - supplies liquid cooling systems using outdoor radiators for dense data centers.
- Company 2 - 48% below our estimate - serves construction markets by delivering steel reinforcement products for funded infrastructure projects.
- Company 3 - 42% below our estimate - shifts electronics capacity from legacy consumer programs toward higher-value AI and data center hardware.
Three companies from the same screener. Open every one of the 31 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com