


Butterfly Network (BFLY) Reached A Commercial Milestone, Is It Still 21% Undervalued?
Butterfly Network (BFLY) drew fresh attention after Mendaera’s Focalist system moved into commercial use with Butterfly’s Ultrasound-on-Chip technology, the first Butterfly Embedded partner solution to reach the market.
The commercial launch with Mendaera comes at a time when Butterfly Network’s 1-month share price return of 21.60% and year-to-date share price return of 138.67% point to building momentum. Over a longer window, a very large 3-year total shareholder return of about 7x shows how sharply sentiment around the stock has shifted, despite a 5-year total shareholder return that remains down 16.43%.
Seize this momentum in Butterfly Network and see how it compares to other health-focused AI imaging plays with our hand-picked 35 healthcare AI stocks.Butterfly Network now trades well below the average analyst target, even after a sharp year-to-date move. Does that gap reflect lingering risk or a valuation that has not fully adjusted yet?
Most Popular Narrative: 21% Undervalued
Against a last close of $8.95, the most followed valuation storyline for Butterfly Network points to a fair value of $11.40, which places the current pricing at a meaningful discount and frames recent licensing deals as more than just headline catalysts.
Butterfly's pipeline of large enterprise and medical school deals, bolstered by recent success in landing a top global health system for full deployment, points to accelerating penetration of handheld ultrasound solutions as healthcare systems shift toward more accessible, cost-effective, point-of-care diagnostics and supports forward-looking revenue growth as funding clarity returns.
See why 36 investors see Butterfly Network as 21% undervalued.
Result: Fair Value of $11.40 (UNDERVALUED)
Still, the bullish Butterfly Network story could crack if large enterprise deals take longer to close or if domestic software renewals remain weak.
Find out about the key risks to this Butterfly Network narrative.
Another View: Butterfly Network On Sales-Based Valuation
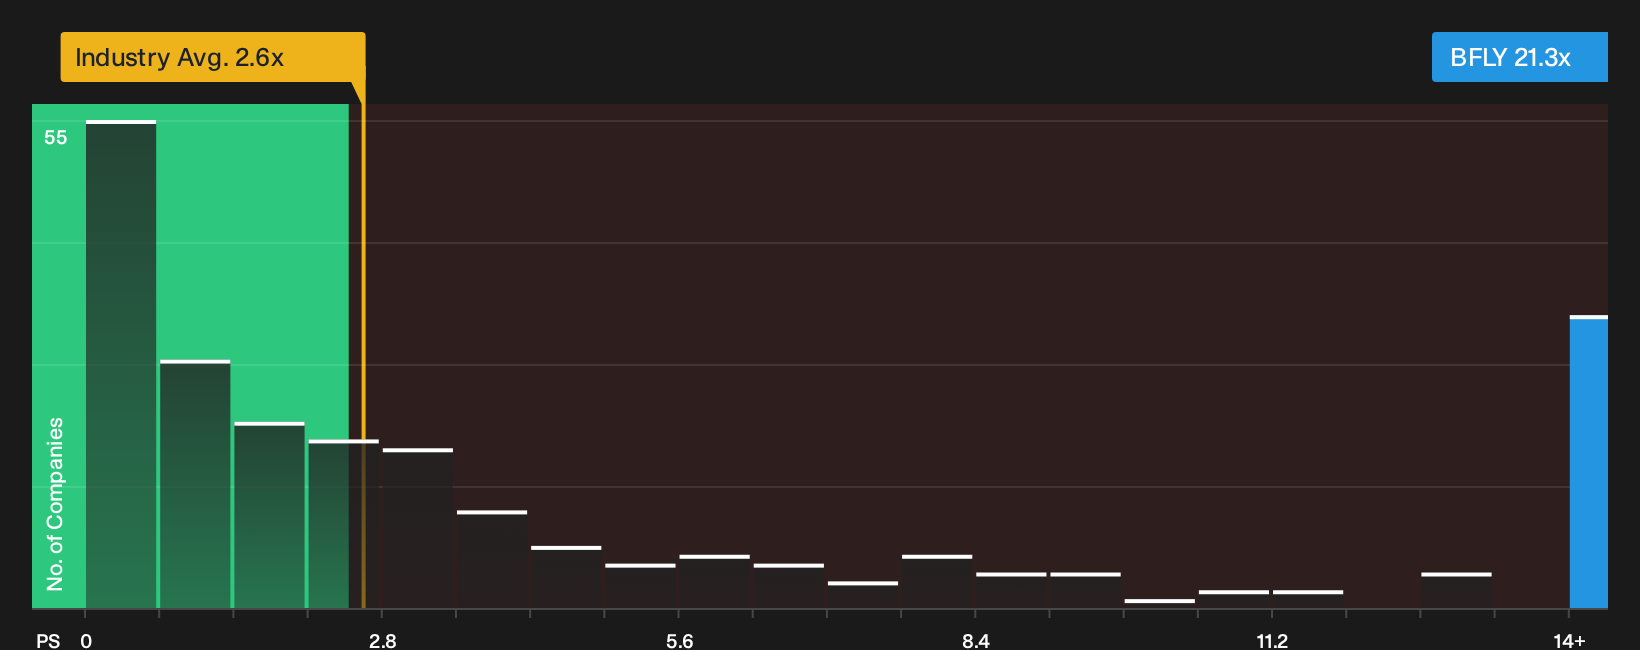
There is a catch. On a simple P/S lens, Butterfly Network trades at about 21.3x sales, while the US Medical Equipment group sits near 2.6x and peers average around 5.7x. The fair ratio model points to 6x. That gap signals rich expectations. Is the growth story strong enough to support this premium?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Butterfly Network’s valuation and sentiment make this a stock you need to judge on your own terms, so move quickly and review both the upbeat forecasts and the caution flags in detail through the 1 key reward and 3 important warning signs.
Looking for more Butterfly Network investment ideas?
If you like what you see in Butterfly Network but do not want to rely on a single stock, broaden your watchlist with a few focused stock shortlists that surface different strengths, then pressure test Butterfly against them.
- Chase value driven setups by scanning a curated pool of companies that screen as attractively priced and financially robust through the 31 high quality undervalued stocks.
- Target resilient balance sheets by comparing Butterfly to a list of solid balance sheet and fundamentals (25 results) that can help you stress test quality in tougher conditions.
- Hunt for under the radar potential by lining Butterfly up against a hand picked collection of 19 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com