


What Waters Investors Were Actually Arguing About
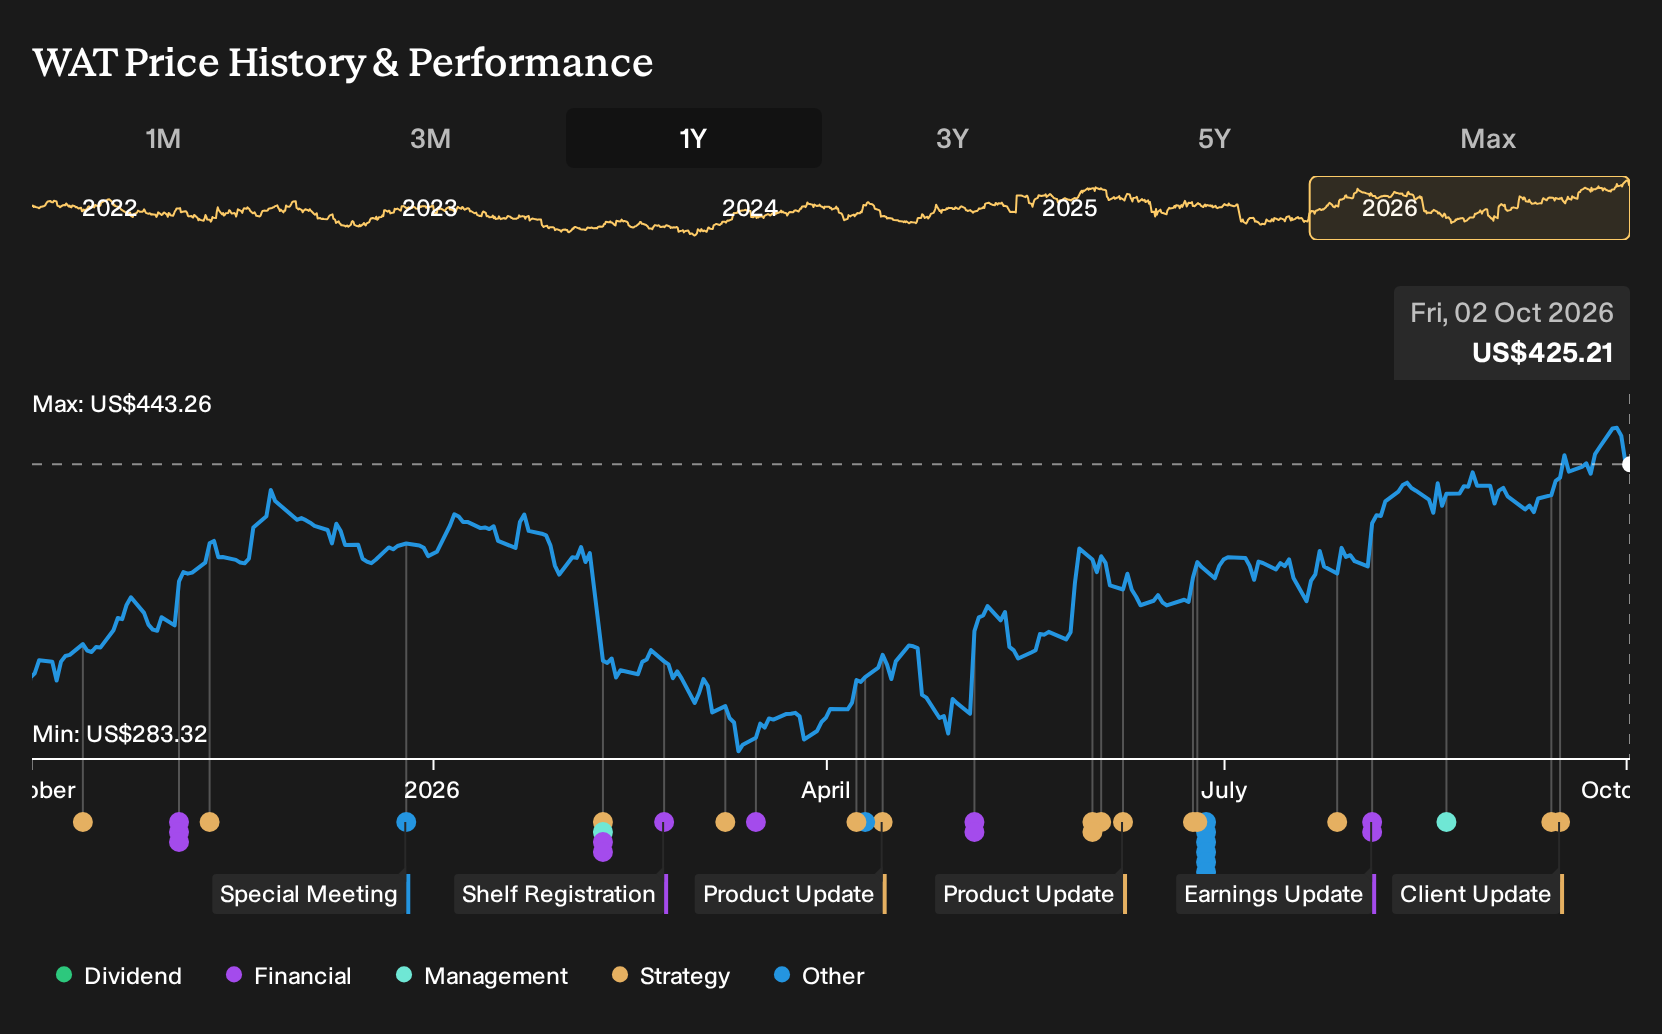
If you had bought Waters on 2 October 2025 and simply sat tight, the outcome might surprise you. Investors who held Waters over the past year are up 29.5%, including dividends. That result now sits alongside headlines about a large BD acquisition, raised guidance, and a recent quarter where revenue climbed but net income swung to a loss. If you were deciding back then, which mattered more, the promised synergies or the risk of margin strain?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Waters is not the only name tied to this theme. Zero in on 35 healthcare AI stocks and compare how each one is priced.
The Argument You Would Have Been Weighing Up On Waters
The shares cost US$322 at the start of the period, and Waters sat between two clear stories about what might come next.
The bullish narrative pinned Fair Value at US$347, assuming revenue would grow 6.4% a year and profit margins would reach 25.8%, helped by expected synergies from the planned BD Biosciences and Diagnostic Solutions deal.
The bearish script put Fair Value closer to US$300, assuming 5.9% annual revenue growth and a 25.9% margin while warning that acquisition integration problems and customer budget pressure could limit the benefit of that merger.
What The Results Changed For The Waters Story
The big development for Waters was the BD Biosciences and Diagnostic Solutions deal flowing through the accounts. Revenue moved from US$771 million in Q2 2025 to US$1.645b in Q2 2026, which lined up with the bullish focus on scale, while a swing from US$147 million profit to a US$136 million loss and net margin falling to -8.3% left the profitability part of that case unproven. The evidence cut both ways.
The key assumption that really mattered here was margin resilience during a large acquisition. When you assess another company, track net income and net margin after a big deal and compare them with the pre acquisition level that backed the original thesis.
What Today’s Waters Price Already Bakes In
Waters now trades at US$425 after a 29.5% gain over the past year. The selected Narrative sees Fair Value below that level and argues the current quote already reflects a lot of optimism about diagnostics expansion and broader healthcare demand.
The Narrative focuses on concerns about reliance on mature product lines, acquisition integration, and emerging market exposure. You would be asking what must keep going right for today’s price to hold, especially around delivering BD deal synergies without lasting pressure on margins and revenue stability.
"Emerging market exposure and integration risks from acquisitions could pressure revenue stability, margins, and delay expected synergies. Persistent weakness in key market segments, margin pressures, and acquisition integration risks threaten Waters' revenue growth, profit trajectory, and ability to achieve planned synergies."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking One Step Beyond Waters
Waters puts you close to drug discovery, testing, and complex diagnostics. You can also look at who turns successful science into treatments.
Across healthcare, one group sinks heavy spending into new medicines and devices. It relies on approvals and trial programs to keep that pipeline moving.
Those therapies often tackle harder diseases, where treatment length and pricing can matter. The same operator is also moving deeper into heart, surgical, and vision procedures.
If your thesis on Waters leans on growing clinical demand, that adjacent effort might deserve attention. The unresolved piece is how that broad platform manages pricing pressure, legal exposure, and major acquisitions from here.
That argument has a Narrative and a number behind it. → See the company one Narrative values 25% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com