


AI Product Launches Could Be A Game Changer For NetScout Systems (NTCT)
- NetScout Systems recently introduced nGenius Copilot, an AI-powered conversational extension to nGeniusONE, and added Model Context Protocol connectivity to its Omnis AI Insights platform, both aimed at turning Smart Data into more accessible operational intelligence across complex hybrid environments.
- These launches push more of NetScout Systems’ packet-derived Smart Data directly into everyday workflows through natural language queries and MCP-linked AI assistants, which could influence adoption patterns, product mix, and how enterprises and service providers allocate budgets across observability, service assurance, and security tools.
- We will now examine how NetScout Systems’ AI-focused nGenius Copilot launch could affect the company’s existing investment narrative and risk balance.
Scan how NetScout Systems' AI push compares with peers by reviewing a curated group of 90 AI infrastructure stocks that power similar observability, networking, and data-center workloads.
NetScout Systems Investment Narrative Recap
To own NetScout Systems, you need to believe its mix of service assurance and cybersecurity can keep pulling in steady enterprise and government demand even as networks get more complex and cloud heavy. The key near term swing factor is how well management turns AI features into real product uptake without eroding its existing high quality earnings profile.
The biggest risk is that slower forecast earnings and modest revenue growth could face more pressure from cloud native tools and stack consolidation, which could weigh on legacy offerings. The recent nGenius Copilot and Omnis AI updates look directionally supportive, but on their own they do not fundamentally change that risk reward balance yet.
The nGenius Copilot release is the clearest operational link to those AI driven catalysts. It pushes NetScout Systems’ Smart Data into everyday workflows through natural language queries, which can make its existing deployments more useful for a broader set of users. That fits the story of extracting more value from the current customer base rather than relying solely on new logo wins.
For you as an investor, the key issue is execution. Copilot and MCP enabled Omnis AI Insights give the firm more ways to tie into tools like Splunk, ELK, Datadog, ServiceNow, and Dynatrace. If customers steadily attach these AI options to current platforms, that supports the thesis of higher contract values and stickier observability and security spend, while still leaving the structural risk from cloud migration in view.
NetScout Systems' current consensus narrative points to revenues of $954.2 million and earnings of $122.2 million by 2029, based on 3.5% yearly revenue growth and an increase in earnings of about $26.7 million from $95.5 million today.
Uncover why NetScout Systems' fair value is essentially aligned with its current price.
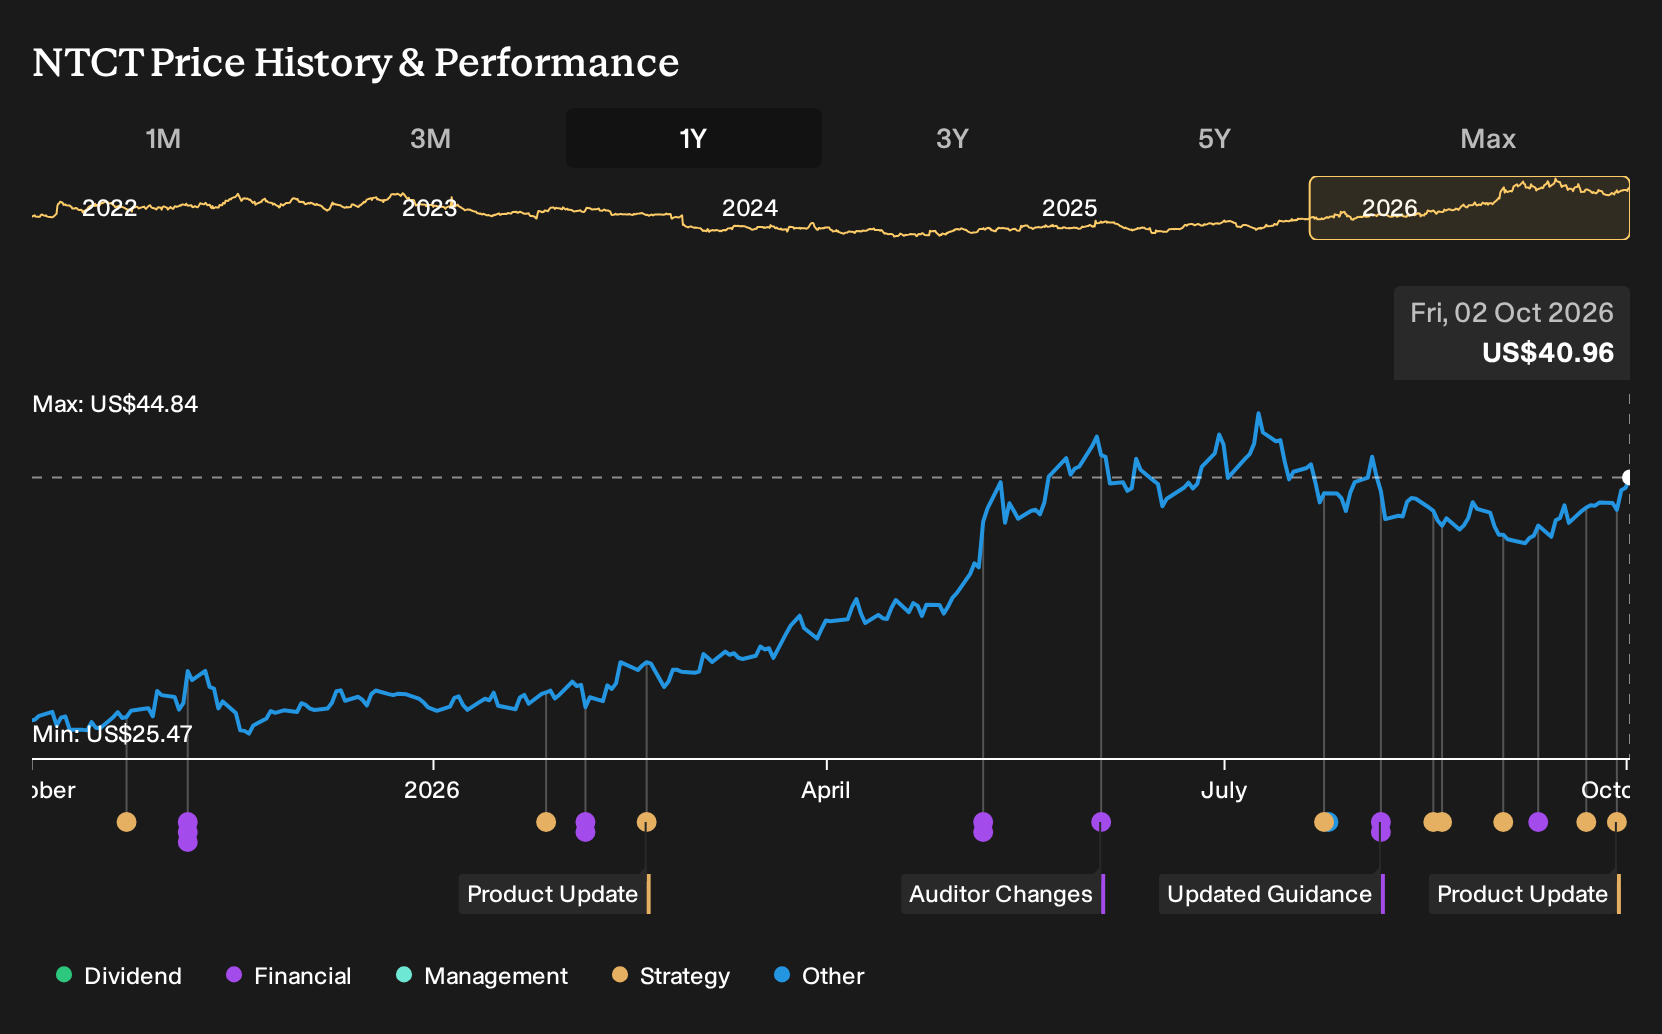
Exploring Other Perspectives
Some of the most optimistic analysts focus on a different angle. They lean into NetScout Systems’ AI exposure and, even before this Copilot news, were working off projections of revenue reaching about $981.1 million and earnings near $123.2 million by 2029. That is a more upbeat story. Views like this can shift. Explore several perspectives before you decide where you stand.
Explore 4 other NetScout Systems fair value estimates, including one that indicates there could be as much as 42% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NetScout Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for NetScout Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NetScout Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond NetScout Systems?
If the NetScout Systems story has sharpened your thinking about AI infrastructure and network visibility, it can help to compare it with a wider set of businesses that fit different risk and income profiles. The Simply Wall St Screener is built for exactly that kind of side by side work.
- For investors who want income to do more of the heavy lifting, scan a curated set of higher yielding opportunities through 7 dividend fortresses.
- If capital preservation and steadier fundamentals matter most to you right now, filter for companies that score well on balance sheet strength using the 31 resilient stocks with low risk scores.
- When you are hunting for less crowded opportunities with solid underpinnings, widen the search to a 19 high quality undiscovered gems that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com