


Why Siltronic Stock Is In Focus After Its Share Sale And Underwriter Change
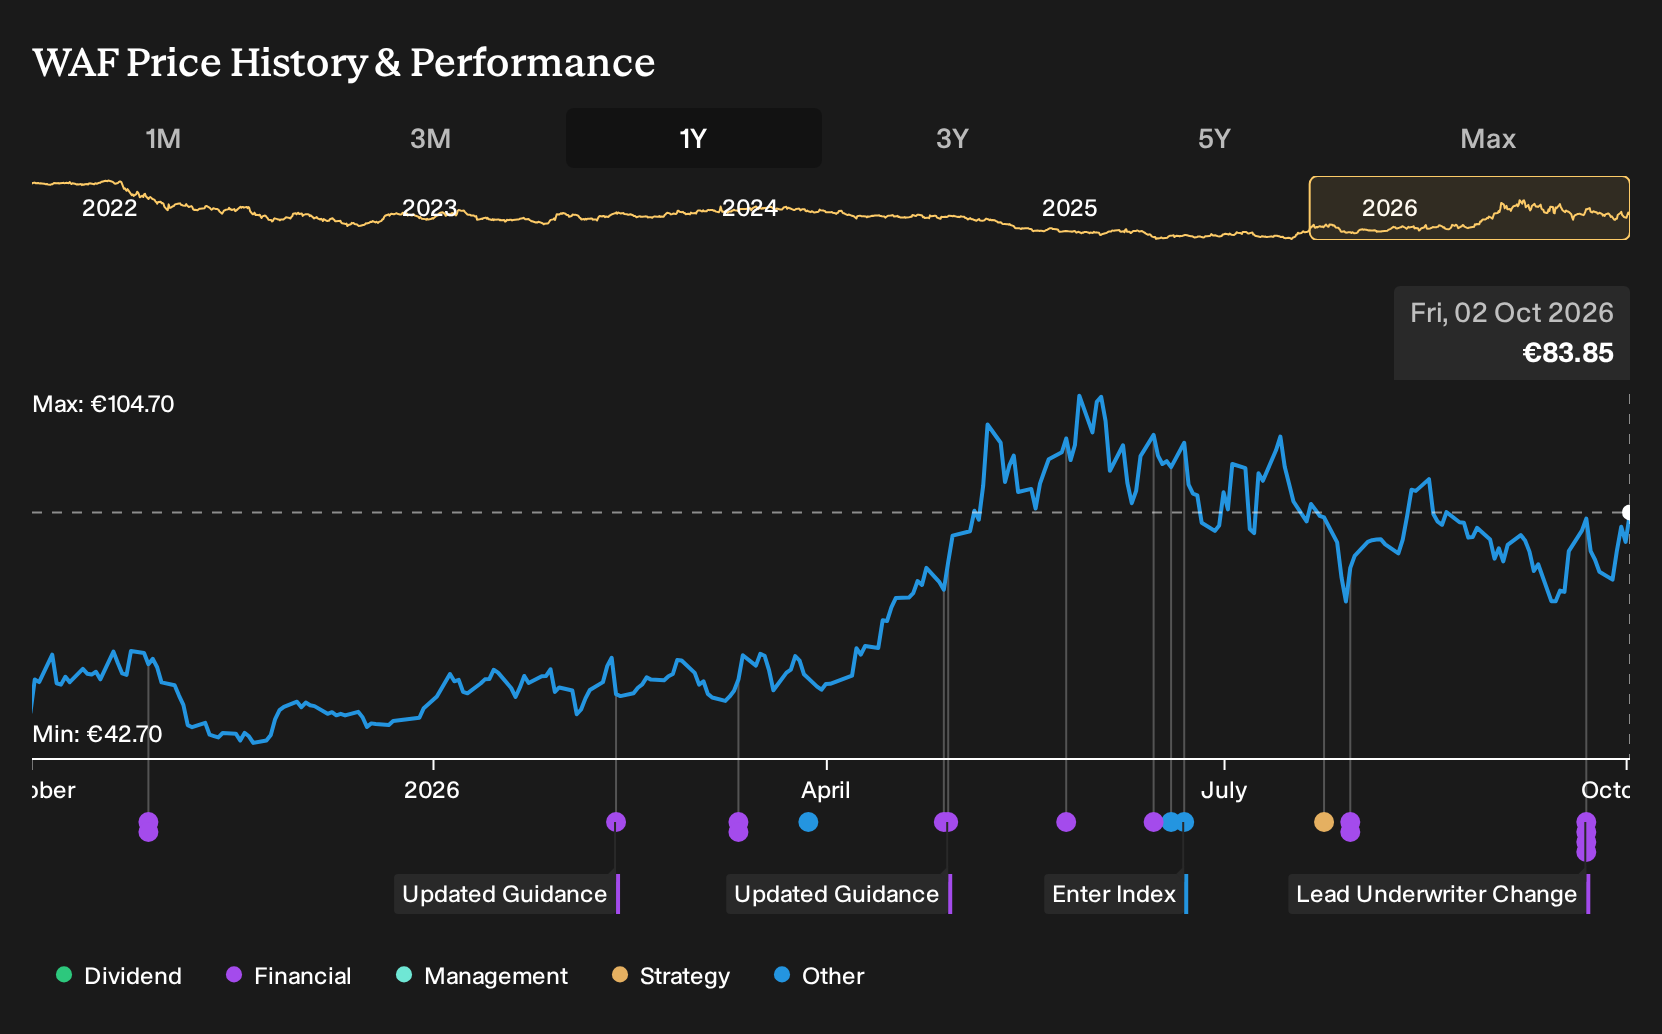
- Siltronic AG completed a €169.95 million follow-on equity offering of 2,200,000 ordinary registered shares at €77.25 per share, supported by BofA Securities and Deutsche Bank AG as co-lead underwriters.
- The capital raise increases financial resources for Siltronic as it manages high capital expenditure, inventory overhang and competitive pressure in advanced wafer production.
- We will now assess how Siltronic's fresh equity raise and new co-lead underwriters could reshape the longer term investment narrative.
Compare Siltronic's fresh capital raise with peers that face significant investment needs and pressure on returns by scanning our curated list of list of solid balance sheet and fundamentals (206 results)
Siltronic Investment Narrative Recap
To own Siltronic, you need to believe that hyperpure silicon wafers remain essential as AI, data center and automotive chips keep getting more complex, and that the FabNext capacity can be absorbed once industry inventories ease. The fresh equity does not change that thesis. It mostly reinforces the focus on advanced 300mm wafers and long term supply agreements.
The key near term catalyst still sits in a cleaner demand picture as customers work through excess stock and orders normalise against Siltronic's expanded footprint. The biggest risk remains a combination of high capital expenditure, weaker free cash flow and intense pricing pressure from international competitors.
The completed €169.95 million follow on equity offering is the central development to focus on. Extra equity capital can help Siltronic handle FabNext related spending, potential FX headwinds and any slower than expected recovery in wafer volumes without relying solely on higher risk funding sources or additional borrowing.
With BofA Securities and Deutsche Bank AG as co lead underwriters, execution risk around the transaction itself appears limited. For you as a shareholder, the more practical questions are how efficiently this cash is deployed, whether it supports the shift toward higher value wafers and how it interacts with future free cash flow and debt levels.
Siltronic's current loss of €192.8 million is set against analyst consensus earnings of €64.2 million by 2029. This implies an earnings swing of about €257 million and revenue growth assumptions of 12.3% per year on the path to a forecast €1.8 billion top line in that same year.
Uncover why Siltronic's fair value indicates a 13% potential upside to its current price, which could close sooner than many investors expect.
Exploring Other Perspectives
One alternate view highlights geopolitical risk for Siltronic. The most cautious analysts worried that restricted access to key regions could limit revenue to about €1.7b by 2029, yet still saw scope for earnings near €267.1 million. Those estimates predate the new equity deal, so opinions may evolve and it can be useful to explore several scenarios yourself.
Explore 6 other Siltronic fair value estimates, including one that suggests as much as 24% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Siltronic research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Siltronic. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Siltronic's overall financial health at a glance.
Looking for more Siltronic-sized investment ideas?
If assessing Siltronic has sharpened your process, it can be useful to line it up against other businesses with different balance sheet strengths, income profiles and risk levels using the Simply Wall St Screener.
- For investors who care most about financial resilience and clean balance sheets, start with a list of solid balance sheet and fundamentals (206 results) that already meet strict fundamentals criteria.
- If you are hunting for companies that the market may not be fully pricing, review a curated set of 192 high quality undervalued stocks that combine quality traits with potential mispricing signals.
- Anyone focused on steady income streams can benchmark Siltronic against a group of 168 dividend fortresses that pair higher yields with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com