


DoorDash (DASH) Jumped, What Is Behind The Move?
DoorDash (DASH) just packed a lot into one day. Expanded retail partnerships, a new restaurant operating platform, drones for deliveries, fresh AI tools, and corporate integrations all point to a broader ecosystem play.
DoorDash has packed these launches into a period when momentum has been mixed, with the share price at US$189.15 after a 1-day share price return of 3.83% but a 30-day share price return down 10.66%, and a 1-year total shareholder return down 30.26% against a much stronger 3-year total shareholder return of about 1.5x.
Scan beyond DoorDash and see how other platform players with ecosystem and AI angles are setting up for their next move with the curated 19 high quality undiscovered gems.
After a sharp one-day pop but a weak year on the chart, DoorDash now asks a simple question of you. Does today’s price still leave enough upside to justify the hit if the story cools?
Most Popular Narrative: 26% Undervalued
On the most followed view, DoorDash is priced below an estimated fair value of $256.26, compared with the last close at $189.15. This puts the latest product blitz in the context of a longer earnings story built on higher margin revenue lines.
Record performance of DashPass and Wolt+ subscriptions, including a recent period where DoorDash added more paid DashPass subscribers in one year than in the prior two years combined, supports a growing base of recurring, higher margin revenue and higher gross profit per MAU that can compound into earnings growth.
See why 78 investors see DoorDash as 26% undervalued.
Result: Fair Value of $256.26 (UNDERVALUED)
Still, if DoorDash faces tougher regulation on worker pay or prolonged spending to support dashers, the higher margin story that the market is watching could stall.
Find out about the key risks to this DoorDash narrative.
Another View On DoorDash Using The P/E Ratio
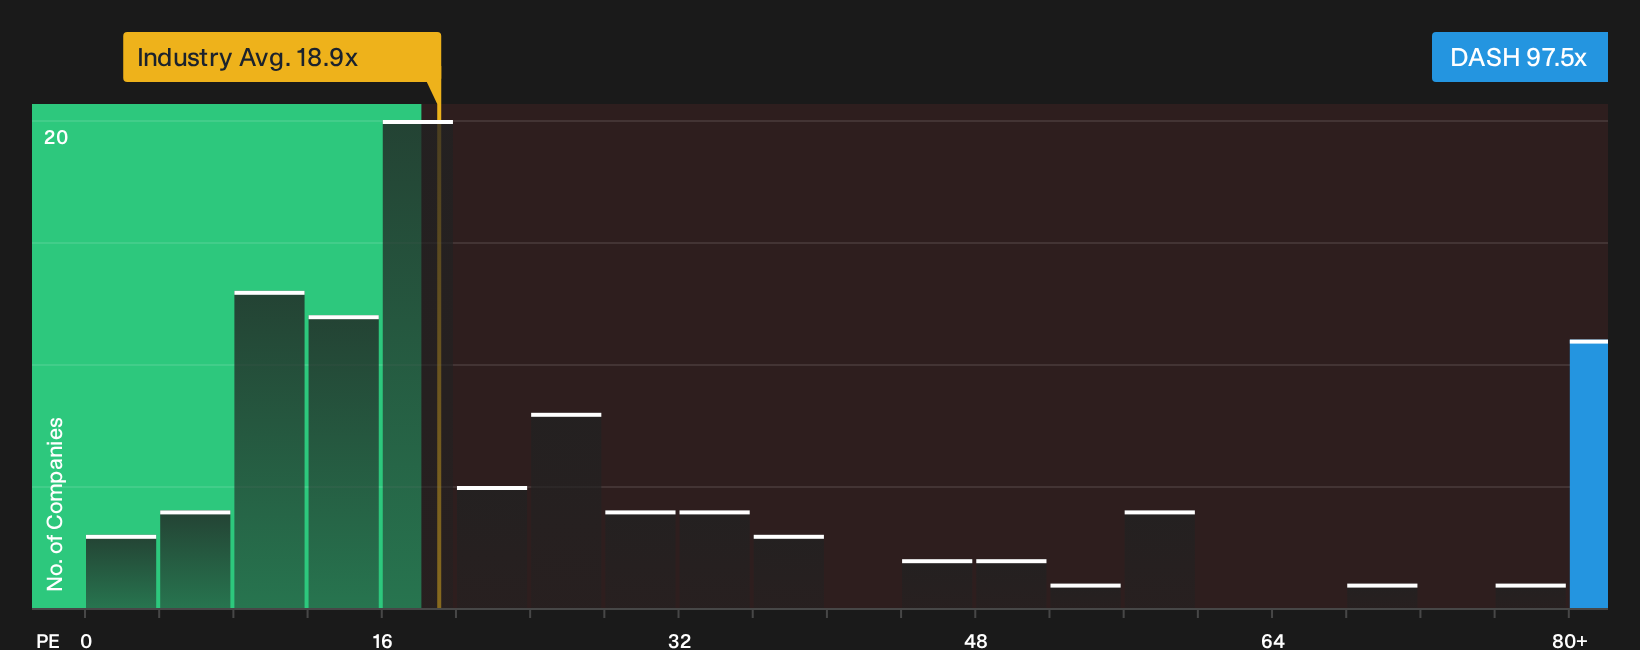
The first story around DoorDash leans on cash flow and long term earnings power. A simple price tag check tells something different. The stock trades on a P/E of 97.5x, while the fair ratio for the business is put at 46.5x, the US Hospitality group sits at 18.9x, and peers average 29.4x.
In plain terms, you are looking at a price that is more than double the fair ratio and far above both sector and peer levels. This raises the risk that any hiccup in the growth path could hit the multiple faster than the cash flow narrative adjusts.
That mismatch is exactly what some investors focus on when they stress test an earnings driven valuation. It can be useful to see what the numbers say in a full valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on DoorDash can feel messy, so move fast, review the data for yourself, and carefully weigh the 4 key rewards and 1 important warning sign.
Looking For More Ideas Beyond DoorDash?
If DoorDash has you rethinking where capital works hardest, do not stop here. Use focused stock lists to spot opportunities before the wider market catches on.
- Target stability and income by scanning companies built around strong payouts and resilient cash flows with the 7 dividend fortresses.
- Hunt for mispriced quality where fundamentals and price still feel out of sync using the 31 high quality undervalued stocks.
- Prioritize resilience and sleep-better-at-night holdings by filtering for businesses that pass tough financial strength checks through the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com