


How Investors May Respond To Schneider Electric (ENXTPA:SU) Software Defined Switchgear Launch
- In late September 2026, Schneider Electric announced multiple data center focused products and alliances, including software defined MV switchgear, an AI ready coolant distribution unit, and a Generator to Chip power delivery model developed with Wärtsilä and Stanley Consultants.
- These moves push Schneider Electric deeper into software led, AI oriented infrastructure and lifecycle services, which directly affects capex intensity, mix of recurring revenue, and execution complexity for large data center and utility clients.
- We will now see how Schneider Electric's investment narrative could be influenced by the software defined MV switchgear launch.
Scan Schneider Electric's AI driven grid and data center push alongside a curated group of power and infrastructure players in the 40 power grid technology and infrastructure stocks.
Schneider Electric Investment Narrative Recap
To own Schneider Electric, an investor needs to believe its mix of energy management, data centers and software can keep turning a strong project backlog into sustained earnings growth, even as competition and capex demands stay high. The latest AI focused power and cooling launches speak directly to that data center pipeline, but do not fundamentally change the short term story.
Near term, the key swing factor remains how efficiently Schneider Electric converts this heavier investment cycle and higher debt load into cash, without letting Systems mix and AVEVA SaaS transition drag margins. The biggest risk still sits in prolonged margin pressure and execution strain if orders stay complex while Industrial Automation and weaker regions struggle.
The Generator to Chip alliance with Wärtsilä and Stanley Consultants looks most directly tied to the AI ready switchgear and liquid cooling push. It tries to package onsite generation, electrical architecture and lifecycle services into one coordinated offer, which aligns neatly with Schneider Electric’s tilt toward software led, recurring service models around the powertrain.
For catalysts, this bundled approach gives data center developers one counterpart for generation, distribution and digital monitoring. This could shorten project timelines and support Schneider Electric’s share of AI infrastructure spend if deployments scale. The flip side is execution risk, because coordinating multiple partners across engineering, permitting and commissioning adds complexity. Any delays or cost overruns would feed straight into the existing concerns around margins and cash conversion.
What The Software Defined Switchgear Implies For Consensus Expectations
Schneider Electric's software defined medium voltage switchgear launches sit against a consensus narrative that already bakes in fairly ambitious profit targets on the back of data center demand, grid upgrades and more digital services. Analysts currently factor in revenue growth of 10.3% a year over the next three years, alongside profit margins moving from 11.3% today to 14.7% on their models. That backdrop matters because any lift or drag from AI ready switchgear, liquid cooling or Generator to Chip offerings filters into earnings expectations that are already stretching the balance between higher complexity and tighter capital discipline.
On earnings, analysts estimate Schneider Electric generates about €4.7b today and reaches €8.3b by 2029. That implies an increase of roughly €3.6b in profit over the period. Consensus is not uniform, with the most optimistic forecast at €9.2b and the most cautious at €7.3b, which gives a sense of how differently people are scoring the risk that more software defined hardware and lifecycle contracts pressure delivery and working capital. For a retail investor, that spread can be a useful shorthand for execution uncertainty rather than a precise prediction of where profits will land.
Schneider Electric's narrative projects €56.4b revenue and €8.3b earnings by 2029. This assumes 10.3% yearly revenue growth and an earnings increase of about €3.6b from €4.7b today.
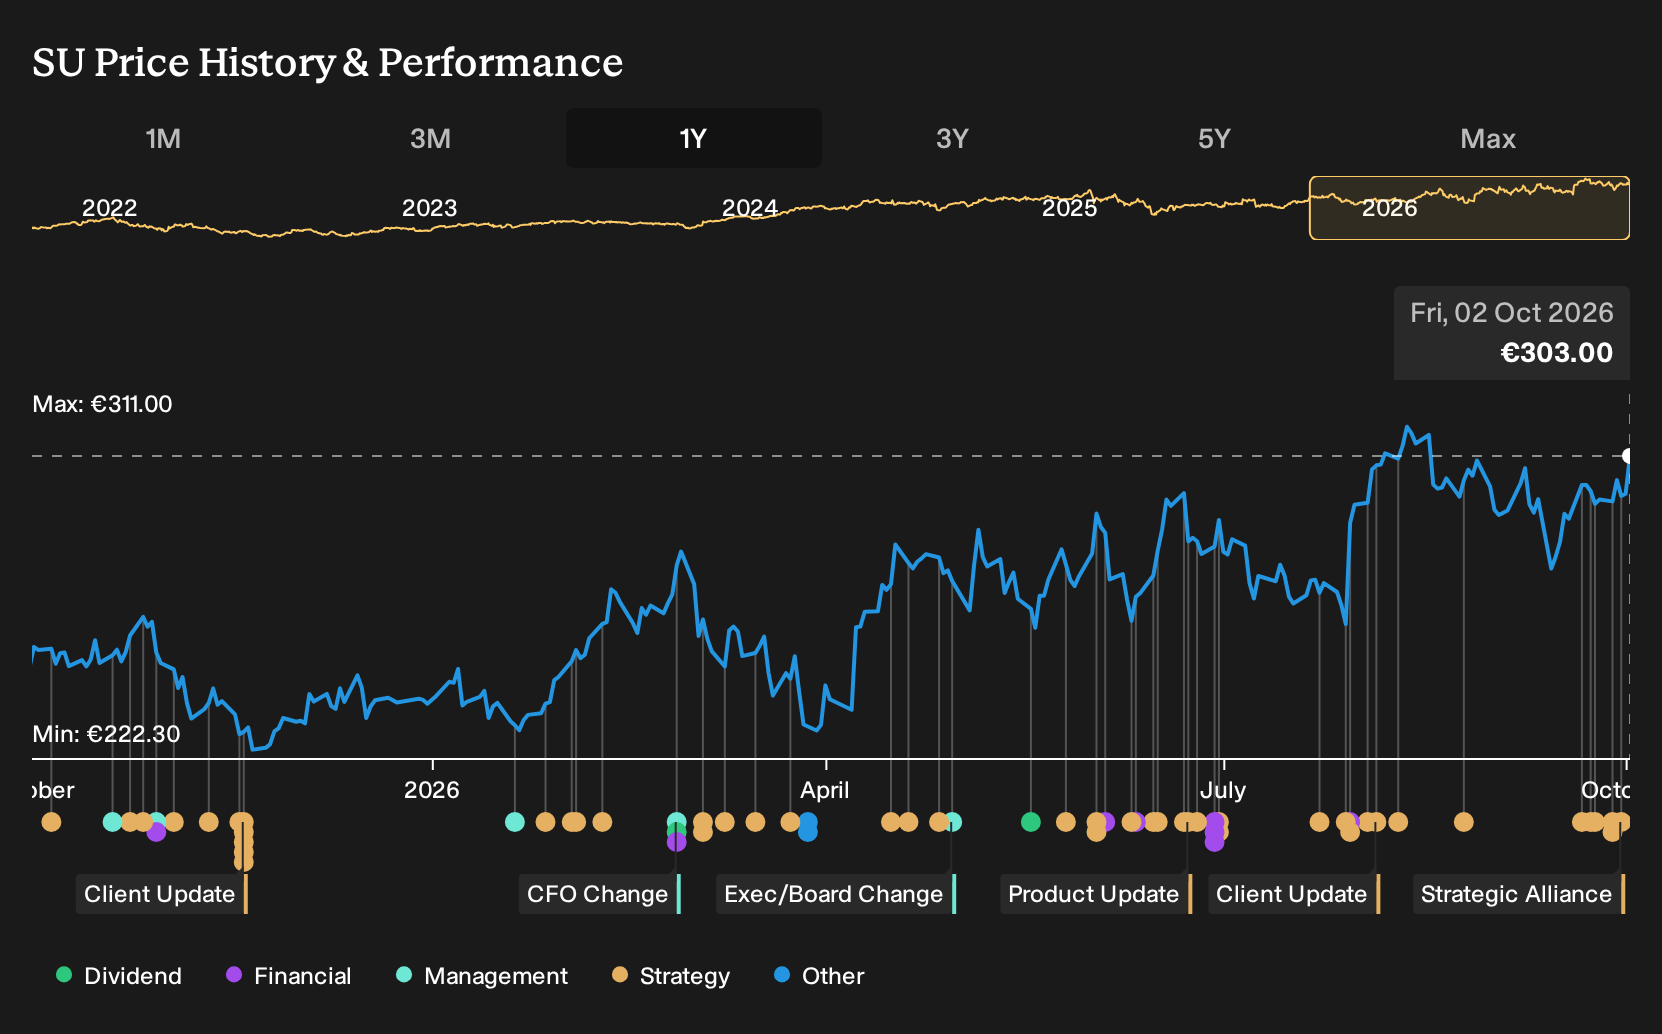
Valuation work ties these operational forecasts into a P/E reset. The current share price of €302.25 sits near an analyst consensus target of €325.04, with the bullish end at €370.0 and the bearish end at €262.0. To line up with that central case, you would need to be comfortable with Schneider Electric trading on a P/E of 28.9x on those 2029 earnings, down from 35.9x today and below the cited 33.8x for the wider GB Electrical industry. AI leaning switchgear and services therefore need to support not just higher earnings, but also a gradual derating as the business mix skews further into long duration projects and subscription like contracts.
For an investor watching the software defined MV switchgear launch, the question becomes how much confidence to place in that 10.3% annual revenue assumption and the move from 11.3% to 14.7% margins while Systems remain a large share of the mix. If AI heavy data center and grid wins arrive with complex engineering scopes, longer acceptance cycles or more aggressive service guarantees, cash conversion could trail earnings and make that margin journey bumpier. On the other hand, if Schneider Electric can standardise these offerings and push more of the value into software, monitoring platforms and recurring support, the same consensus path looks more achievable without leaning entirely on price or volume.
Uncover why Schneider Electric's fair value indicates a 7% potential upside to its current price before this discount closes.
Exploring Other Perspectives
The Simply Wall St Community adds four fair value views for Schneider Electric, stretching from about €218.94 to €379.32. That is a wide span. You see everything from deep discount to rich premium. Set those crowd estimates against the Generator to Chip push and AI ready grid products, then explore how sharply opinions can diverge.
Explore 3 other Schneider Electric fair value estimates, including one that suggests as much as 25% potential increase from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Schneider Electric research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Schneider Electric. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Schneider Electric's overall financial health at a glance.
Looking For More Investment Ideas Beyond Schneider Electric?
Once you have formed a view on Schneider Electric, it can help to set that thesis alongside other opportunities with different risk profiles and balance sheet strengths. The Simply Wall St Screener lets you do that quickly by filtering for specific traits that match how you like to invest.
- For investors who want potential mispricing backed by fundamentals, scan a 192 high quality undervalued stocks that combine solid cash generation with quality balance sheets.
- If capital preservation comes first, focus on resilience and financial stability by reviewing a 227 resilient stocks with low risk scores that score well on volatility and business risk.
- Those hunting for future leaders before they hit the headlines can comb through a 615 high quality undiscovered gems that already show healthy fundamentals but low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com