


Will Wafer ID Launch Change Cognex's (CGNX) Narrative
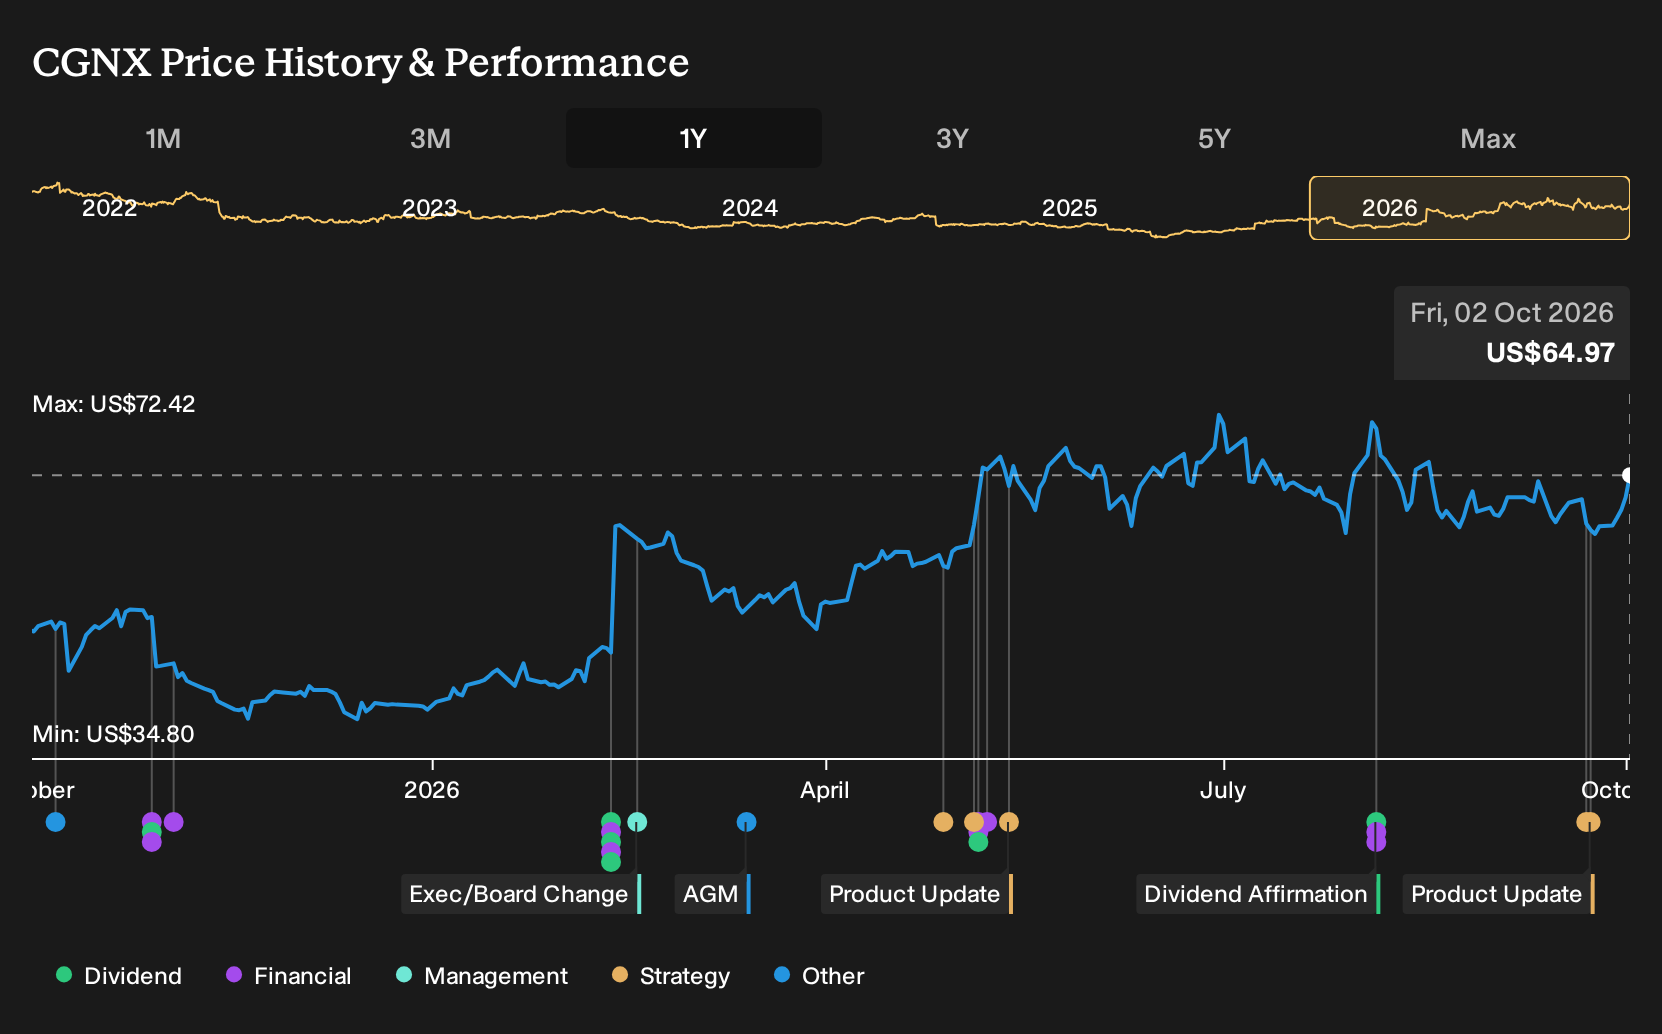
- Cognex recently introduced the In-Sight 1750 Series, a next-generation wafer and panel identification system aimed at improving traceability and maintaining throughput in complex semiconductor production.
- The product is built for drop-in upgrades from the In-Sight 1740, which can reduce engineering friction and accelerate adoption across existing semiconductor lines.
- We will now examine how Cognex's broader investment narrative could be affected by the In-Sight 1750's AI-driven wafer traceability focus.
Scan beyond Cognex and this wafer-traceability story by reviewing a curated group of 89 robotics and automation stocks that are pushing automation deeper into semiconductor and factory floors.
Cognex Investment Narrative Recap
The big picture for Cognex is simple. You need to believe that demand for AI-powered vision in factories and warehouses keeps expanding and that management can convert that into higher quality earnings without sacrificing margins to cheaper rivals. The In-Sight 1750 supports that story operationally but does not fundamentally change the near term focus on scaling OneVision and newer verticals.
The most important short term swing factor still looks like how Cognex handles pricing pressure, memory cost inflation and the RealSense integration while aiming for high 20s to low 30s adjusted EBITDA margins. The 1750 launch helps execution credibility but does not remove the risk of hardware commoditization or integration drag.
The recent In-Sight 1750 launch is the announcement that lines up most cleanly with existing catalysts. It brings Cognex’s AI and imaging stack into a semiconductor use case that already matters to the machine vision portfolio, and it is explicitly designed as a drop in upgrade path for current 1740 users.
For you as an investor, the operational question is whether products like the 1750 can reinforce the push toward higher value AI systems, support the effort to broaden the customer base, and help offset rising memory component costs. Execution on these deployments will sit alongside RealSense integration and cost discipline as key proof points.
Cognex's current analyst narrative points to US$1.5b in revenue and US$386.7 million in earnings by 2029, built on a 10.3% yearly revenue growth rate and an earnings increase of about US$211.9 million from US$174.8 million today.
Uncover why Cognex's fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on cyclical risk. The most bearish Cognex analysts worry that electronics and auto exposure keeps results choppy, even with products like the In‑Sight 1750 in the mix. They were only modeling about US$1.4b in 2029 revenue and US$339.3 million in earnings. This new launch could eventually reshape that gloomier script.
Explore 5 other Cognex fair value estimates, including one that suggests as much as 59% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cognex research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Cognex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cognex's overall financial health at a glance.
Looking For More Ideas Beyond Cognex?
If the Cognex story has sharpened your thinking about automation and AI, it can be useful to line it up against a wider field of potential opportunities. Use the Simply Wall St Screener to pressure test your thesis, compare quality, and spot companies that better fit your risk, income, or value preferences.
- If capital preservation is front of mind, start with a basket of companies that screen well on balance sheet strength using the list of solid balance sheet and fundamentals (25 results).
- If income is your priority, scan a focused set of businesses with resilient payouts through the 7 dividend fortresses.
- If you are hunting for mispriced quality, widen your watchlist with a hand picked 19 high quality undiscovered gems that may not be on every investor's radar yet.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com