


Avis Budget Group Fell 28% And The Hard Part May Be Starting Now
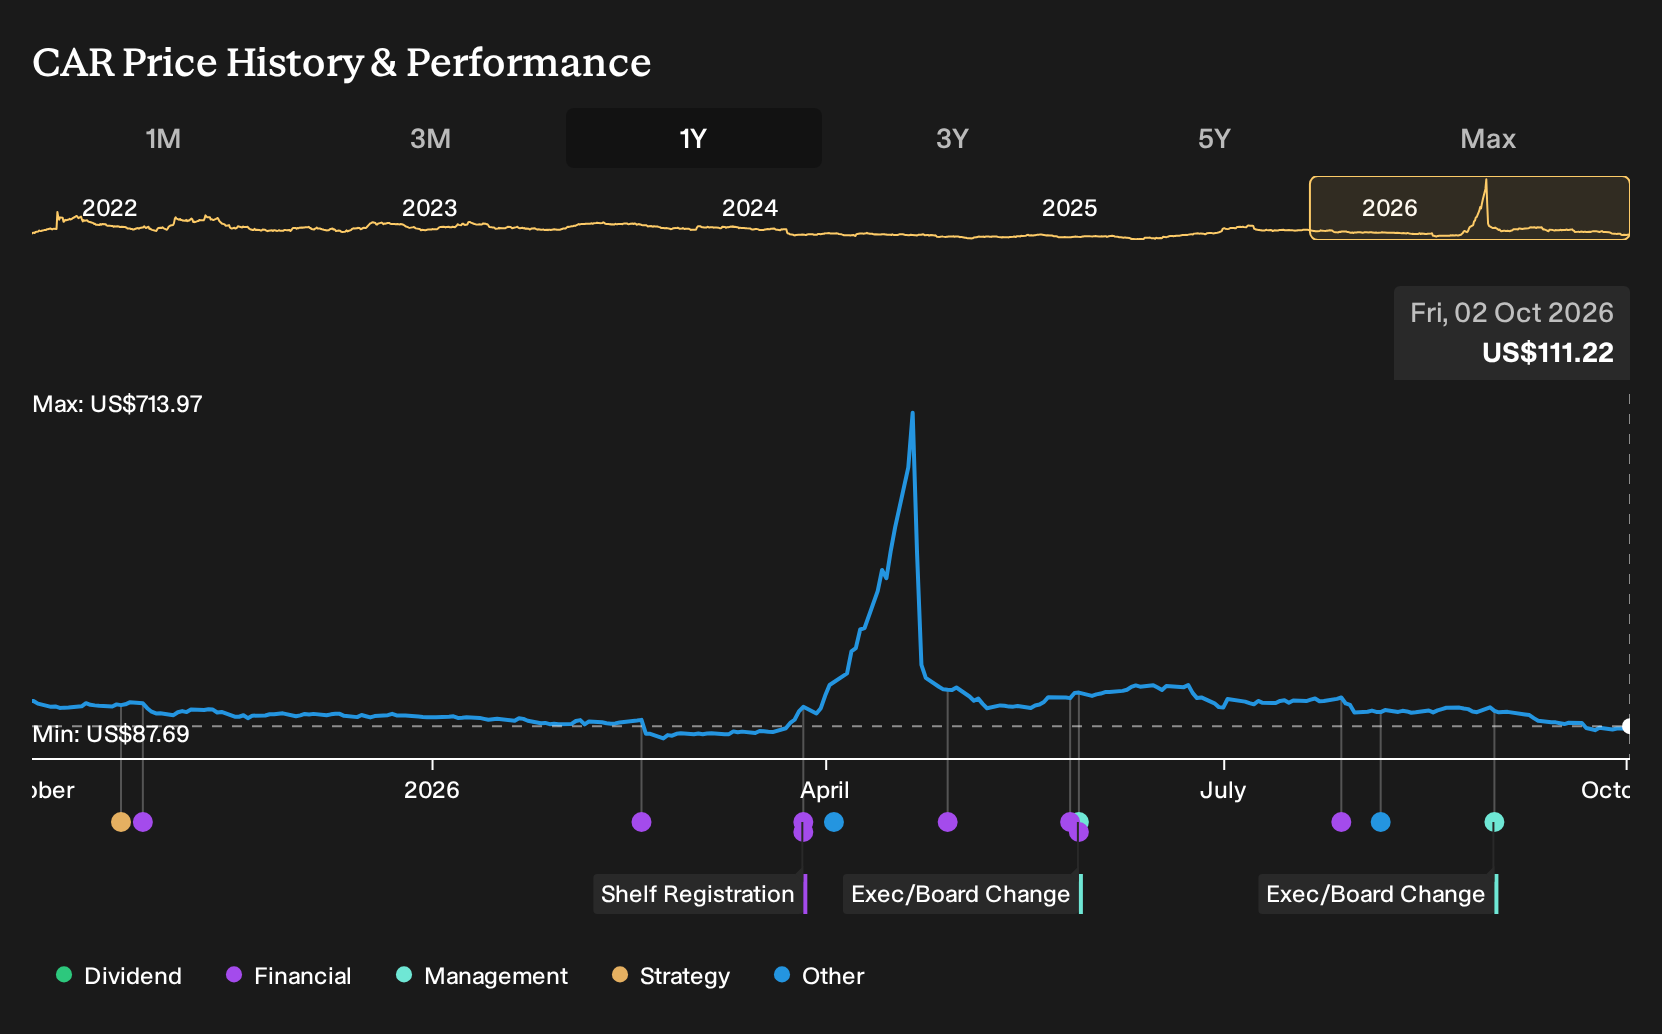
Avis Budget Group is back in the headlines after class action lawsuits alleged its shares were whipped around by a massive short squeeze and suspected manipulation tied to a major hedge fund holder. Investors who held Avis Budget Group over the past year are down 28.0%, including dividends. If you had committed capital on 2 October 2025, how much of that result reflects business reality versus trading mechanics, and what does that say about the next serious test of trust in this stock?
The easy part of this move is behind Avis Budget Group. Zero in on 31 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Weigh On Avis Budget Group
The shares cost US$160 at the start of the period, so anyone looking at Avis Budget Group then was really choosing between two sharply different stories about what that figure meant.
On the optimistic side, the bull Narrative pointed to a Fair Value of US$200. This was essentially the price implied if premium services and technology investments worked. That view leaned on assumptions that digital fleet management and offerings like Avis First would lift profit margins from a loss position to positive territory over time.
The more cautious bear Narrative suggested a Fair Value of US$148. This was the level implied if growth stayed modest and risks around alternative mobility and capital needs became more significant. This camp highlighted the possibility that rising competition and slow electric vehicle adoption could pressure future revenue and strain funding for fleet upgrades.
What The Evidence Did To The Avis Budget Group Argument
Avis Budget Group’s Q2 2026 report showed revenue at US$2,998m versus US$3,039m a year earlier, while net income excluding extras moved from US$4m to US$35m and net margin rose from 0.1% to 1.2%. That shift in profitability gave the premium and technology bull story some support, yet the top line softness kept the cautious thesis alive. The evidence pointed in both directions.
The lesson is simple. When a story leans on margin expansion, track net margin and absolute profit against that script, and treat any improvement without clear top line support as only a partial win.
What The Fall In Avis Budget Group Is Asking You To Believe Now
Avis Budget Group trades at US$111 after a 28.0% loss over the past year, while the selected Narrative’s Fair Value sits above the current price and frames that gap as justified by business execution rather than trading noise.
The Narrative focuses on premium offerings, technology-heavy fleet management and new mobility partnerships. A buyer today would need to believe those efforts genuinely turn cyclical rental demand into steadier, higher margin earnings power.
"Premium service and advanced fleet management strategies are expected to drive margin expansion, revenue growth, and lasting efficiency improvements. Strategic moves in autonomous mobility, digital infrastructure, and flexible rental models position the company for sustained relevance and steadier long-term earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Where Avis Budget Group’s Story Connects
Avis Budget Group is trying to turn car rental into a steadier, tech-driven service. You can look one step away from that push.
Riders increasingly expect to tap a phone, see a car arrive, and pay automatically. That habit creates pressure for smoother, more flexible transportation access in general.
Another business is chasing the same travelers from a different angle. It runs a platform that matches riders with cars, delivery drivers and freight capacity.
Its plan for driverless vehicles could reshape how those trips get supplied. If that effort changes who controls routes and pricing, Avis Budget Group’s next chapter may look very different beside it.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 70% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com