


Should Google Cloud AI Deal Require Action From BNP Paribas (ENXTPA:BNP) Investors?
- BNP Paribas and Google Cloud recently announced a five-year partnership to expand the bank's access to Google Cloud infrastructure and AI tools, including Gemini Enterprise and agentic AI, across functions such as credit memo preparation, sales, trading, research, and internal assistants like LLM@CIB and Nickel Assist.
- The collaboration highlights how BNP Paribas is leaning on external cloud and AI capabilities to reshape internal workflows, manage security and data governance in a multi-cloud setup, and potentially shift the cost and productivity profile of core corporate and retail banking activities.
- We will now examine how this AI-focused partnership with Google Cloud could influence BNP Paribas' broader investment narrative.
Scan how BNP Paribas is leaning into AI and then size up other financials wired for the same shift with a curated set of 90 AI infrastructure stocks.
BNP Paribas Investment Narrative Recap
To own BNP Paribas you need to be comfortable with a large, complex Eurozone lender that leans heavily on traditional retail and corporate banking while trying to squeeze more efficiency from digital tools and wealth management. The key near term swing factor remains execution on cost control and tech rollouts that can offset structurally pressured margins in core markets.
Recent leadership moves in wealth and property services look incremental for now, not thesis changing. The bigger near term risk still sits in regulatory pressure, funding mix and bad loan levels, especially as higher risk wholesale funding and a relatively high non performing loan ratio leave little room for operational missteps if the cycle weakens.
The partnership with Google Cloud is the clearest operational catalyst in this batch of announcements. It plugs directly into BNP Paribas’ push to harmonise technology across units, automate labour intensive work like credit memos and give front line staff AI tools that can, in theory, support productivity in sales, trading and client service.
If the bank executes well, these AI agents and internal assistants could help tackle some of the group’s structural challenges such as a high cost base and exposure to digital only competitors. The flip side is execution risk. Complex, agentic AI inside sensitive banking systems raises governance, security and integration hurdles that could slow rollouts or blunt the expected efficiency gains.
BNP Paribas' narrative projects €61.0b revenue and €16.4b earnings by 2029. This assumes 6.0% yearly revenue growth and an earnings increase of €3.6b from €12.8b today.
Uncover why BNP Paribas' fair value indicates a 30% potential upside to its current price that could narrow quickly.
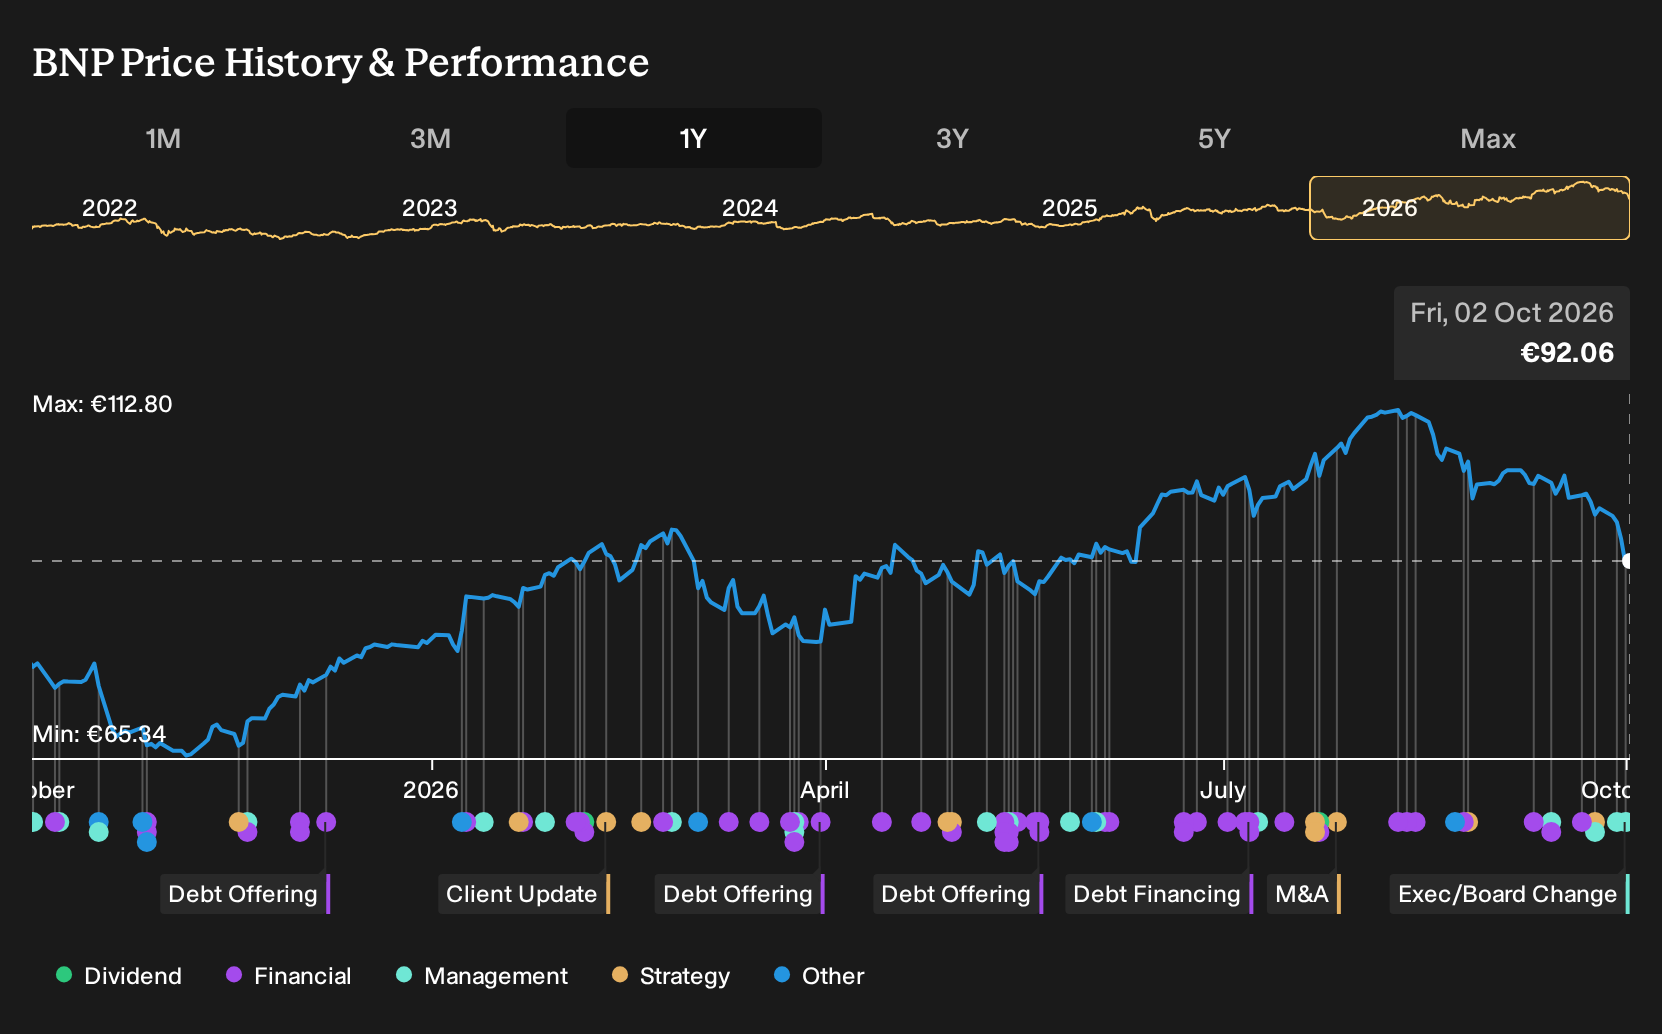
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about €106.5 and €120.0 per share, which already shows a tight but meaningful spread in expectations. Those views do not yet reflect recent management changes or the Google Cloud AI rollout at BNP Paribas, so you are seeing pre catalyst opinions. Use that gap to stress test your own scenario and compare where you sit against alternative viewpoints.
Explore 2 other BNP Paribas fair value estimates, including one that suggests it could be worth just €106.51.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your BNP Paribas research is our analysis highlighting 5 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for BNP Paribas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BNP Paribas' overall financial health at a glance.
Looking For More Ideas Beyond BNP Paribas?
Once you have a view on BNP Paribas, it can help to line it up against other opportunities that match your preferred style, whether that is value, income, or balance sheet strength.
- If you want potential mispricing with quality fundamentals, scan the 192 high quality undervalued stocks and see which companies line up with your return hurdles.
- If resilience matters more than excitement, check the 227 resilient stocks with low risk scores and compare how those businesses stack up on stability versus reward.
- If balance sheet strength is non negotiable for you, sort through the list of solid balance sheet and fundamentals (206 results) to find candidates that might complement or substitute your BNP Paribas view.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com