


Essex Property Trust (ESS), Why Is It Back In The Spotlight?
Essex Property Trust (ESS) has drawn fresh attention after recent trading left the stock about 10% lower over the past 3 months, prompting investors to reassess this large West Coast apartment REIT.
Over the past year, Essex Property Trust has delivered a 5.61% total shareholder return. Recent momentum has cooled, with the share price at $268.65 and shorter term moves, including a 30 day share price return down 3.57% and a 90 day share price return down 9.85%. These results point to a more cautious tone as investors reassess growth prospects and risk around West Coast multifamily real estate.See how Essex Property Trust compares with other income focused real estate plays by checking a curated list of 7 dividend fortresses.
After a 3 month slide and a share price near $268, Essex Property Trust now trades at a double digit discount to both analyst targets and intrinsic estimates. Is that gap signaling value, or something else?
Most Popular Narrative: 12% Undervalued
On the most followed view, Essex Property Trust screens undervalued, with a fair value of $304.23 against a last close of $268.65, which puts the current slide in a different light for long term holders focused on cash flow and asset backing.
Limited new multifamily supply in Essex Property Trust's core West Coast markets, including about 0.3% of stock in Northern California and deliveries in Seattle now below 1% of stock, continues to restrict competition for quality units and can support rent growth and occupancy, which feeds directly into revenue and same property NOI.
See why 11 investors see Essex Property Trust as 12% undervalued.
Result: Fair Value of $304.23 (UNDERVALUED)
Still, Essex Property Trust remains highly concentrated in West Coast markets, and softer Southern California performance with longer eviction timelines could keep portfolio wide margins under pressure.
Find out about the key risks to this Essex Property Trust narrative.
Another View On Essex Property Trust’s Valuation
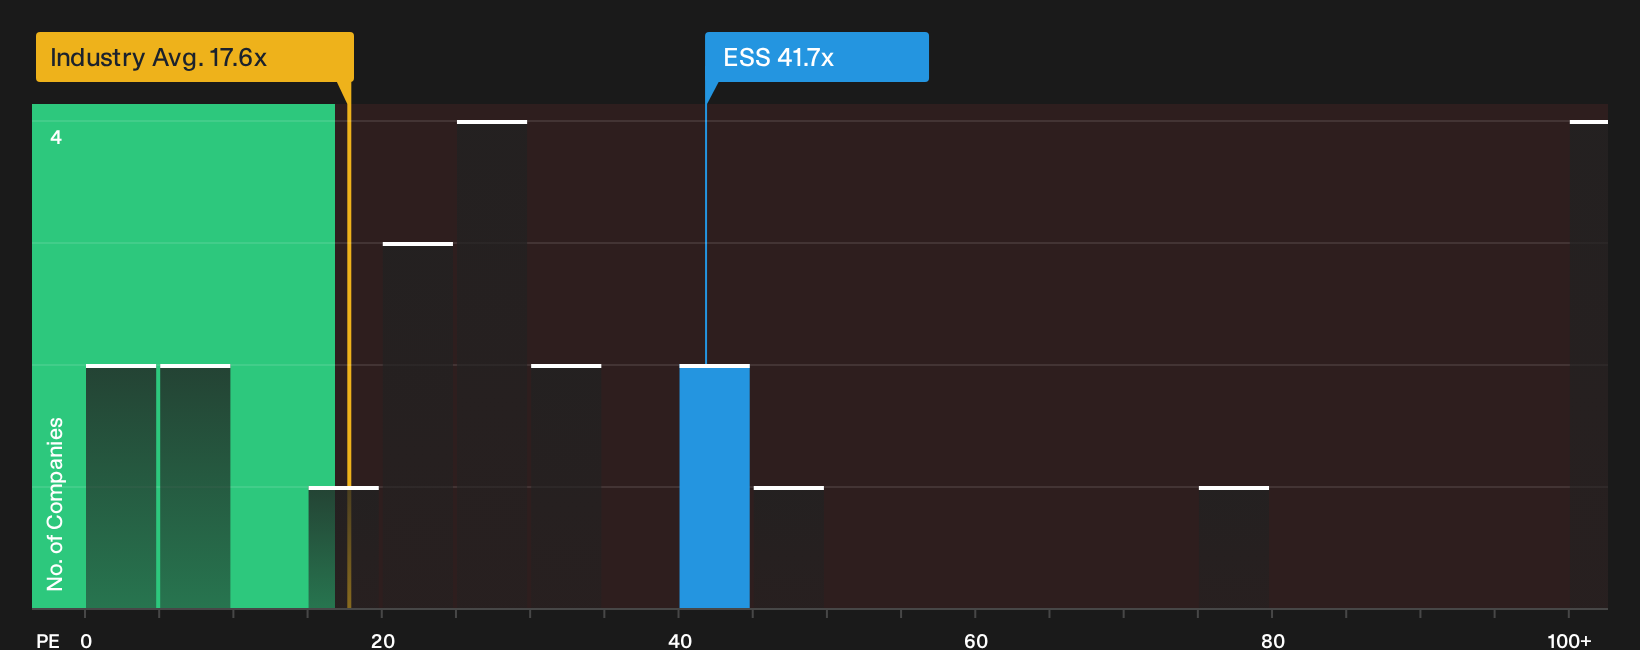
The first take presents Essex Property Trust as undervalued relative to its fair value, yet the earnings multiple tells a different story. ESS trades on a P/E of 41.7x, which is above the global Residential REITs average of 17.6x and a fair ratio of 32.4x. This difference points to meaningful valuation risk if sentiment cools.
See what the numbers indicate about this price gap by reviewing our valuation breakdown through the See what the numbers say about this price — find out in our valuation breakdown..
To put that into context, the current P/E is higher than both sector peers and the fair ratio that the market could move toward. As a result, any disappointment on earnings or growth could have an outsized effect on the share price relative to fundamentals.
Next Steps
Mixed messages on Essex Property Trust's valuation and risks can feel uncomfortable. Check the underlying data yourself and decide quickly whether the risk or reward matters more for your plan by reviewing the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Essex Property Trust?
If Essex Property Trust has you rethinking your watchlist, now is the moment to widen your search and line up your next candidates before others do.
- Target potential mispricings across the market by scanning our 31 high quality undervalued stocks that combine solid fundamentals with attractive entry points.
- Strengthen the defensive side of your portfolio by reviewing a list of solid balance sheet and fundamentals (25 results) that can help you sleep better through rough patches.
- Get ahead of the crowd by sifting through 19 high quality undiscovered gems that most investors are not watching yet but already show promising fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com