


Swisscom (SWX:SCMN) Could Be 11% Overvalued As It Drops From The SMI Index
Swisscom dropped from SMI index
Swisscom (SWX:SCMN) has been removed from the Swiss SMI Index, following an index reshuffle that can trigger forced trading by funds and ETFs that closely track this benchmark.
Over the past year, Swisscom has delivered a 13.28% total shareholder return, supported by a 10.36% year to date share price return. This points to steady momentum even though the stock slipped 2.74% on a 7 day share price basis as investors react to the index exit.
Compare Swisscom's index-related shakeup with other resilient telecoms and cash-generative companies using our hand picked screener of 227 resilient stocks with low risk scores.
Swisscom now trades above the average analyst price target, while an intrinsic value model suggests a wide discount. Where does a fair entry point actually sit after the index exit and recent gains?
Most Popular Narrative: 11% Overvalued
Swisscom last closed at CHF639, while the most followed narrative assigns a fair value of CHF574.59 based on a 4.12% discount rate. That gap puts the index exit in sharper context because it suggests sentiment has run ahead of the underlying cash flow assumptions.
Recent research on Swisscom shows a split view on the stock, with one group of analysts raising fair value estimates and another group becoming more cautious on execution risks and current valuation levels. The new CHF 620 price target sits within this range of opinions and highlights how views differ on Swisscom's ability to justify its current P/E and deliver against its revenue and margin assumptions.
See why 7 investors see Swisscom as 11% overvalued.
Analysts behind this framework are using a revenue trajectory that points to a gradual decline of 0.4% a year and profit margins near 11.6% over time. That mix keeps the earnings path growing, with forecasts of 7.3% annual profit expansion, but not at a pace that would usually attract premium growth pricing.
The same narrative runs a 4.12% discount rate through those projected earnings and cash flows to arrive at a fair value of about CHF574.59. With Swisscom at CHF639, that implies investors are paying up relative to those assumptions and effectively baking in either higher cash generation or a lower required return.
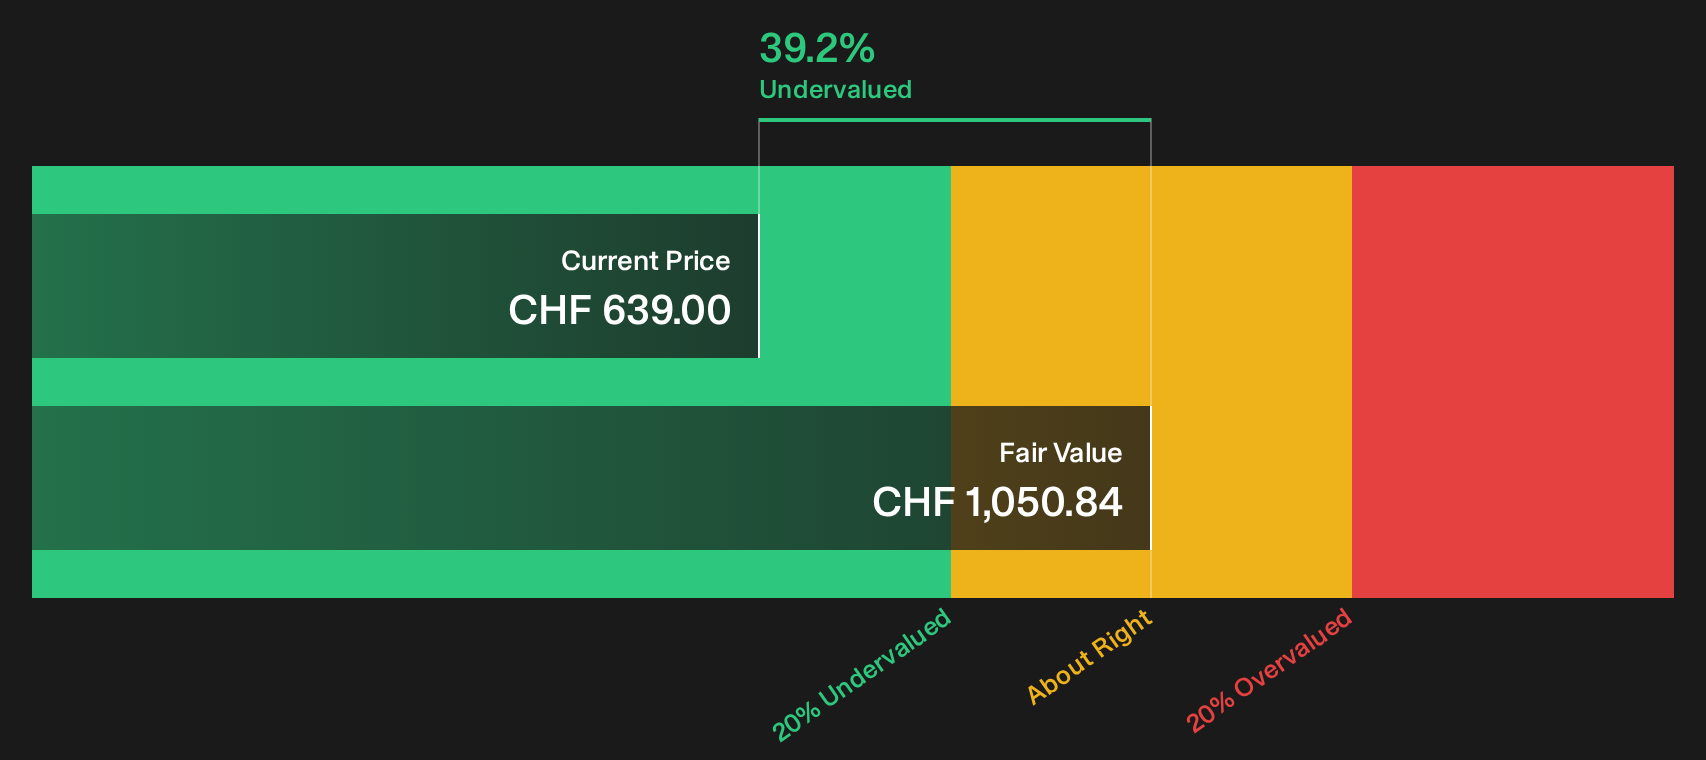
Against that backdrop, the SWS DCF model output in the statements data is more generous, with a future cash flow value estimate of CHF1,050.84 for Swisscom compared with the current CHF639 share price. The two approaches sit quite far apart, so it becomes important for you to decide which set of inputs you trust more, whether that is the more cautious revenue line in the narrative or the richer cash flow profile embedded in the DCF result.
Result: Fair Value of CHF574.59 (OVERVALUED)
Still, the narrative around Swisscom can unravel if Swiss service revenue pressure persists or if the Italian integration synergies arrive more slowly than expected.
Find out about the key risks to this Swisscom narrative.
Another Take on Swisscom's Valuation
The first narrative argues that Swisscom is about 11% overvalued at CHF639, yet our DCF model points in the opposite direction. On those cash flow assumptions, the SWS DCF model indicates Swisscom trades below an estimated value of CHF1,050.84, which frames the current price as a discount instead of a premium.
That is a wide gap between a CHF574.59 narrative fair value and a CHF1,050.84 DCF outcome. It leaves you with a simple but important question: Which set of inputs around revenue pressure, margins and required returns feels closer to how Swisscom actually operates over the long run?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Swisscom for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Swisscom's value can feel confusing, so move quickly from headline noise to your own judgment. Start with the 2 key rewards and 2 important warning signs.
Looking for more Swisscom sized investment ideas?
If Swisscom's mixed signals leave you curious, use that momentum and widen your watchlist with a few focused sets of opportunities.
- Target stronger upside potential by scanning 192 high quality undervalued stocks that pair appealing prices with solid fundamentals.
- Lock in potential income streams by reviewing 168 dividend fortresses that offer higher yields with an eye on resilience.
- Prioritise staying power by checking the list of solid balance sheet and fundamentals (206 results) so your next idea starts on firmer financial ground.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com