


Joby Aviation (JOBY) Nears FAA Certification After Flight Progress While Valuation Questions Build
Joby Aviation (JOBY) has drawn fresh attention after remotely operating its supervised autonomous J208 aircraft in Utah and flying eVTOL demonstration routes in Texas and Dubai, while moving toward final FAA type certification for commercial service.
Despite the operational progress, Joby Aviation’s share price has come under pressure, with the stock down 11.72% over 30 days and 33.30% over 90 days, and the 1-year total shareholder return declining 67.42%. This points to fading momentum as investors reassess execution risk and the timing of commercial ramp up.
Capitalize on the momentum around Joby Aviation by comparing it with hand-picked air mobility and transport peers screened for quality and valuation using the 31 high quality undervalued stocks.Joby Aviation has moved sharply out of favor, yet the gap between its US$5.95 share price and the US$10.68 analyst target is wide. Where does a reasonable fair value range actually land within that spread?
Most Popular Narrative: 44% Undervalued
On the most followed view, Joby Aviation’s fair value sits near $10.68, which is well above the recent $5.95 close and frames the current drop as a valuation gap rather than just fading hype.
The eVTOL sector is moving into a more regulated and capital intensive phase. Joby is now in the costly final stages of FAA Type Certification and building five TIA aircraft. Any slippage in certification timing or test results could extend loss making periods and push out the ramp in operating earnings.
See why 43 investors see Joby Aviation as 44% undervalued.
Result: Fair Value of $10.68 (UNDERVALUED)
Still, a few developments could flip the story, including faster-than-expected vertiport rollouts or stronger route uptake from the Blade and Virgin Atlantic partnerships.
Find out about the key risks to this Joby Aviation narrative.
Another Look At Joby Aviation’s Valuation
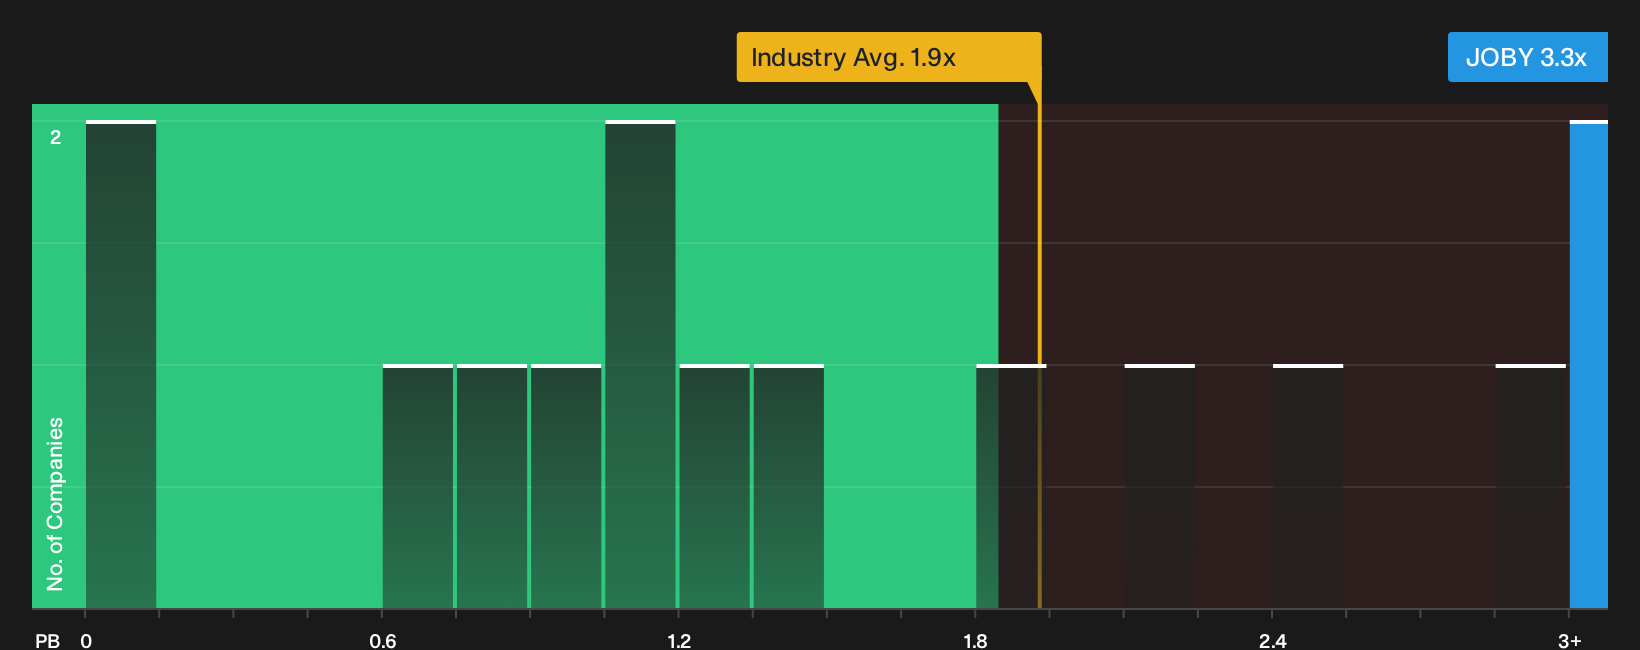
That $10.68 fair value hinges on long range assumptions about Joby Aviation’s future earnings. On simpler yardsticks, the picture is less forgiving. The stock trades on a P/B ratio of 3.3x, while the global Airlines peer group sits near 1.9x. For investors, that premium raises a basic question. Is this still a growth story worth paying up for, or just valuation risk waiting to be repriced?
Before leaning too heavily on any one metric, it can help to see how all the valuation checks line up side by side, including how that P/B premium compares with a fair ratio the market could eventually move toward. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed about the tone of this Joby Aviation story so far. Act quickly, review both sides of the data, and weigh the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Joby Aviation?
If Joby Aviation has you rethinking your watchlist, use this moment to refresh your playbook with fresh opportunities across different styles, sectors, and risk profiles.
- Target potential upside in smaller companies by reviewing the 8 elite penny stocks with strong financials that already pair higher risk with stronger financial underpinnings.
- Strengthen your core holdings by assessing the list of solid balance sheet and fundamentals (25 results) for businesses built on healthier balance sheets and more resilient fundamentals.
- Hunt for tomorrow’s potential leaders by scanning the 19 high quality undiscovered gems before more investors start paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com