


Learn Why The Bull Case For Kohl's (KSS) Could Change Following Online Shopping Pressure
- Kohl's is contending with mixed investor expectations as ongoing shifts toward online and mobile shopping affect store traffic and raise questions about how resilient its earnings profile really is.
- The key issue is whether current valuation reflects structural pressures on Kohl's traditional retail model or an overly pessimistic view of its ability to adapt.
- Next, the focus will be on how these changing views of Kohl's earnings resilience feed into the broader investment narrative for the retailer.
Kohl's Investment Narrative Recap
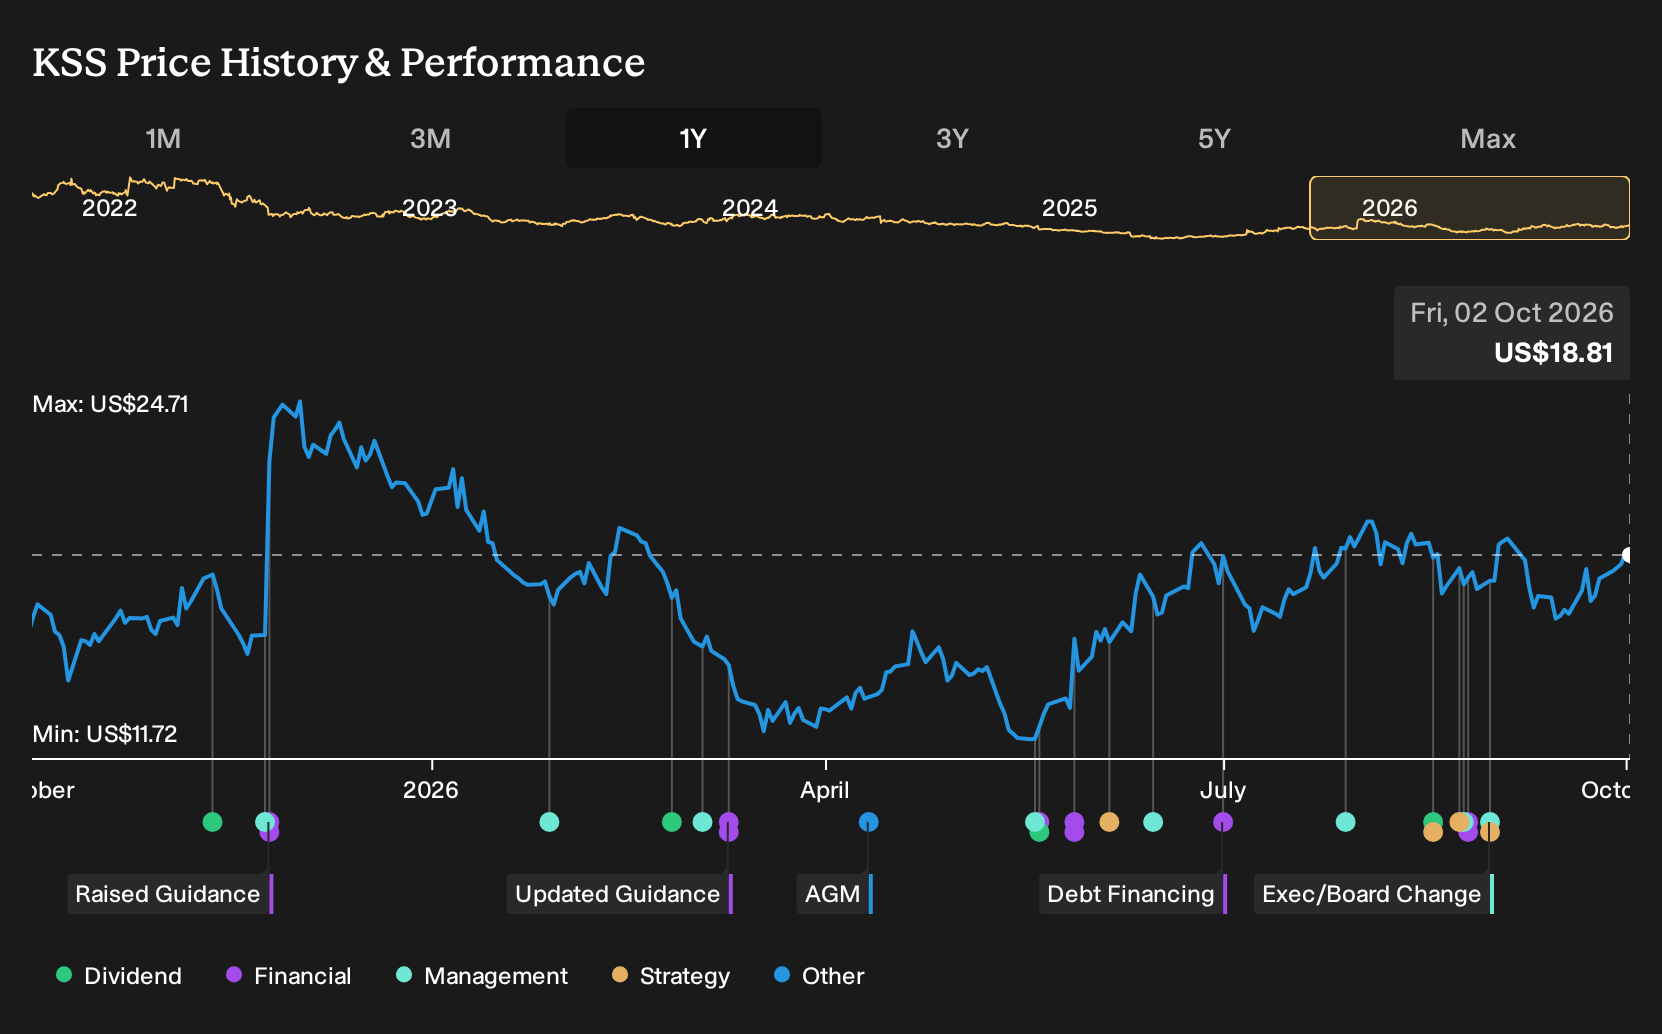
Kohl's asks you to believe the chain can keep reshaping a traditional department store footprint into something that works for online first shoppers. In the short term, potential upside still leans on stabilising traffic through Sephora shop in shops, proprietary labels and tighter promotions. Recent share price swings, with a 9.7% weekly gain but an 11.3% year to date decline, mostly reflect shifting confidence around that earnings durability rather than a clear change in the operating story.
The biggest near term catalyst remains execution on omnichannel retail, particularly getting more profitable digital orders and better conversion from store visits. The key risk sits on the other side of the same coin. If online migration keeps pulling transactions away from Kohl's stores faster than its website and app capture demand, higher promotions, wage pressure and fixed store costs could squeeze margins further.
With no fresh corporate announcements tied directly to this price move, the most relevant reference point is still Kohl's push into higher margin proprietary brands and the Sephora rollout. That effort aims to pull in younger shoppers, deepen baskets with beauty and improve mix, which matters when the customer base is value focused and traffic is under pressure.
The same set of initiatives also frames both upside and downside from here. Stronger performance in private labels, disciplined inventory and cleaner pricing could support earnings resilience even if sales stay flat. Weak execution, slower digital gains or heavier discounting would make it harder to offset store traffic declines, and the recent volatility in Kohl's stock shows how quickly the market reacts to any sign of slippage.
Kohl's Forecasts, Assumptions And Valuation Signals
Analyst models for Kohl's sketch out a modest top line, with revenue expected to stay roughly flat and reach about $15.5b by 2029. Earnings are projected at $227.9 million in the same year. The comparison point today is earnings of $270.0 million, so consensus implies an earnings decline of about $42.1 million alongside a shift in profit margins from 1.7% now to 1.5% by 2029. The P/E multiple is estimated at 13.5x versus 8.1x currently. That picture is also layered over expected share count creep of 0.83% per year and a discount rate of around 12.5% that analysts use to frame what they see as fair value around an $18.69 share price, close to where the stock trades today.
Kohl's narrative projects $15.5b revenue and $227.9 million earnings by 2029. This implies fairly flat annual revenue trends and an earnings decrease of about $42.1 million from current earnings of $270.0 million.
Uncover why Kohl's fair value appears to be generally consistent with its current price.
Exploring Other Perspectives
One alternate view on Kohl's puts the marketplace and Babies"R"Us rollout at the center of the story. In that more optimistic setup, bullish analysts were still penciling in roughly flat revenue of about $15.7b and earnings of $205.8 million by 2029 before this latest price move. Those assumptions could shift. Consider this a prompt to explore several competing narratives rather than anchor on a single forecast.
Explore 3 other Kohl's fair value estimates, including one that suggests as much as 184% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Kohl's research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kohl's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kohl's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kohl's?
Once you have a view on Kohl's, it helps to widen the lens and compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener can help you filter for businesses that match what you want in terms of balance sheet strength, income potential, or future prospects.
- If capital preservation is a priority, start with resilient businesses by scanning our 31 resilient stocks with low risk scores for candidates with steadier profiles.
- For income focused investing, check out companies that offer meaningful yield through our hand picked 7 dividend fortresses to see which ones line up with your return targets.
- If you want to look earlier in the story, scan the 19 high quality undiscovered gems and see which underfollowed opportunities might be worth a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com