


Shake Shack (SHAK) Could Be 48% Undervalued On Its Expansion Narrative
Shake Shack (SHAK) drew fresh attention after its shares closed at $60.98 on 2 October 2026, giving the burger chain an equity value of about $2.61b and sharpening focus on its recent performance.
Recent trading has been choppy for Shake Shack, with the share price up 1.31% on the day and 9.78% over the past week, yet down 12.13% over 30 days and 26.94% year to date. The 1 year total shareholder return has fallen 37%, while the 3 year total shareholder return is still positive at 8.45%, suggesting short term momentum has cooled even as longer term holders have seen mixed results.
Scan beyond Shake Shack's recent swings and line up potential alternatives using our curated 31 high quality undervalued stocks, which includes companies with solid cash generation and balance sheets.Shake Shack now trades at a meaningful discount to both analyst targets and one estimate of fair value. Is the market rightly cautious, or has the latest sell off gone too far on valuation alone?
Most Popular Narrative: 48% Undervalued
Based on the most followed narrative, Shake Shack is priced well below an estimated fair value of $116.37, compared with the recent close at $60.98. This frames the current sell off as a potential gap between execution risk and long term expectations.
The combination of roughly 20% lower net build costs per new Shack, recent new class returns above 30% cash on cash, and drive thru formats producing incremental revenue above core designs opens a path for future units to be more capital efficient than the base portfolio. This can support higher returns on invested capital and improved free cash flow.
See why 3 investors see Shake Shack as 48% undervalued.
Result: Fair Value of $116.37 (UNDERVALUED)
Still, the bullish Shake Shack story can crack if record beef and distribution costs stay high or if recent earnings misses keep investors wary of management guidance.
Find out about the key risks to this Shake Shack narrative.
Another View: Shake Shack On Earnings Multiples
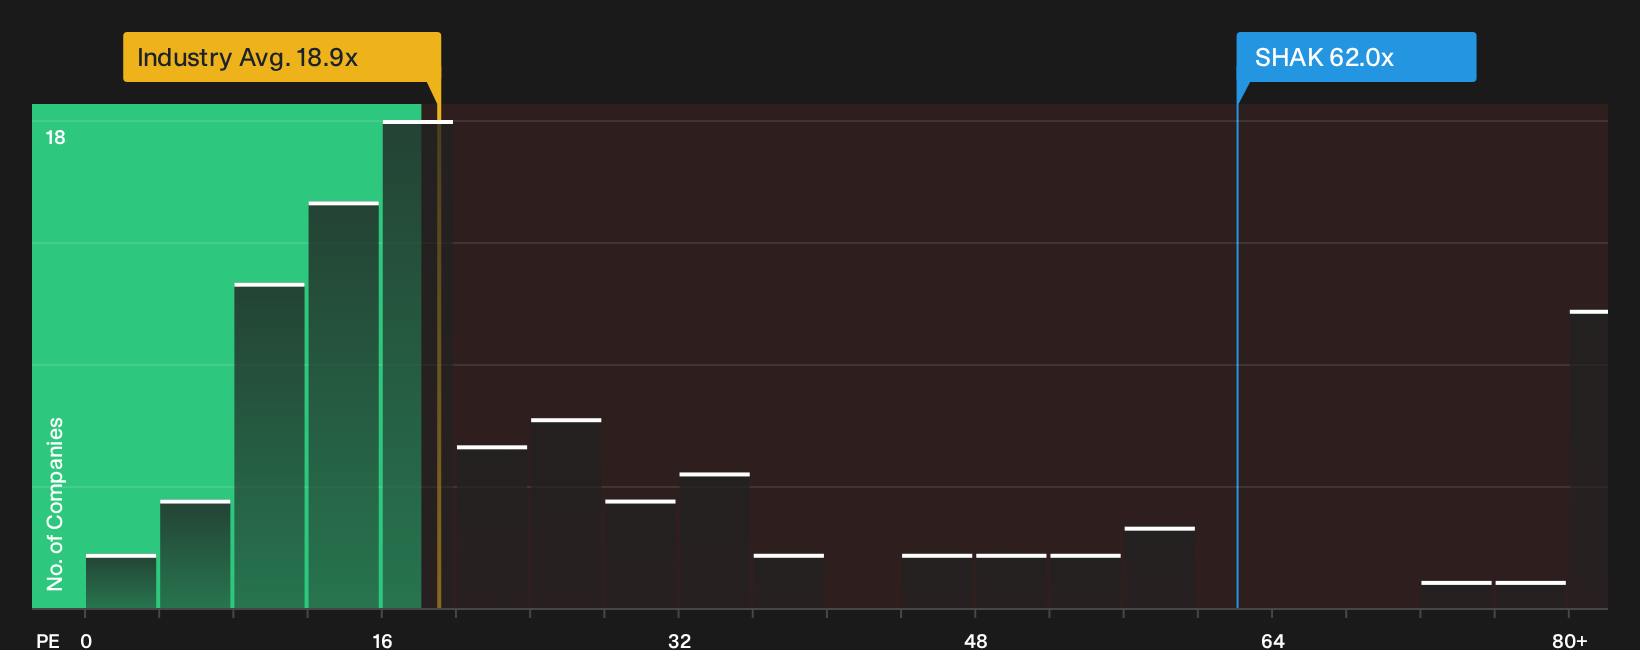
The bullish fair value of $116.37 paints Shake Shack as undervalued, yet the current P/E of 62x tells a different story. That valuation is far higher than both the US Hospitality industry at 18.9x and peers at 18.2x, and almost triple the fair ratio of 22.1x, which implies meaningful downside risk if sentiment cools.
When one framework flags upside and another points to an expensive earnings multiple, which signal should matter more for your own process, and over what time frame?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Shake Shack is split, so move quickly past the headlines and review the underlying data for yourself before opinions harden. To weigh those positives directly, take a closer look at the 3 key rewards.
Looking for more Shake Shack style investment ideas?
If you only stop at Shake Shack, you risk missing other opportunities that could fit your goals even better. Broaden your search with a few focused screens.
- Target potential mispricings by scanning companies that combine quality fundamentals with attractive entry points through the 31 high quality undervalued stocks.
- Strengthen your income watchlist by reviewing businesses with robust payout profiles using the 7 dividend fortresses.
- Dial down overall portfolio stress by filtering for resilient, lower risk opportunities via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com