


Battery Storage Push Could Be A Game Changer For Wärtsilä Stock (HLSE:WRT1V)
- Wärtsilä and RCT Solutions have launched Valo as a dedicated global battery energy storage system integrator and, in a separate alliance with Schneider Electric and Stanley Consultants, introduced a coordinated “Generator-to-Chip” power concept for U.S. AI data centers. Both initiatives were announced in late September and early October 2026.
- These moves push Wärtsilä deeper into utility-scale storage integration and data center power solutions, tying its traditional engine expertise more closely to grid-scale batteries, digital controls and long-duration project services.
- We will now look at how Wärtsilä's investment narrative could shift as it connects engine power plants more directly to utility-scale storage.
Wärtsilä Oyj Abp Investment Narrative Recap
To own Wärtsilä Oyj Abp, you need to believe the shift from pure engines toward integrated energy and marine solutions can keep earnings quality high as regulations and customer preferences evolve. The key near term swing factor remains how consistently the existing order backlog in energy and marine converts into cash flow while service activity stays resilient.
The biggest risk is that clean tech and pure renewables pull demand away from engine based power plants faster than Wärtsilä’s portfolio tilts toward storage and alternative fuels. The Valo launch and Generator to Chip concept look more evolutionary than transformative for the next few quarters, so they do not fundamentally change that risk reward balance yet.
The Generator to Chip alliance with Schneider Electric and Stanley Consultants looks closest to a practical near term catalyst. It links Wärtsilä’s modular engine plants directly with electrical infrastructure and digital controls for U.S. AI data centers where power availability and build speed are under pressure.
If this bundled offer converts into contracted projects, it could reinforce recent momentum in energy order intake and add a visible services opportunity around lifecycle support. Execution risk is real, though. Large data center builds are complex, permitting can slow progress, and Wärtsilä must coordinate seamlessly with partners to protect margins and timelines.
What Consensus Numbers Say About Wärtsilä Oyj Abp
Analysts currently model Wärtsilä Oyj Abp on a relatively clear set of headline assumptions. Revenue is projected to increase by 6.7% per year over the next three years, profit margins are expected to move from 9.4% today to 10.4% around 2029, and aggregate earnings are estimated at €871.9 million in that year. Those profit forecasts sit against earnings today of €650.0 million, with the most optimistic forecasts at €1.0b and the most cautious at €776.3 million, so the spread of views is wide even if the central estimate is reasonably tight.
Wärtsilä Oyj Abp’s narrative projects €8.4b revenue and €871.9 million earnings by 2029. This implies 6.7% yearly revenue growth and an earnings increase of about €221.9 million from €650.0 million today.
The current consensus ties those profit expectations to a target valuation multiple. To hit analyst price targets, the stock would need to trade on a P/E of 27.2x on the 2029 earnings figure, compared with 31.1x today and against a quoted 25.9x for the wider GB Machinery industry. That setup implies investors are being asked to underwrite slightly higher pricing than the sector, even as the assumed multiple moderates from current levels.
On top of that, analysts build in only marginal equity dilution, with the share count expected to rise by about 0.19% per year over the next three years. That low projected issuance means most of the earnings trajectory in these models flows directly to per share figures rather than being diluted by new stock.
The valuation section of the consensus work then rolls those earnings and margin assumptions into a headline target price. The average analyst price target sits at €32.33, framed by a bullish end at €42.0 and a bearish marker at €18.0. Against a recent share price of €34.27, the central target is about 6.0% lower, which suggests many forecasters view the shares as roughly in line with their own estimates rather than clearly cheap or clearly expensive.
For anyone tracking Wärtsilä Oyj Abp as a way to gain exposure to data center power and grid edge upgrades, these numbers give a reference point. The models effectively ask you to judge whether mid single digit top line growth, a modest margin uplift, and a P/E that stays above the broader machinery group feel reasonable given Wärtsilä’s push into storage integration, AI focused engine plants and longer term service agreements.
Uncover why Wärtsilä Oyj Abp's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
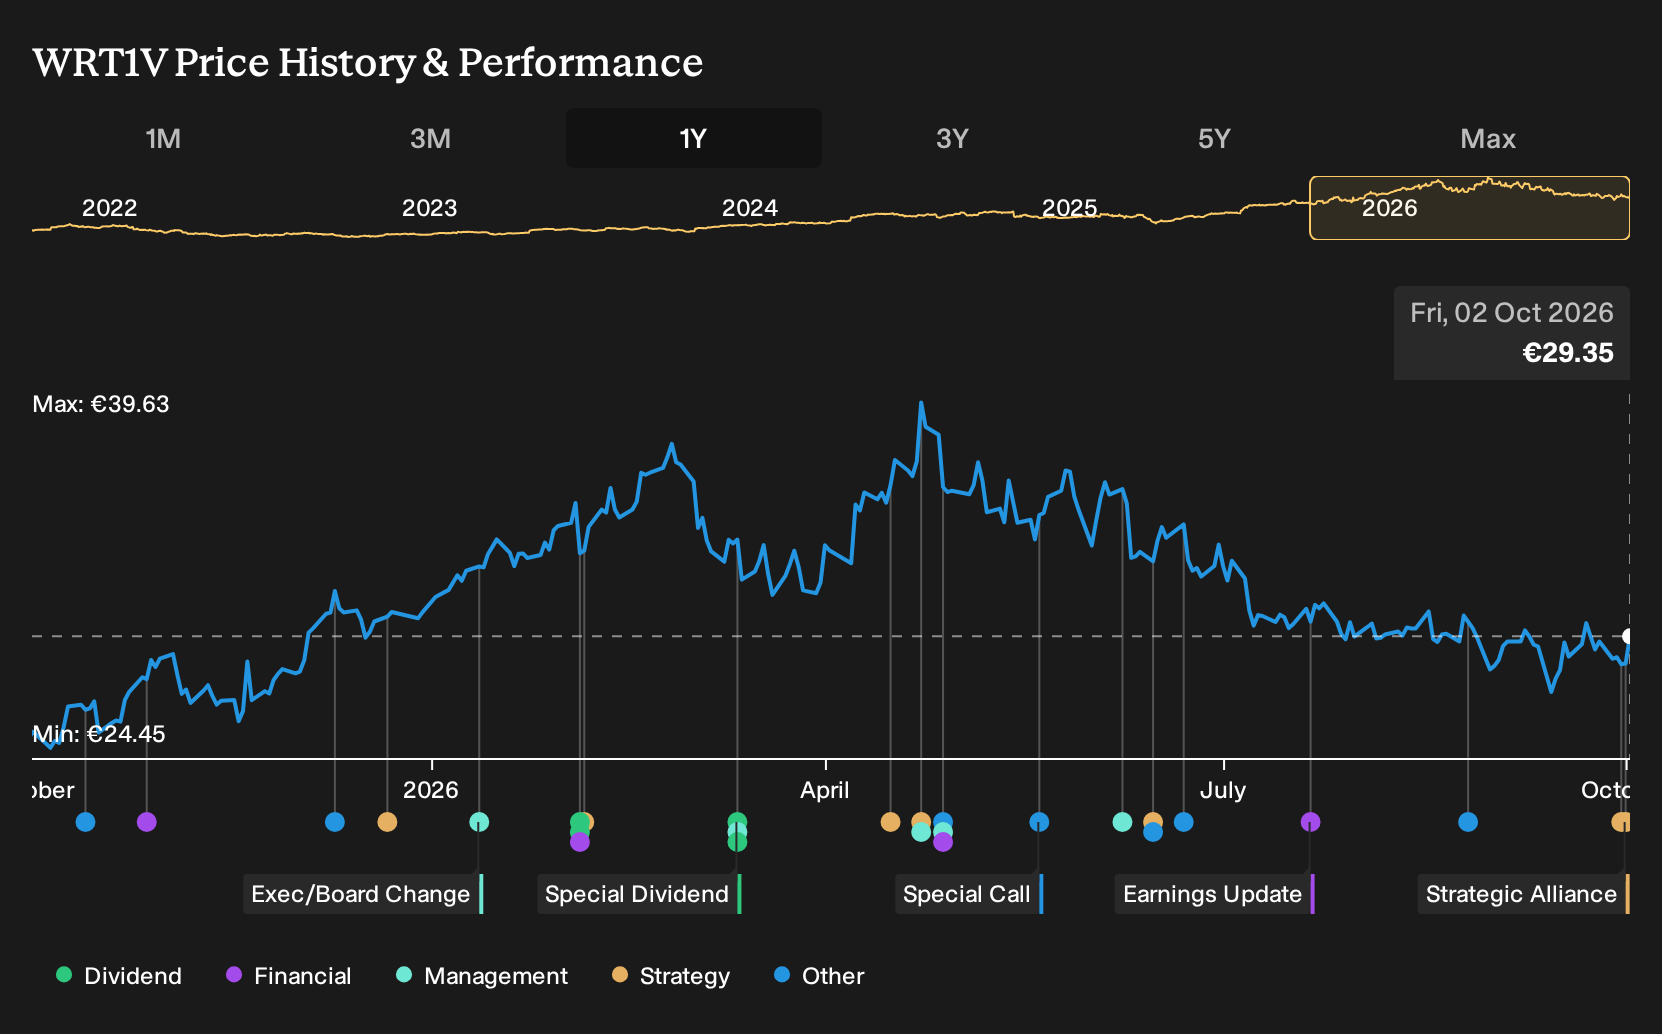
Exploring Other Perspectives
You now have a clear fork in the story. The most optimistic analysts already pencilled in €9.4b of revenue and €1.0b of earnings by 2029, largely on the idea that data center power and digital services could scale quickly. The Valo launch and Generator to Chip concept might push that thesis further, or cause forecasts to be revisited entirely. Use these contrasting views as a prompt to compare your own expectations with both the cautious and upbeat cases.
Explore 4 other Wärtsilä Oyj Abp fair value estimates, including one that suggests as much as 47% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Wärtsilä Oyj Abp research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Wärtsilä Oyj Abp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wärtsilä Oyj Abp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Wärtsilä Oyj Abp?
If the Wärtsilä Oyj Abp story has sharpened your thinking about power, infrastructure and capital allocation, use that momentum to widen your watchlist with companies that fit your preferred balance of quality, risk and income.
- Focus on quality at a reasonable price by scanning a hand picked set of companies that screen as attractively priced on fundamentals through 193 high quality undervalued stocks.
- If capital preservation is front of mind, narrow in on businesses with stronger balance sheets and steadier financial profiles using our list of solid balance sheet and fundamentals (206 results).
- For investors who like to back under followed opportunities, surface less crowded ideas with robust underlying metrics through our 615 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com