


How Investors May Respond To First BanCorp Stock As Dividend Growth Draws Focus
- First BanCorp currently offers a 3% dividend yield compared with the 2.55% Banks - Foreign industry average, and has raised its payout five times in five years with an average annual increase of 29.65%, alongside a Zysts consensus earnings estimate of US$2.40 per share for fiscal 2026 that implies 18.23% year over year growth.
- This mix of above industry income, a rapid dividend growth history, and an earnings forecast tied to operational performance has drawn fresh attention to First BanCorp's ability to generate cash for shareholders while still funding its banking franchise.
- We will examine how First BanCorp's investment narrative is influenced by this stronger dividend profile and the 2026 earnings outlook.
Scan income-focused opportunities with dividend profiles similar to First BanCorp by moving through our hand picked 7 dividend fortresses for yield driven investors.
First BanCorp Investment Narrative Recap
For you to back First BanCorp, you need to be comfortable with a bank that leans heavily on Puerto Rico, Florida, and the Virgin Islands for growth, and that is still investing in digital capabilities and fee income while managing higher regulatory and technology costs. The recent update around a 3% dividend yield and the earnings expectation for 2026 indicates that the thesis hinges on consistent loan demand, deposit stability, and expense control rather than a radical shift in direction.
The most important short term swing factor is how funding costs and competitive pressure on deposits shape net interest margin, especially as higher rate expectations keep customers focused on yield. The biggest operational risk remains concentration in a few regions that can be hit by local economic shocks or natural disasters, so the latest dividend and earnings outlook mainly signals confidence rather than materially changing that exposure.
Among recent information tied to this story, the Zysts consensus earnings estimate of US$2.40 per share for fiscal 2026 is the reference point that links First BanCorp's dividend profile to its operating engine. That forecast implies 18.23% year over year earnings growth, which sets a clear bar for how well management needs to execute on loan growth, credit quality, and cost discipline to keep the dividend covered.
For you as a shareholder, the useful way to view that figure is as a stress test of the current business mix rather than as a guarantee. If loan growth in Puerto Rico and the broader footprint slows, or if deposit pricing pressure intensifies, it becomes harder to line up that earnings number with ongoing dividend growth. If asset quality and digital adoption trends hold close to recent patterns, the current payout and earnings path appear more operationally aligned than speculative.
First BanCorp's narrative projects US$1.2b revenue and US$358.0 million earnings by 2029. This assumes 8.7% yearly revenue growth and an earnings decline of US$14.6 million from US$372.6 million today.
Uncover why First BanCorp's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
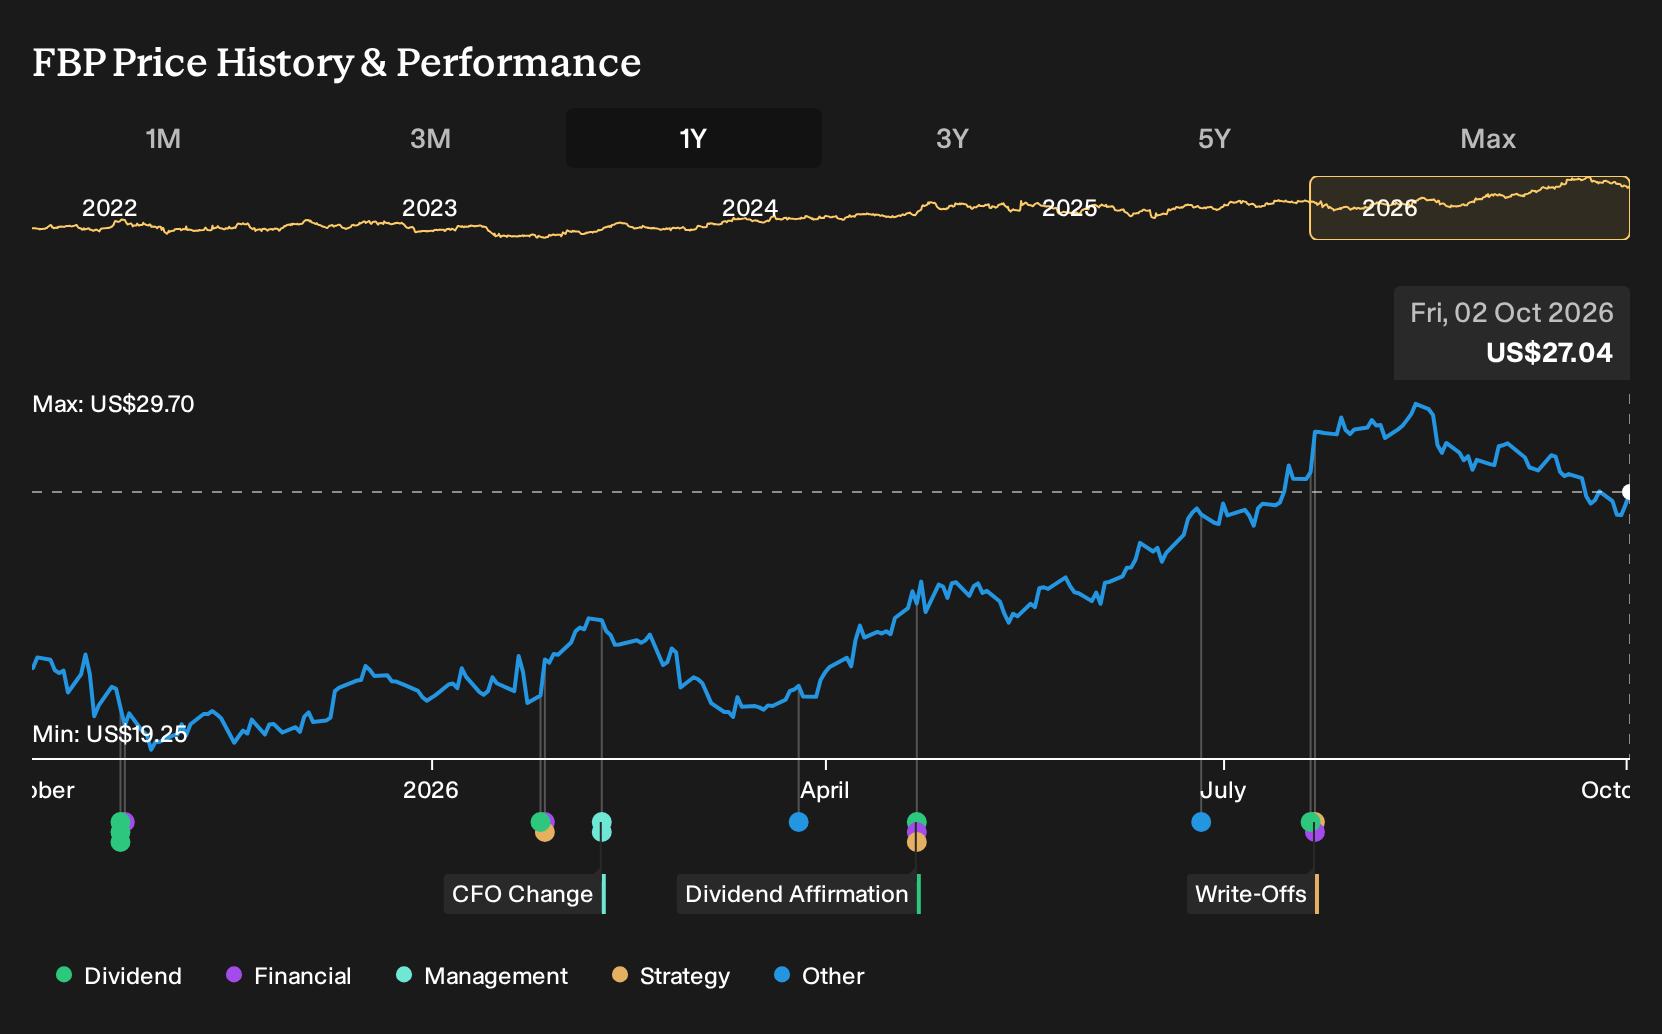
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$31 to just under US$59, so some investors see First BanCorp as far cheaper than others. That gap sits beside real risks around geographic concentration and deposit competition. Consider this a prompt to compare several viewpoints before forming your own view.
Explore another First BanCorp fair value estimate, including one that suggests potential upside of up to 118% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your First BanCorp research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for First BanCorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First BanCorp's overall financial health at a glance.
Looking For More Ideas Beyond First BanCorp?
Once you have a handle on First BanCorp, it can help to widen the lens and compare it with peers that offer different combinations of income, balance sheet strength, and risk. The Simply Wall St screener tools make that comparison more structured so you are not just reacting to headlines or price moves.
- If you want income with fewer surprises, focus on payouts from sturdier businesses by scanning our 7 dividend fortresses that aim to pair yield with consistent fundamentals.
- If your priority is resilience through the cycle, check the 31 resilient stocks with low risk scores that filters for companies with stronger financial profiles and lower overall risk scores.
- If you are hunting for opportunities that the market may be pricing cautiously, work through the 31 high quality undervalued stocks that flags high quality stocks where fundamentals and price are not fully aligned.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com