


Cohu (COHU) Draws AI Test Attention As Fair Value Questions Follow
Cohu (COHU) is drawing fresh attention after recent commentary highlighted its Neon inspection platform’s role in semiconductor test demand tied to AI infrastructure, putting the company’s broader test and inspection portfolio back in focus for investors.
The recent focus on Cohu’s Neon platform lands on a stock that has already attracted strong attention, with a 30-day share price return of 44.87% and a year-to-date share price return of 198.58%. This aligns with a 264.12% total shareholder return over the past year and suggests that momentum has been building as investors reassess both growth potential and risk around AI-driven semiconductor test demand.
Scan beyond Cohu to see which other AI-linked semiconductor testers are already building momentum in our curated list of 90 AI infrastructure stocks.
Cohu’s surge now forces a simple tension. Are you looking at a repricing of the underlying test and inspection business, or a sentiment swing around AI that valuation needs to decode next?
Most Popular Narrative: 4% Overvalued
Cohu’s most followed valuation narrative points to a fair value of $70.88 against a last close of $73.48, which implies a modest premium that investors now have to explain through future AI test demand and margin recovery.
The push towards automation, data analytics, and AI-driven yield/process optimization through Cohu's software suite (DI-Core, Tignis) supports an ongoing shift to higher-margin, recurring software and services revenue. This shift is expected to enhance long-term net margins and earnings stability. Strategic diversification into automotive, industrial, precision analog, and display/AR markets (beyond traditional consumer electronics) is increasing the resilience and breadth of Cohu's revenue base, making earnings less vulnerable to cyclical downturns and customer concentration risks.
See why 11 investors see Cohu as 4% overvalued.
Result: Fair Value of $70.88 (OVERVALUED)
Still, the Cohu narrative can crack if early stage AI handler wins fail to qualify at key customers or if Asia-centric manufacturing shifts introduce unexpected execution hiccups.
Find out about the key risks to this Cohu narrative.
Another View on Cohu’s Valuation
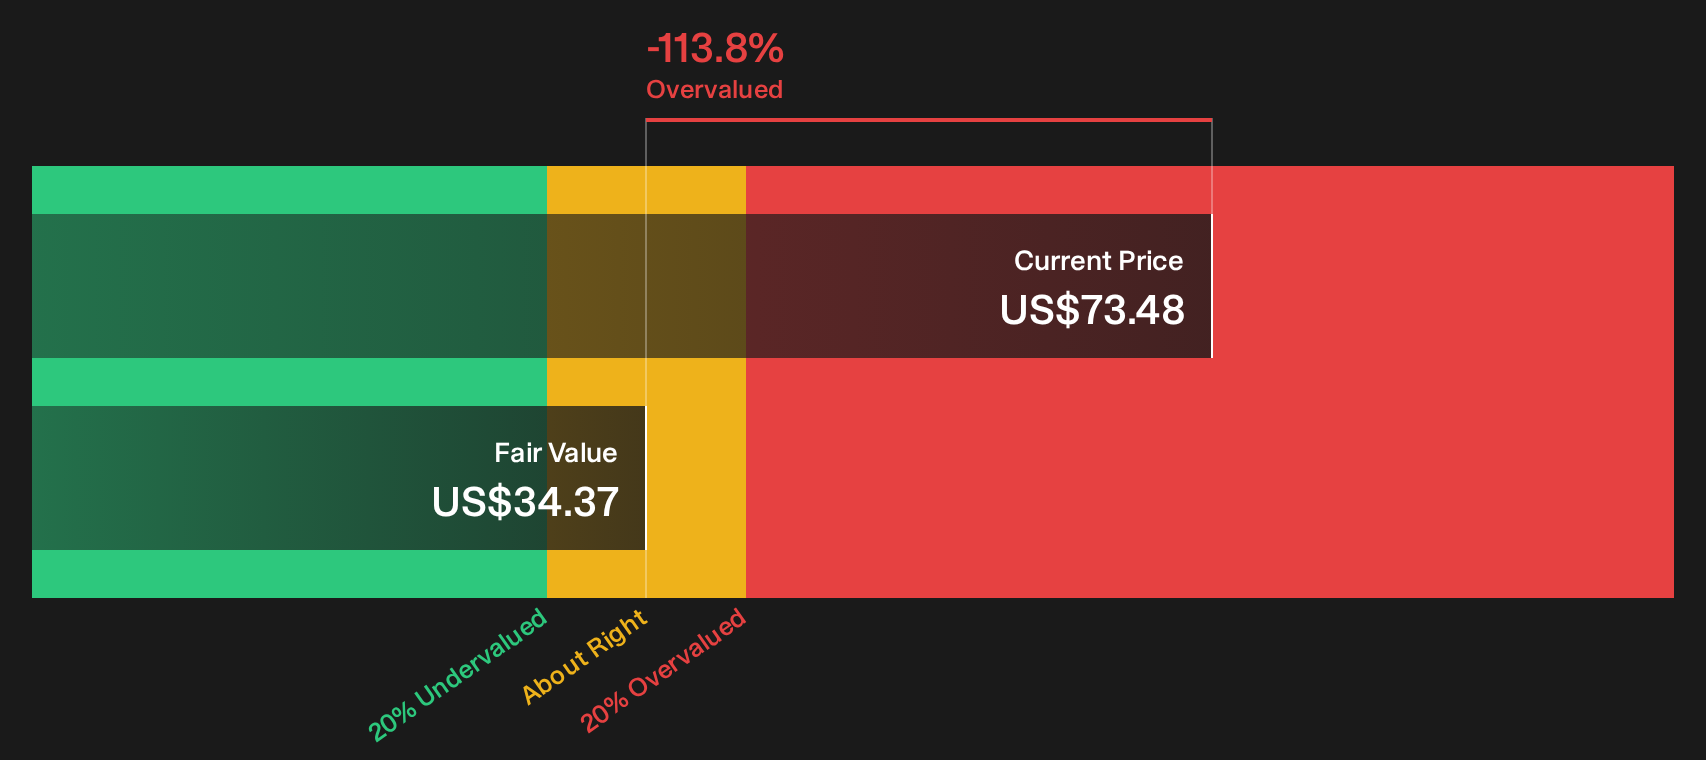
The analyst narrative leans on earnings forecasts and price targets, yet the SWS DCF model tells a much harsher story. At $73.48, Cohu trades well above an estimated future cash flow value of $34.37, which screens as overvalued. Which signal do you trust more: the story or the cash flows?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed on Cohu after all this. Move quickly, review the full data set, and weigh both the upside and the red flags in 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Cohu?
If Cohu has you rethinking your watchlist, do not stop here. Apply the same discipline to other opportunities that match your risk and return preferences.
- Target steadier compounding by scanning for resilient businesses through the 31 resilient stocks with low risk scores.
- Look for potential mispriced opportunities using the carefully filtered 19 high quality undiscovered gems.
- Prioritise financial strength and shortlist candidates from the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com