


3 Travel Stocks Tied To Europe’s Budget Hostel Boom
European budget travel is being rebuilt in front of you, as institutional money moves into hostels and mass-market operators start packaging dorm beds like resort stays. That shift could reshape how value flows across real estate, construction and listed hospitality stocks, and missing the early innings may feel painful later. This article walks through three stocks that look closely tied to this hostel news wave and what that might mean for your portfolio.
The stocks covered below are just a first pass on this theme, and the full screen surfaced 9 more European budget travel and hostel-focused operators with equally compelling narratives that are not discussed here. To identify and analyze the highest conviction ideas in this niche, head straight into the European budget and hostel-focused travel & hospitality operators screener.
Hostelworld Group (LSE:HSW)
Overview: Hostelworld Group runs a Dublin based online travel platform that connects youth and budget travelers with hostel and low cost lodging worldwide.
Operations: The business generates about €99 million from software and data processing services, with hostel focused bookings sourced across Europe, the Americas, and Asia, Africa and Oceania.
Market Cap: £124 million
For anyone interested in the hostel and backpacker theme, Hostelworld Group offers targeted exposure to bed capacity, youth travel demand, and budget friendly destinations, even as recent earnings and margins show some pressure. The opportunity sits in how this specialist hostel platform converts institutional hostel investment into healthier profitability, depending on how one unseen pressure plays out.
That turning point starts with understanding how recent pressure, future hostel supply, and platform economics intersect in the analysis report for Hostelworld Group before the market fully prices that shift.

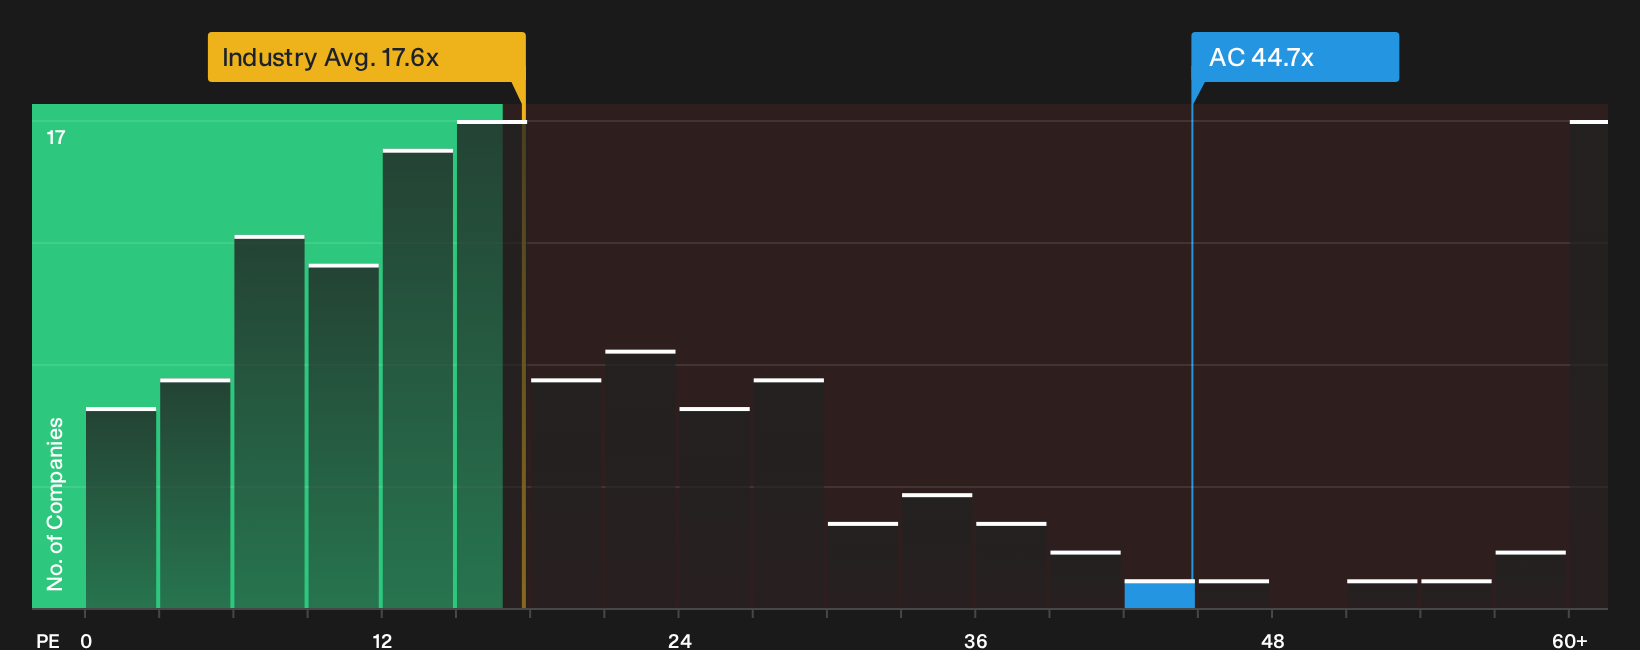
Accor (ENXTPA:AC)
Overview: Accor runs a global hotel group anchored by budget and midscale brands like ibis, alongside premium and luxury flags across multiple regions.
Operations: The group earns about €3.8b in revenue, primarily from Premium, Midscale and Economy activities. This includes €1.0b in hotel assets and €0.9b in management and franchise fees.
Market Cap: €10.3b
Accor matters for this hostel and budget travel screen because its ibis and other economy badges sit closest to where institutional capital is pushing new low cost capacity. This positioning puts the group in a place to redirect that demand through its existing brands and distribution pipes.
"Continued shift toward an asset-light model, with disciplined focus on higher fee-per-room contracts and quality churn, is expected to improve net margins and enhance stability/recurrence of earnings by reducing capital expenditure and exposure to owned hotel volatility."
What really moves the dial for Accor now is how one evolving pressure in its budget network filters through to future pricing power.
That pricing question is exactly where the full narrative for Accor shows whether Accor's asset light shift is quietly accelerating earnings power or instead masking new pressure in its budget tier.
TUI (XTRA:TUI1)
Overview: TUI AG is a Hanover based tourism group that runs package holidays, airlines, cruises, hotels, and digital tour booking platforms.
Operations: TUI AG generates most of its revenue from Markets & Airlines in Northern and Central Europe, together producing around €17.7b annually.
Market Cap: €3.5b
TUI gives this hostel and budget accommodation theme a different angle, since its tour packages and airline seats can funnel cost conscious travellers into large scale, pre arranged trips where cheaper beds, including hostel style options, are part of the bundle rather than the main attraction.
"TUI is leveraging its vertical integration across airlines, hotels, cruises, and ground experiences, resulting in higher occupancy rates, increased daily rates, full cruise ship utilization, and the cross-selling of high-margin, differentiated products."
What really decides how TUI benefits from the hostel shift is whether one unresolved pressure inside its mass market packages keeps squeezing margins.
That margin squeeze is the real hinge, and the full narrative for TUI shows whether TUI's vertical model is quietly converting hostel pressure into accelerating earnings power, or just masking strain.

Seeking Alternatives Before The Crowd
Fresh ideas do not stay quiet for long. Breakout stories gain momentum, under the radar for now, then get caught once prices start flying. Do not delay, get in early.
- Target resilient cash generators before defensive money rotates into them by scanning the list of solid balance sheet and fundamentals (9 results), which is curated for staying power when conditions shift.
- Ride structural growth themes while they are still dropping under most radars by zeroing in on the 90 AI infrastructure stocks, built around mission critical spending.
- Position ahead of capital flows chasing hard assets by tracking producers in the 16 top copper producer stocks, where demand stories meet real operating businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com