


Louisiana-Pacific (LPX) Expands SmartSide Distribution, Is The Pullback A Buying Opportunity?
Louisiana-Pacific (LPX) just reset how its flagship LP SmartSide siding reaches buyers by rolling out a nationwide distribution model anchored by an expanded BlueLinx partnership and a select group of committed regional wholesalers.
Despite the expanded SmartSide rollout, Louisiana-Pacific’s recent share price performance has been under pressure, with the stock at US$65.10 after a 90-day share price return that declined 16.12% and a year-to-date share price move down 20.35%. The 3-year total shareholder return of 30.31% points to a longer-term story that has been more constructive than the past year’s 26.86% decline in total shareholder return.
Scan beyond Louisiana-Pacific and see how other building solutions peers are positioned in our hand-picked list of solid balance sheet and fundamentals (25 results) for this part of the cycle.
So with Louisiana-Pacific shares sliding despite the broader SmartSide distribution reset, is the current pullback giving you a sensible entry point on valuation, or simply flagging that the risk now leans heavier than the reward?
Most Popular Narrative: 29% Undervalued
On the most followed view, Louisiana-Pacific screens as undervalued, with a fair value of about $92.07 against the latest close at $65.10. This puts the new SmartSide distribution push in the spotlight.
Accelerated adoption of LP's SmartSide and ExpertFinish trim and siding products, supported by SmartSide volume and revenue compound growth that has outpaced single family housing starts over the past 15 years and by ExpertFinish volumes that grew 35% year over year in Q4 2025, continues to point to potential above market volume growth and stronger long term revenue and gross margin.
See why 12 investors see Louisiana-Pacific as 29% undervalued.
Result: Fair Value of $92.07 (UNDERVALUED)
Still, the Louisiana-Pacific thesis can come unstuck if housing starts and repair activity stay weak or if low OSB pricing keeps segment earnings under pressure.
Find out about the key risks to this Louisiana-Pacific narrative.
Another View: What Multiples Say About Louisiana-Pacific
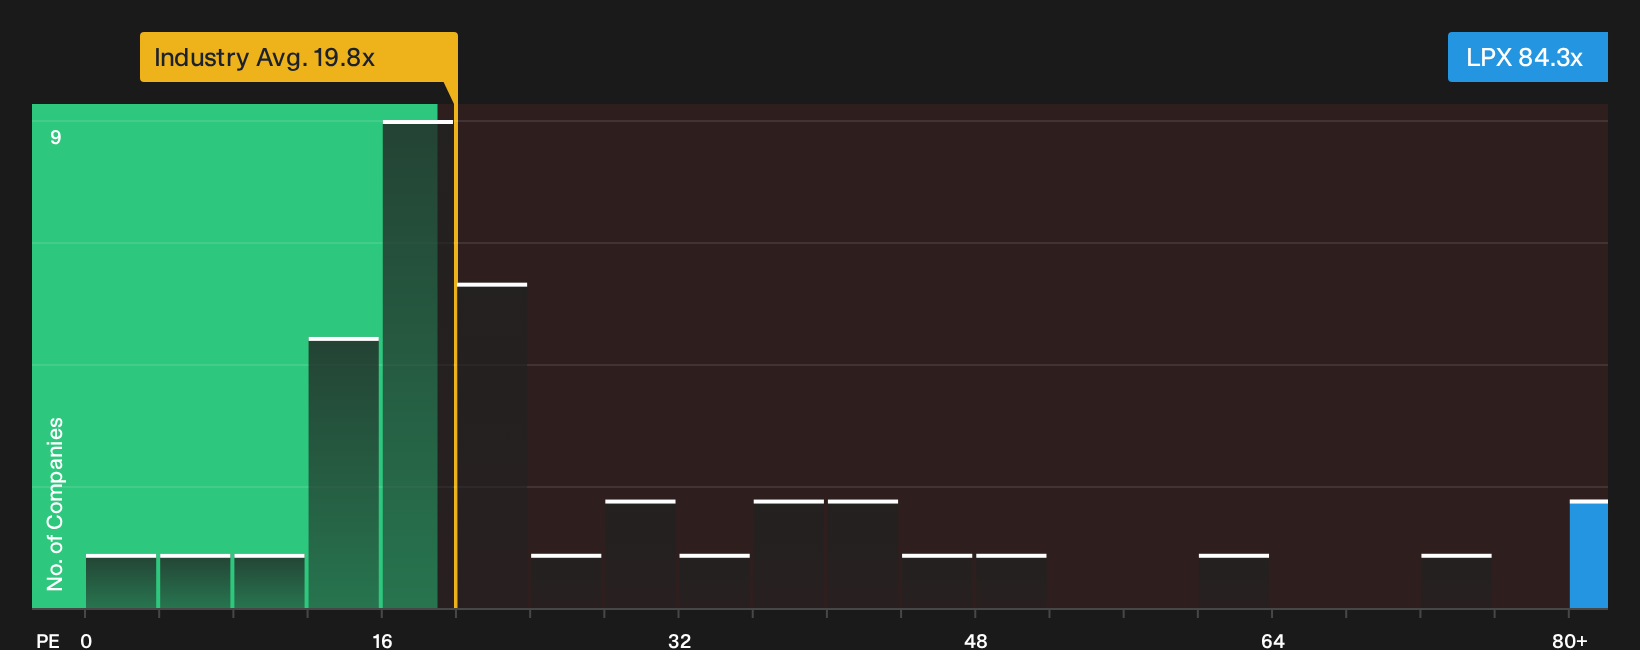
There is a catch. On simple P/E math, Louisiana-Pacific looks expensive, trading at 84.3x earnings against a peer average of 23.3x and a fair ratio estimate of 81.8x. That gap points to limited margin of safety if earnings forecasts slip or the SmartSide story takes longer to play out.
Before leaning on the analyst fair value, it helps to see what the numbers imply at different earnings levels and P/E outcomes, including how far the market might move toward that fair ratio over time and what that would mean for your risk budget today. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Louisiana-Pacific feels familiar, consider reviewing the underlying data yourself as soon as possible. Then weigh up the 2 key rewards and 3 important warning signs
Looking for more Louisiana-Pacific investment ideas?
Do not stop your research with Louisiana-Pacific alone. If you want a clearer picture of where to put fresh capital to work, broaden your watchlist right now using the Simply Wall Street Screener so you do not miss opportunities that fit your style.
- Target sturdier candidates by focusing on companies with cleaner finances through our curated list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by scanning our hand picked list of 31 high quality undervalued stocks before the crowd catches on.
- Prioritise peace of mind by zeroing in on 31 resilient stocks with low risk scores that may help smooth out the rough patches in your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com