


How Investors May Respond To Commercial Metals Stock Before Fourth Quarter Earnings
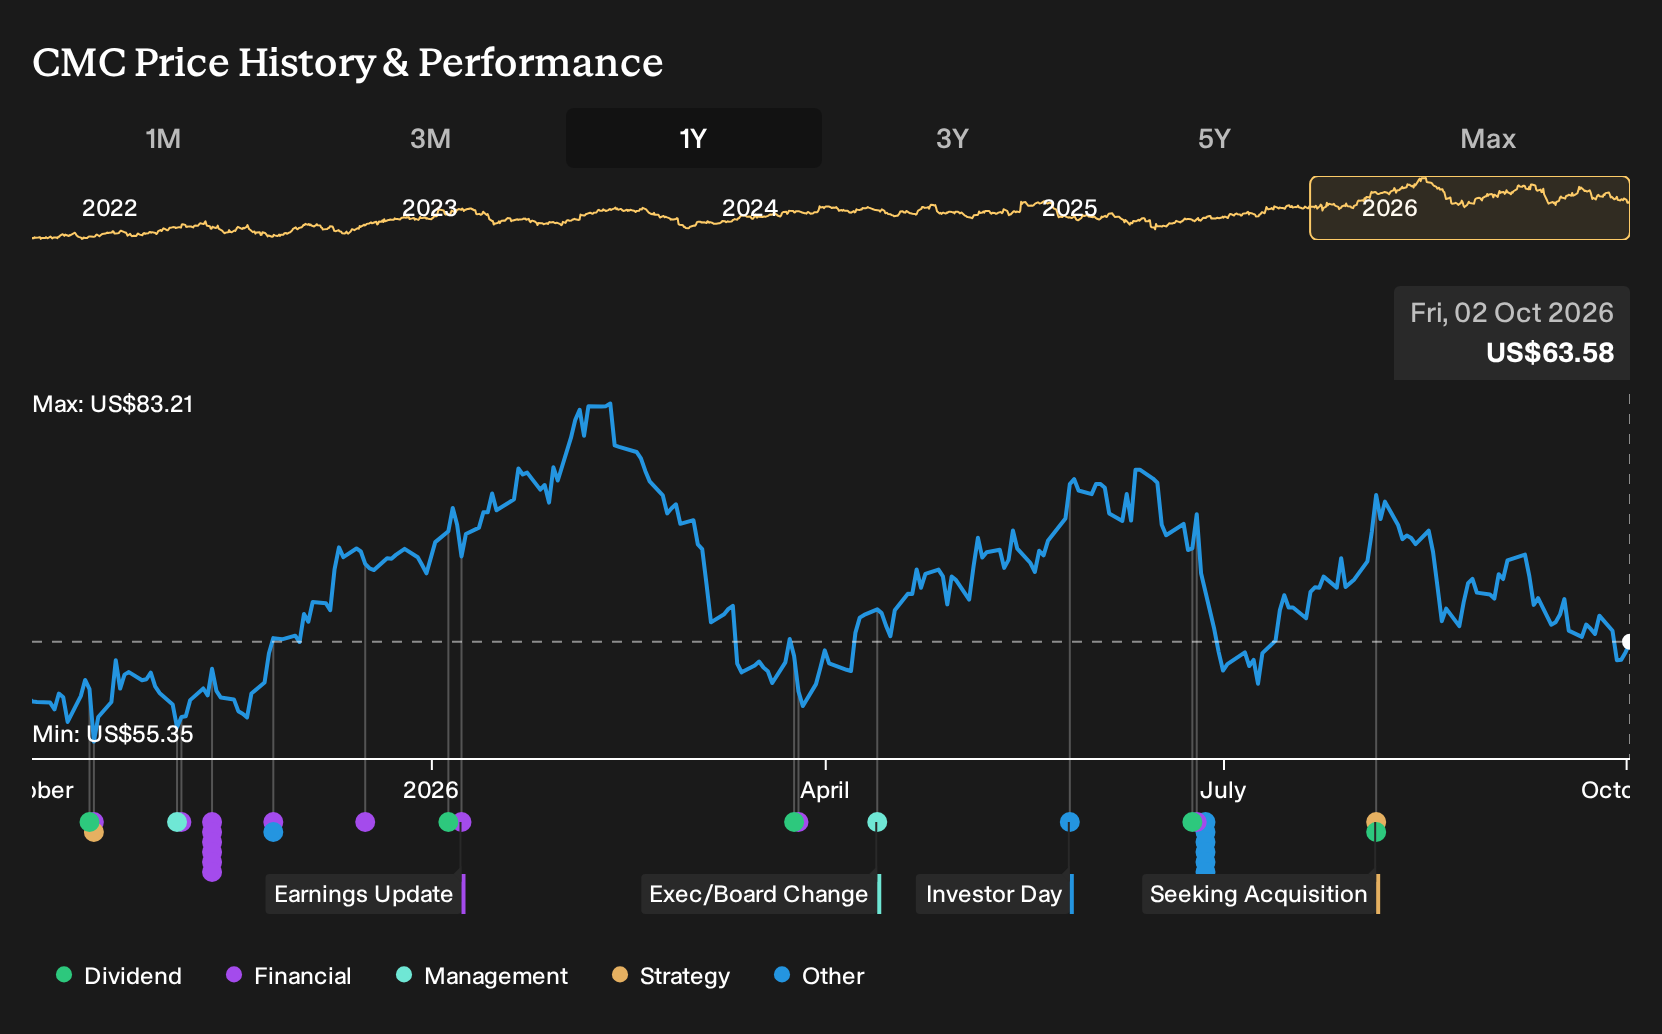
- Commercial Metals Company plans to report its fourth quarter earnings on October 15, 2026, with analysts forecasting earnings of $1.98 per share on revenue of $2.56 billion, following an earlier $600 million increase to the authorized share repurchase program.
- The enlarged buyback authorization, combined with expectations for higher quarterly earnings per share, highlights management’s focus on capital returns alongside its core steel and metals operations.
- This article now examines how Commercial Metals’ investment narrative is influenced by the expanded share repurchase program ahead of the fourth quarter earnings release.
Scan how Commercial Metals’ capital return story compares with other potential opportunities by reviewing our curated list of list of solid balance sheet and fundamentals (25 results) in similar heavy-industry and materials sectors.
Commercial Metals Investment Narrative Recap
To own Commercial Metals, you need to be comfortable with a cyclical construction and infrastructure story that leans heavily on execution at projects like Arizona 2 and Steel West Virginia, as well as the TAG efficiency program. The upcoming fourth quarter earnings report is the next real check on how these initiatives are feeding into profitability and volume.
The biggest near term swing factor remains how scrap spreads, rebar pricing and start up costs interact in a still choppy macro and tariff backdrop. Weather disruptions, copper hedging losses or slower project awards could all show up quickly in margins. The fresh earnings data matters here, but it does not change those core risks.
The expanded US$600 million share repurchase authorization is the announcement that links most directly to this earnings setup. It points investors back to two questions: how much free cash flow Commercial Metals is generating from its mills and fabrication operations, and how management is choosing between debt reduction, new projects and returning cash to shareholders.
Buybacks can tighten the share count over time, which makes execution on TAG savings, mill ramp ups and European cost control even more important for each remaining share. The October 15 release should help you judge whether current returns on that higher capital spend, plus the company’s existing debt load, leave enough room for this enlarged program to continue without squeezing future flexibility.
Commercial Metals Consensus Setup Behind The Buyback
Commercial Metals' current analyst storyline points to revenues of US$10.5b and earnings of US$714.6m by 2029. That profile assumes revenue grows by 7.8% each year and earnings rise by about US$209.4m from US$505.2m today.
Uncover why Commercial Metals' fair value indicates a 27% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate storyline around Commercial Metals leans heavily on TAG and new mill capacity as a potential upside catalyst. The most optimistic analysts were penciling in about US$10.9b of revenue and US$675.4m of earnings by 2029, and a higher 18.7x P/E, even before the US$600m buyback expansion. That shows how far views can stretch, so it may be useful to treat the new repurchase news as a fresh reason to compare these different scenarios yourself.
Explore 3 other Commercial Metals fair value estimates, including one that suggests potential upside of up to 108% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Commercial Metals research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Commercial Metals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Commercial Metals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Commercial Metals?
If the Commercial Metals story has sharpened your thinking about capital allocation and balance sheet strength, it can be useful to widen the lens and line it up against other listed businesses with different risk and income profiles.
- For investors who want quality at a discount, start by scanning a curated set of companies flagged as having attractively priced fundamentals through the 31 high quality undervalued stocks.
- If dependable income streams matter to you, focus on companies that pair higher yields with more durable balance sheets by reviewing the 7 dividend fortresses.
- For a more defensively tilted watchlist, consider businesses screened for stronger financial footing and lower overall risk scores via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com