


Westlake (WLK) Shuts Cologne PVC Plant, Is The Stock A Bargain?
Westlake (WLK) is back in focus after the company moved to close its polyvinyl chloride plant in Cologne, Germany. The step comes with sizeable charges and a reset of its European footprint.
Recent trading reflects that repositioning. Westlake’s share price has fallen 16.7% over the past month and is down 14.4% year to date, while the 1-year total shareholder return is lower by 20.8%, which points to fading momentum despite management’s push to cut higher cost capacity.
Scan how other chemicals and materials stocks with resilient balance sheets are positioned for capacity shifts using our hand picked list of solid balance sheet and fundamentals (26 results) as a starting list.
Bulls see Westlake using painful restructuring to set up a cleaner, more profitable PVC base. Bears see a shrinking footprint and heavy charges. Which story fits the current valuation?
Most Popular Narrative: 31% Undervalued
Against a last close of $63.50, the most followed narrative puts Westlake’s fair value near $92.31, which implies a sizeable valuation gap built on its assets, cost base and end market mix.
Westlake continues to benefit from having around 85% of Performance and Essential Materials production tied to North American natural gas and NGL feedstocks, which were largely unaffected by the recent oil price spike. This allowed a 21% sequential average sales price increase in Q2 2026 to flow through to margins and supported future earnings sensitivity to global polyethylene, caustic soda and PVC pricing.
See why 9 investors see Westlake as 31% undervalued.
Result: Fair Value of $92.31 (UNDERVALUED)
Still, if global oversupply keeps pressuring Performance and Essential Materials pricing or if higher feedstock costs return, the current Westlake upside narrative could unravel quickly.
Find out about the key risks to this Westlake narrative.
Another View: Westlake Through Future Cash Flows
The SWS DCF model presents a different view of Westlake. On that framework, the estimated future cash flow value is $49.73 per share, which is below the recent price of $63.50. That suggests an overvaluation risk rather than a simple discount story. Which lens do you give more weight to?
Look into how the SWS DCF model arrives at its fair value.
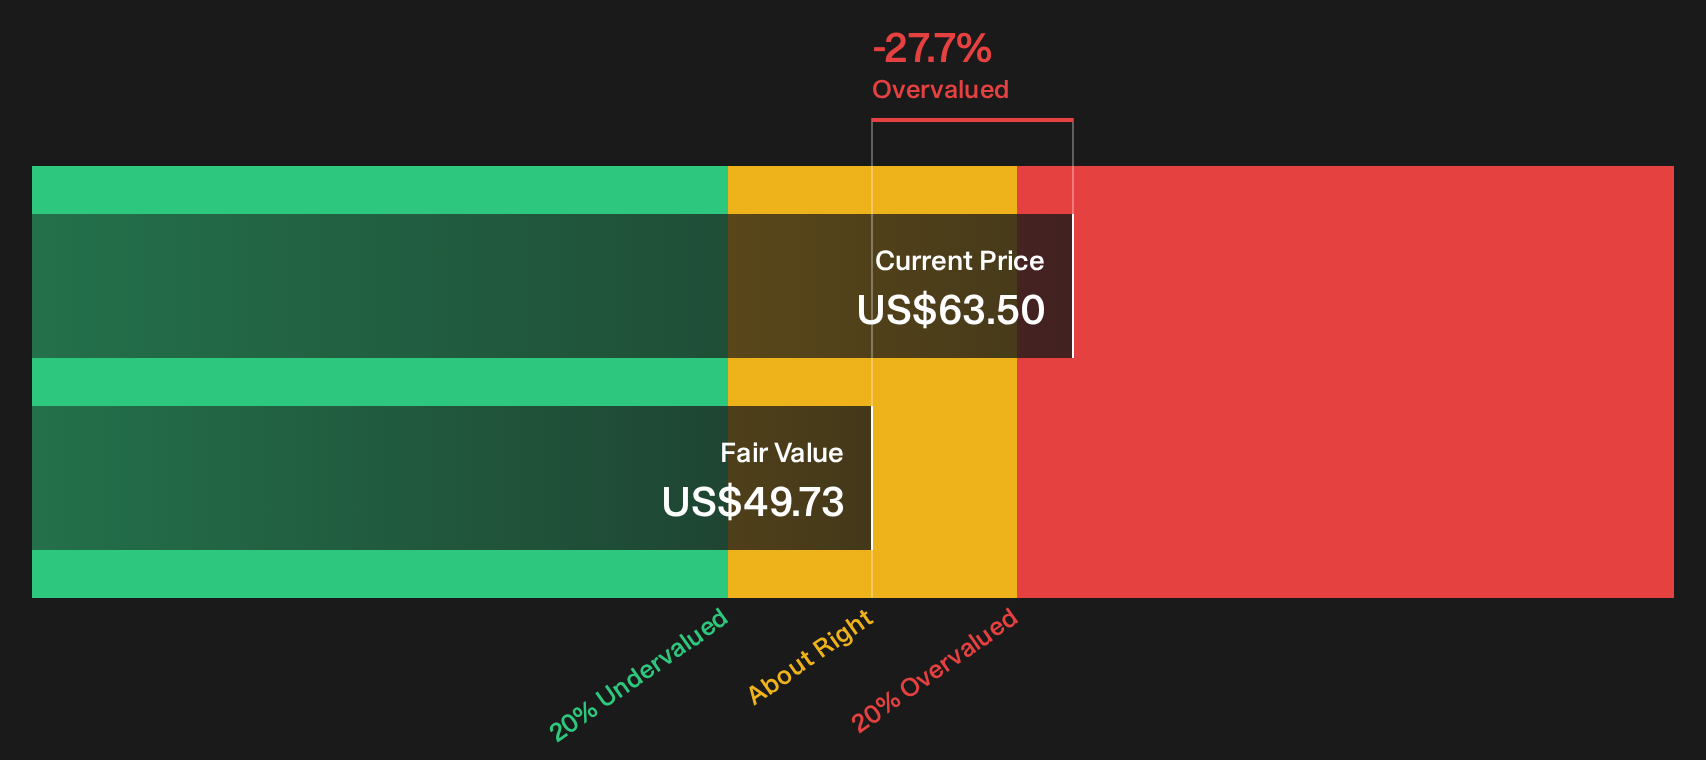
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Westlake for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 31 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Torn between Westlake’s restructuring pain and the potential benefits suggested by its valuation gap? Move quickly, weigh the evidence on both sides, and see the full picture through 3 key rewards and 1 important warning sign.
Looking for more Westlake sized investment ideas?
If Westlake has sharpened your focus on valuation and resilience, do not stop here. Broaden your watchlist now so you are not reacting after the move.
- Target value first and scan companies that combine quality fundamentals with pricing that still looks reasonable using the 31 high quality undervalued stocks.
- Secure income potential and review businesses built around robust payouts and higher yields with the 7 dividend fortresses.
- Prioritize resilience and stress test your portfolio with companies screened for stronger balance sheets via the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com