


3 Founder Led Stocks With Revenue Growth Up To 47%
Rising interest rates are reshaping how capital is priced, and that puts leadership under the spotlight. When borrowing is less forgiving, investors often pay closer attention to founders who still own a meaningful stake and make decisions with their own wealth on the line. This article explains why that mindset can matter now and highlights three founder-led stocks from our screener that may be worth a closer look.
The three founder-led stocks below are only a sample, and the full screen surfaced 329 more companies with equally compelling narratives that are not covered here. If you want to identify founder-operators whose incentives are tightly aligned with shareholders, go straight to the Founder-Led Companies screener.
Tesla (TSLA)
Tesla is the purest expression of the founder-led theme in this list, with Elon Musk’s fingerprints on everything from vehicle design to in-house AI. This makes how the business earns its money and is valued by the market especially important for investors to understand.
Tesla, Inc. is a founder-led business focused on electric vehicles and in-house software, with most of its US$103.6b revenue coming from Automotive at about US$90.8b and a smaller Energy Generation and Storage arm at roughly US$12.8b. The stock carries a market value near US$1.4t.
Tesla is pursuing a range of ambitious and, in some cases, speculative opportunities: AI leadership, robotaxis, humanoid robotics, and battery storage.
What happens to Tesla’s long term earnings power if a single key assumption in that founder-driven expansion path breaks under real world pressure?
If that question is front of mind, read the full narrative for Tesla to see how Tesla’s big bets, risks and optionality all tie together.

Meta Platforms (META)
Meta Platforms is a clear example of a founder still steering a massive consumer internet empire. Mark Zuckerberg is using the company’s large social and messaging franchise to fund more speculative projects that fit squarely with the founder-led theme.
Meta Platforms, Inc. runs Facebook, Instagram, WhatsApp, Messenger, Meta AI and other services under its Family of Apps, which generated about US$226b in revenue, while Reality Labs added roughly US$2.3b from VR, AR and wearables. The stock carries a market value near US$1.85t.
Reality Labs lost $19.19 billion in 2025. On $2.21 billion in revenue.
Whether that founder-driven gamble ultimately strengthens Meta’s earnings power now depends on how one massive, long-lived spending commitment plays out.
That commitment is only the starting point, and the full narrative for Meta Platforms shows how Meta Platforms could turn heavy Reality Labs spending into accelerating earnings power or a controlled reset.

Space Exploration Technologies (SPCX)
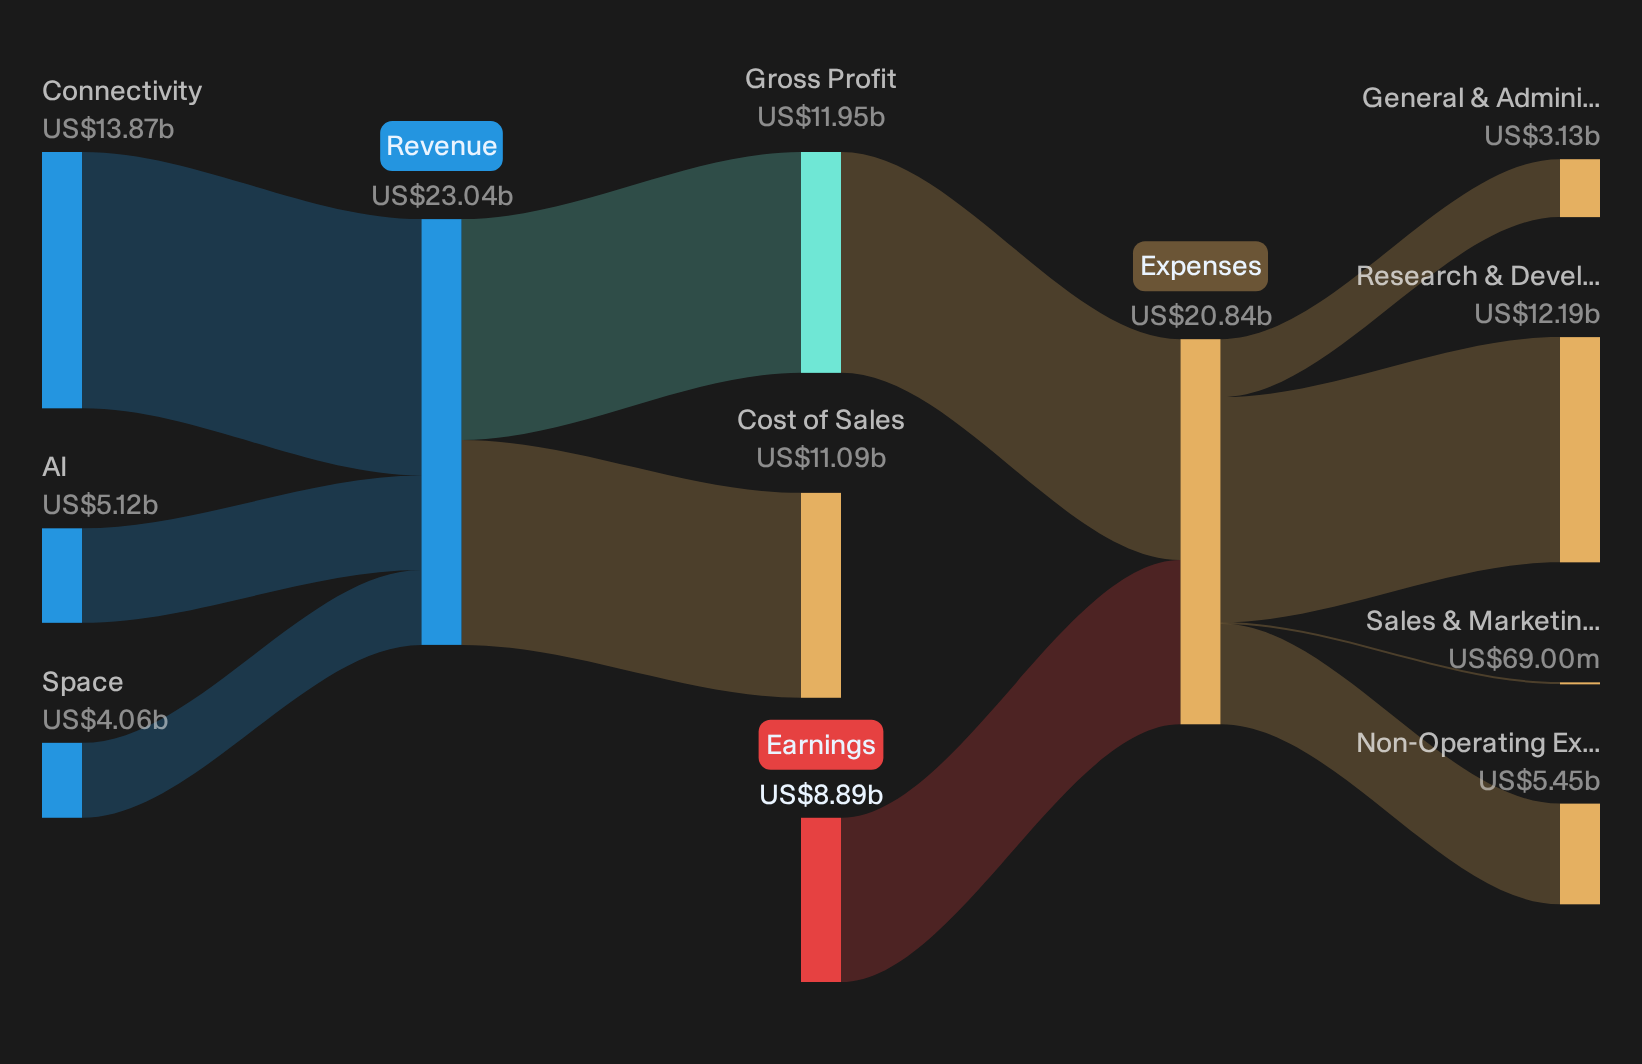
Space Exploration Technologies ties Elon Musk’s founder mindset directly to Starlink, while also running a large launch and AI infrastructure business. The group generated US$13.9b from Connectivity, US$5.1b from AI and US$4.1b from Space, and carries a roughly US$2,009.7b market cap.
Space Exploration Technologies fits this founder-led screen because Starlink is not just a product; it is Musk’s main commercial vehicle for turning his long-term space ambitions into a cash-generating enterprise.
Starlink satellite internet is currently the main driver of revenue and is the only division reporting an operating profit.
What really matters now is how one unresolved constraint around scaling that profitable engine filters through to funding costs and future margins.
That funding question is exactly where the full narrative for Space Exploration Technologies shows how Starlink’s cash engine, capital intensity and AI ambitions could be accelerating, or quietly stalling, future returns.
Seeking Fresh Alternatives Before They Fly?
New ideas move fast. The most interesting stories often shift from quiet to breakout before the crowd catches on. Scan these fresh shortlists while it matters and get in early.
- Chase income that can keep working even when prices whip around by running through a curated set of 7 dividend fortresses built on sturdy cash flows and balance sheets.
- Spot potential compounding engines before they hit every headline by filtering through 19 high quality undiscovered gems that pair clean financials with under-the-radar momentum and business quality.
- Stay ahead of the next buildout wave by reviewing 40 power grid technology and infrastructure stocks geared toward companies linked to grid upgrades, electrification projects and long-term infrastructure spending.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com