


Fevertree Drinks And 2 British Founder Led Stocks To Watch
With UK energy suppliers urging urgent government action on rising household bills, British investors face a simple question: who feels the squeeze, and who has the resilience to keep compounding value? Founder-led businesses with significant insider ownership bring a different mindset, as their leaders have more on the line than a bonus. This article highlights three such UK stocks from our screener that align management incentives with yours.
The three founder-led stocks below are only a sample from this idea, and the full screen surfaced 5 more businesses with equally compelling insider stories that are not covered here. To identify and analyze the leaders most aligned with your capital, head straight into the Top Founder-Led Companies screener.
Fevertree Drinks (AIM:FEVR)
Overview: Fevertree Drinks develops and sells premium mixer beverages under the Fever-Tree brand. Founder-led branding tightly aligns products with this screener’s focus on committed insider ownership.
Operations: Fevertree Drinks generates revenue across the United Kingdom (£109.8 million), Europe (£102.3 million), the United States (£94.9 million) and the Rest of the World (£38.8 million).
Market Cap: £938.1 million
Fevertree Drinks matters for this founder-led screen because the premium mixers that built the brand are still steered by the original insiders, tying long-term decisions directly to owner outcomes rather than short-term incentives.
"The partnership with Molson Coors is intended to secure U.S. profit growth, but an overreliance on one strategic partner may expose Fevertree to unfavorable contract renegotiations, possible margin dilution if guaranteed royalties fail to match rising costs, and slower-than-expected U.S. market penetration, all of which could weigh on future profits."
The real test for Fevertree Drinks now is how one unresolved pressure shapes future pricing power and earnings quality over time.
That unresolved pressure is exactly why the full narrative for Fevertree Drinks digs into how Fevertree Drinks could turn contract risk into accelerating brand reach and stronger owner alignment.

Computacenter (LSE:CCC)
Overview: Computacenter delivers large scale IT sourcing, support, and long-term managed services for corporate and public sector clients worldwide, aligning founder-led ownership with multi-year outsourcing contracts.
Operations: Computacenter generates £12.1b from Computer Services globally, with major contributions from the United States, United Kingdom, Germany, and Western Europe.
Market Cap: £5.7b
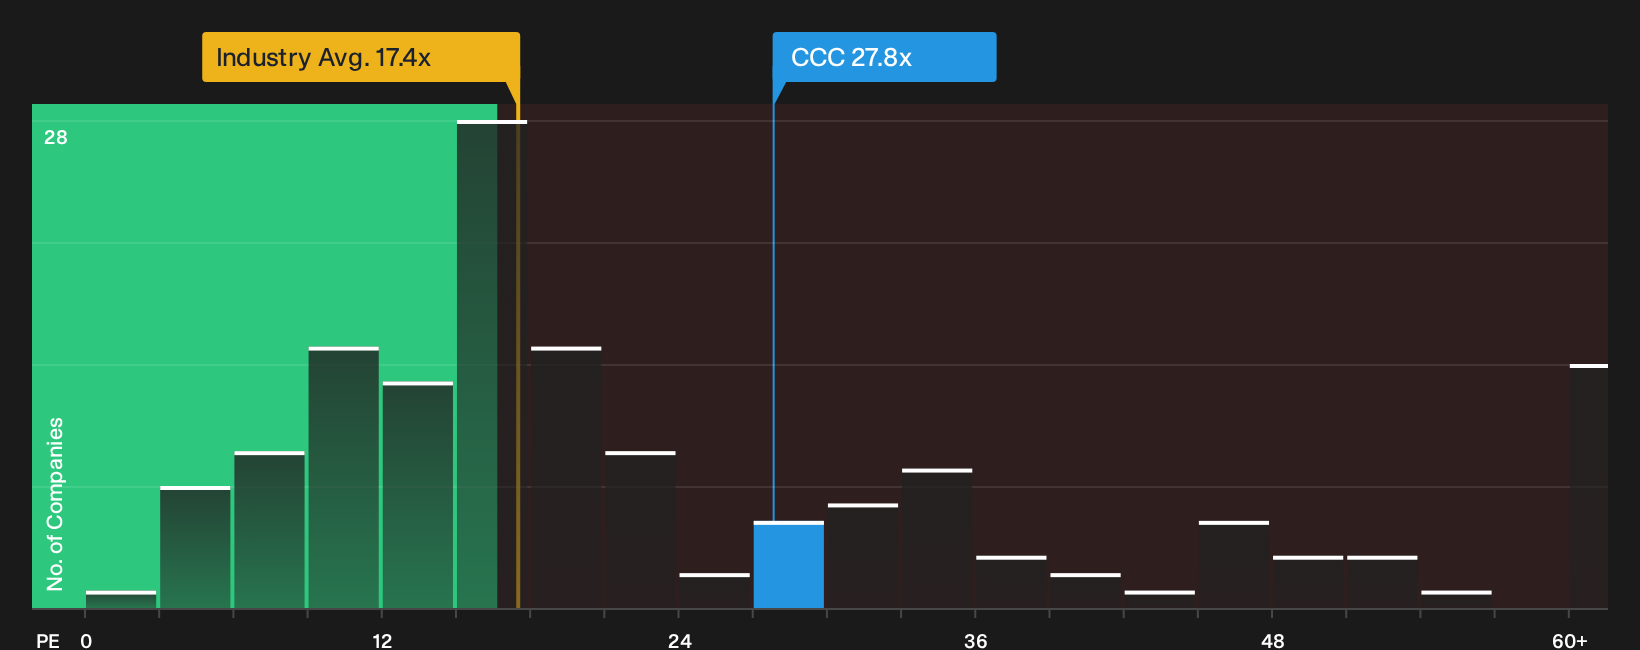
Computacenter ties founder-led ownership directly into long-running IT outsourcing relationships, with trailing 12-month earnings up 27.9% and ROE at 21.1%. The richer P/E multiple and thinner 1.7% margin highlight the importance of those multi-year contracts and board stability. A single pressure on pricing could reshape renewals and would be important for investors to monitor.
Those contract terms are exactly why the analysis report for Computacenter could help you see whether Computacenter’s earnings strength is masking pressure or setting up the next leg of compounding.
Applied Nutrition (LSE:APN)
Overview: Applied Nutrition manufactures and markets founder-led sports nutrition and wellness products, with branded proteins, BCAAs, pre-workouts and related supplements.
Operations: Applied Nutrition generates £134 million from sports nutrition products, with £58.3 million from the United Kingdom, £57.7 million internationally and £18 million across Europe.
Market Cap: £664 million
Applied Nutrition fits this founder-led list because the same insiders who built its sports nutrition brands are still steering product, pricing and expansion decisions. This structure ties long-term wealth creation directly to how well those powders, cans and supplements earn repeat customers.
"Expansion into new geographies such as Eastern Europe, Latin America, Asia and Canada via a scalable B2B distributor model may create a long runway for international penetration with limited incremental fixed cost, which could underpin future revenue trends and EBITDA margin resilience."
What really moves the needle now is how one less visible pressure ultimately shapes the balance between faster distribution reach and unit profitability.
If that trade off is what you care about, read the full narrative for Applied Nutrition to see whether Applied Nutrition’s expanding distributor network is accelerating or quietly straining returns.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the most interesting stories rarely stay under the radar for long. Scan fresh ideas showing real momentum before the crowd catches on, then consider your options promptly.
- Hunt for income workhorses using the 1 dividend fortresses and see which high-yield payers still pair distributions with balance sheets built to endure.
- Spot companies involved in automation with the 90 robotics and automation stocks and track curated selections connected to the shift toward smarter factories, warehouses and industrial systems.
- Focus on companies with resilient balance sheets through the list of solid balance sheet and fundamentals (9 results) so potential capital protectors and steady compounders do not slip past you.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com