


Ensign Group (ENSG) Could Be 22% Undervalued On Its Acquisition Turnaround Story
Ensign Group (ENSG) has drawn fresh attention after its recent share move, with the stock closing at US$171.78. That price invites closer inspection of its returns and fundamentals over different time frames.
Recent trading has been choppy for Ensign Group, with a 1-day share price return of 1.27% contrasting with a 7-day share price return that declined 1.94%. The 1-year total shareholder return is slightly negative, and the 5-year total shareholder return of 139.36% points to stronger long-term momentum than the near term suggests.
See how Ensign Group compares with other resilient operators by exploring our hand picked list of list of solid balance sheet and fundamentals (26 results).
Ensign Group looks like a solid operator on the surface, yet the recent share move around US$171.78 raises a sharper issue. Are investors paying a fair price for that quality today, or stretching too far?
Most Popular Narrative: 21.9% Undervalued
The most followed valuation narrative pegs Ensign Group’s fair value at $220 per share, compared with the recent close at $171.78. This puts the current move squarely in the spotlight for anyone weighing upside against execution risk.
A sizeable pipeline of low occupancy, clinically challenged acquisitions, particularly in Texas, creates room for operational turnaround using the existing cluster and ONE CLINICAL model. This can affect occupancy driven revenue and EBIT over multi year periods.
See why 1 investors see Ensign Group as 22% undervalued.
Result: Fair Value of $220 (UNDERVALUED)
Still, the Ensign Group story can unravel if government reimbursement tightens or if the recent wave of low occupancy acquisitions takes longer to turn profitable.
Find out about the key risks to this Ensign Group narrative.
Another View On Ensign Group’s Valuation
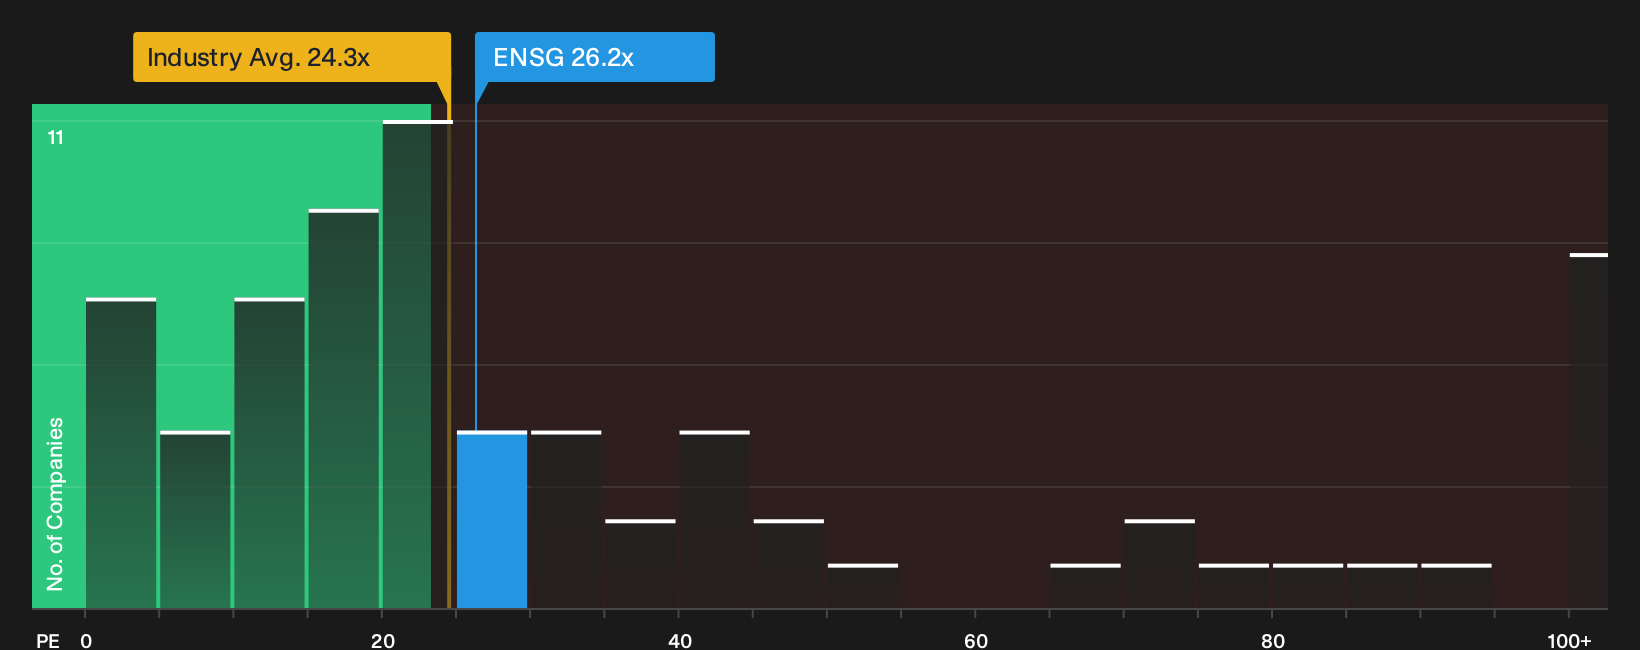
There is a catch with Ensign Group on simple earnings multiples. The stock trades on a P/E of 26.2x, which is higher than both the US Healthcare industry at 24.1x and its peer average at 15.2x, and even sits above an estimated fair ratio of 25.6x. That gap points to a richer pricing that could compress if sentiment cools. The key question is whether you think the quality of the business justifies paying up today.
For a closer look at how this earnings based view stacks up against detailed valuation work, check the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling mixed about the tone around Ensign Group after all these numbers. Use the data, look at the context, and quickly decide what story you believe, then check the 4 key rewards
Looking for more investment ideas beyond Ensign Group?
If Ensign Group has sharpened your focus on quality and price, do not stop here. Broaden your watchlist using targeted stock ideas built from data driven screeners.
- Target potential value opportunities before they get crowded by reviewing a curated set of 31 high quality undervalued stocks.
- Strengthen your income stream by focusing on companies that aim to sustain payouts through a focused group of 7 dividend fortresses.
- Dial down portfolio stress and concentrate on resilience by scanning a refined pool of 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com